Compare your deck to N26

Compare Your Deck

N26 Pitch Deck (2015)

Fintech
Stage: Various
Raised: Multiple
Year: 2015
Slides: 22
Outcome: Valued at $9B

Pitch Deck

1 / 22
N26 pitch deck - The Opening: Brand + Problem Framing
Click to expand

Deck Analysis

This deck for N26 presents a crisp, design-forward pitch for a mobile-first challenger bank focused on European expansion and fintech platformization. It pairs strong visual storytelling (hero imagery, simple typography) with concrete product highlights, traction metrics, partner integrations, and a clear geographic expansion plan — helping investors quickly understand the market opportunity, product differentiation, and early execution. Notable is how the deck balances brand emotion (lifestyle photography, millennial-oriented messaging) with operational proof points (fast account opening, partner integrations, user growth), making it a useful template for consumer fintech founders.

The Opening: Brand + Problem Framing

The Opening: Brand + Problem Framing

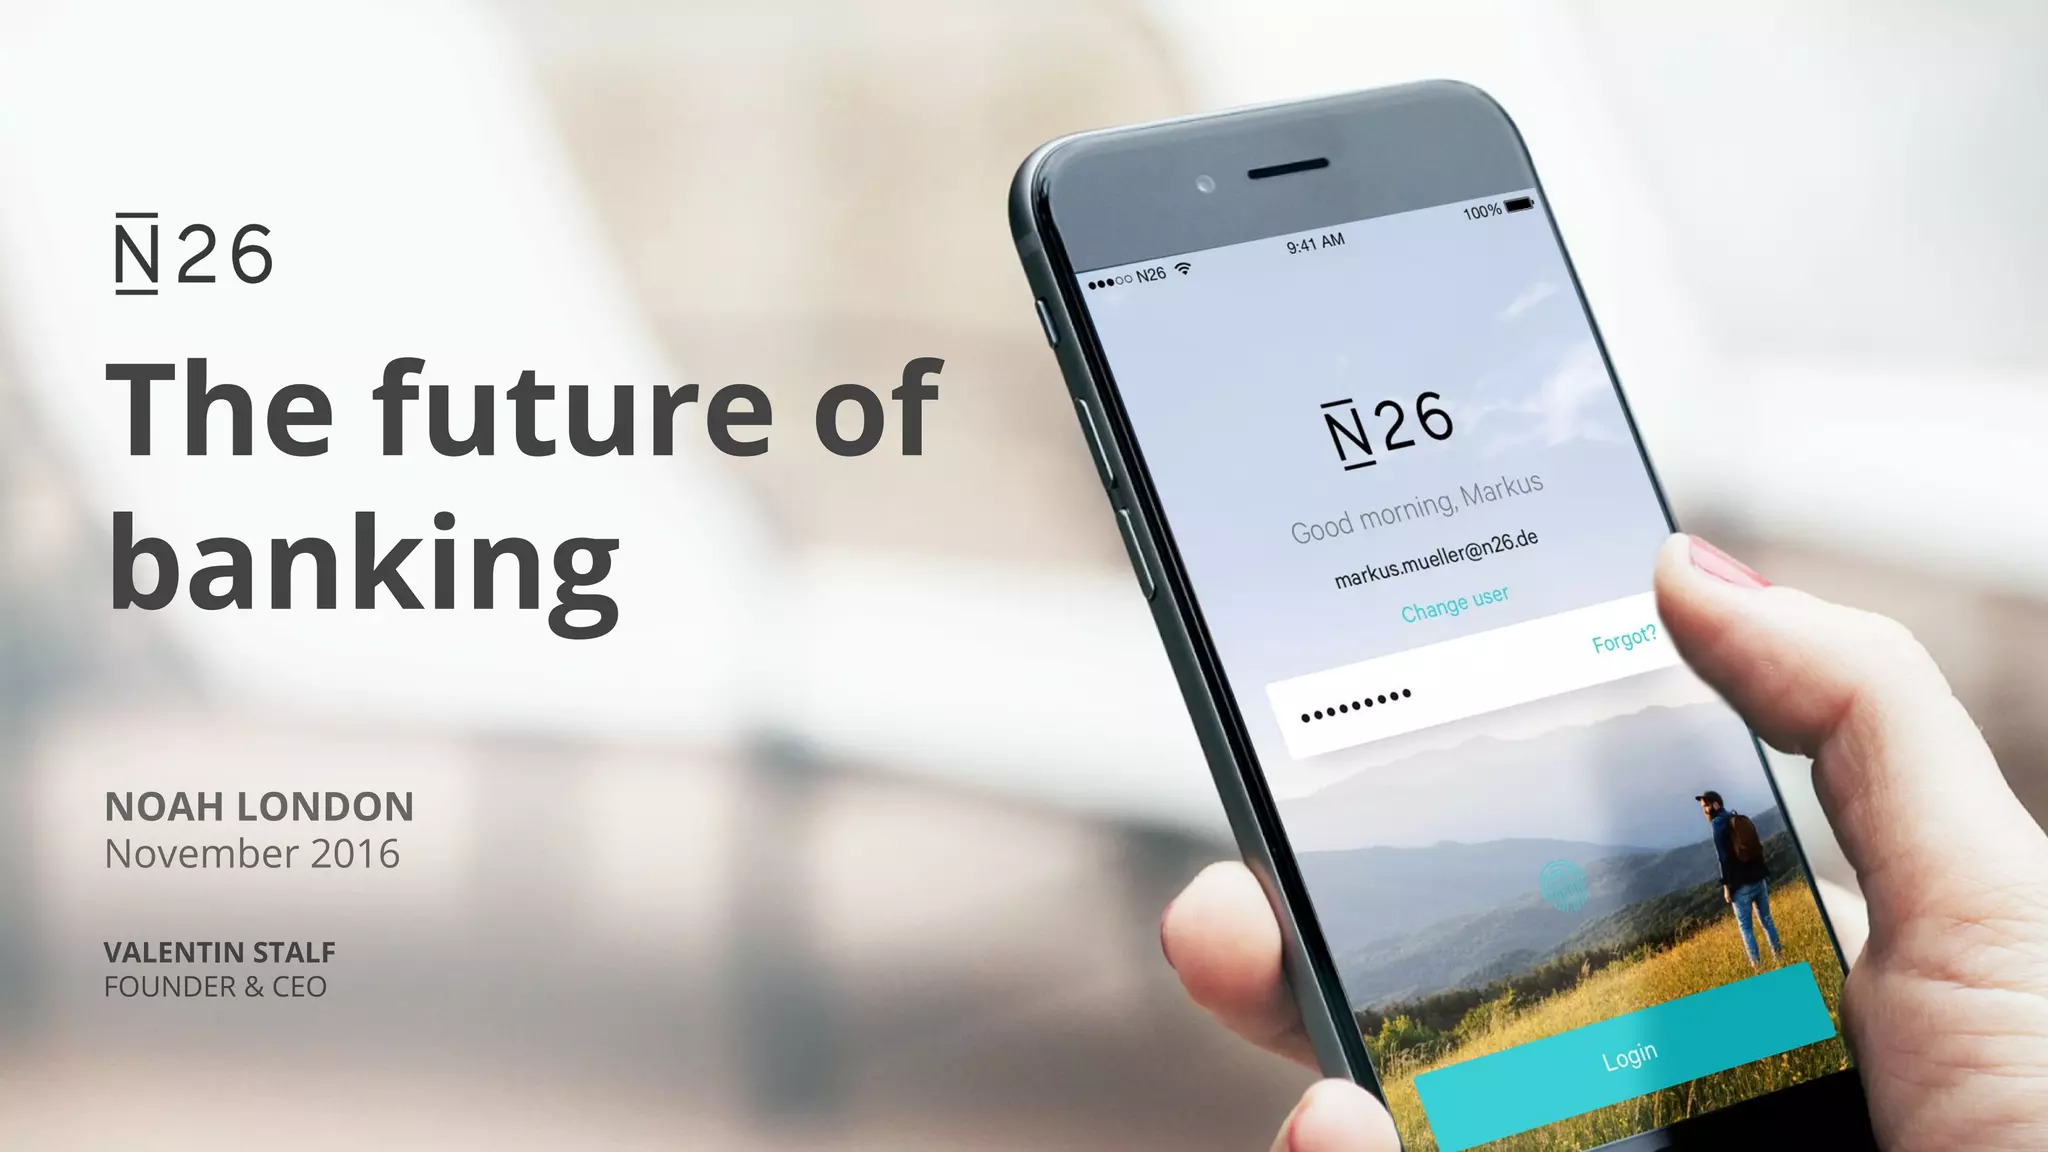
Slide 1 opens with a bold visual and a short, memorable tagline: "The future of banking." The hero image of the mobile login screen immediately communicates the product context (mobile-first banking) while the slide credits and date anchor the pitch historically. This slide is effective because it sets an emotional tone and communicates product-category fit in under five seconds — essential for investor attention in early deck review.

Founders can learn from the economy of this slide: lead with a strong visual that shows the product in-context, pair it with a single declarative line about the company mission, and include minimal logistical details (event, date, presenter) so the audience knows why they should keep watching. The slide signals confidence without overwhelming viewers with data, making it an ideal opener to segue into problem and traction slides.
Key Takeaway: Open with a clean, product-in-context visual plus a single mission line to immediately communicate what you do and who you serve.
Problem Statement: Customer Sentiment & Market Pain

Problem Statement: Customer Sentiment & Market Pain

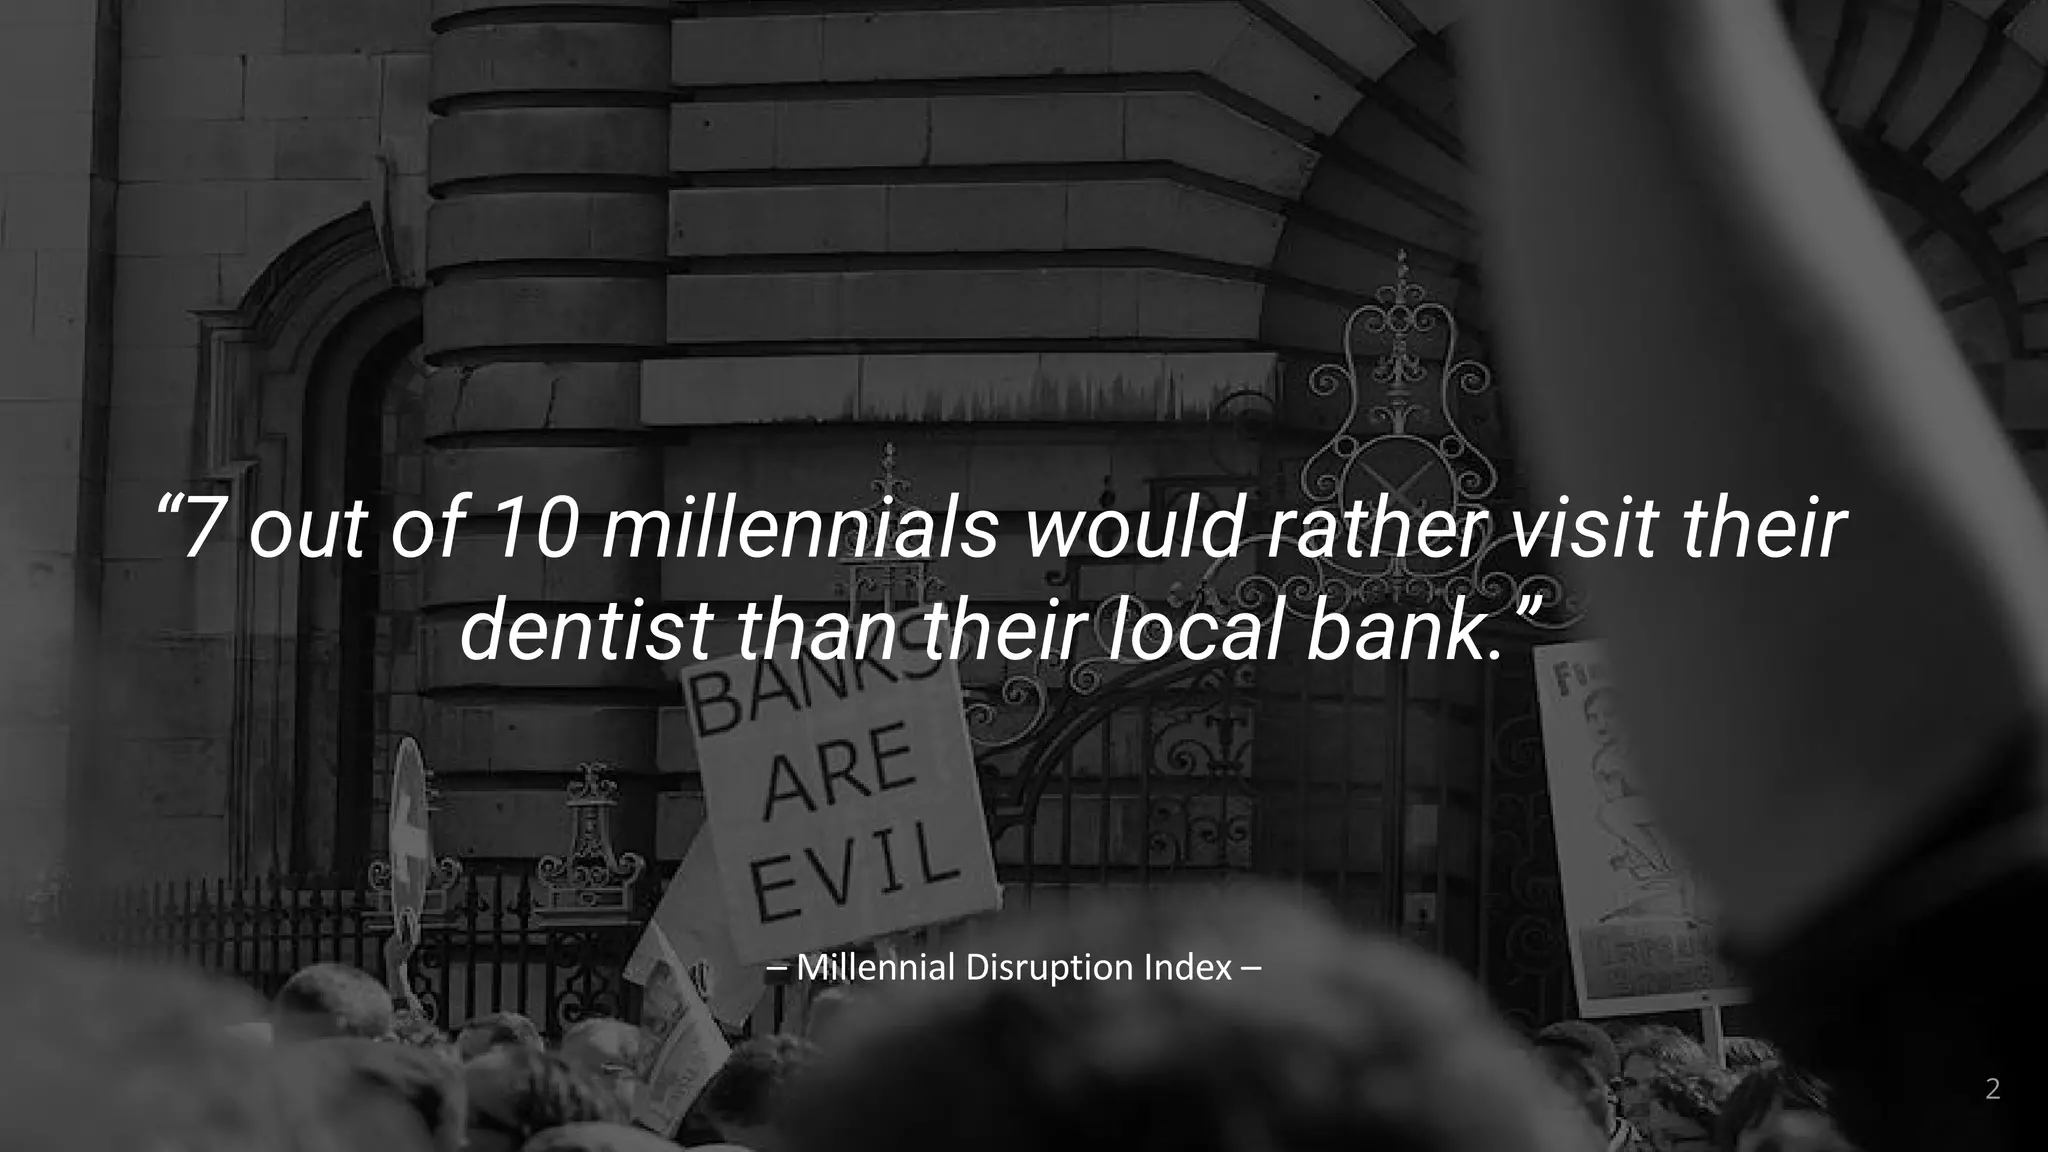
Slide 3 uses a striking statistic — “7 out of 10 millennials would rather visit their dentist than their local bank” — paired with a moody image of protest signage to dramatize distrust in traditional banks. This kind of social-proof-based problem framing is effective because it quantifies dissatisfaction and ties it to a specific demographic segment valuable to fintechs: millennials. The slide sets up a strong why: there is a real behavioral gap that a modern digital bank can address.

For founders, this demonstrates how to present a problem with emotion and scale: show a market sentiment or behavioral stat that resonates and back it with evocative imagery. It’s important, however, to ensure the statistic is credible and sourced in the appendix or pitch notes so investors can validate the claim during diligence.

Key Takeaway: Use a concise, emotionally resonant statistic to make the market problem tangible — but be ready to cite the source in follow-up materials.
Product Overview: Core Capabilities and Differentiators

Product Overview: Core Capabilities and Differentiators

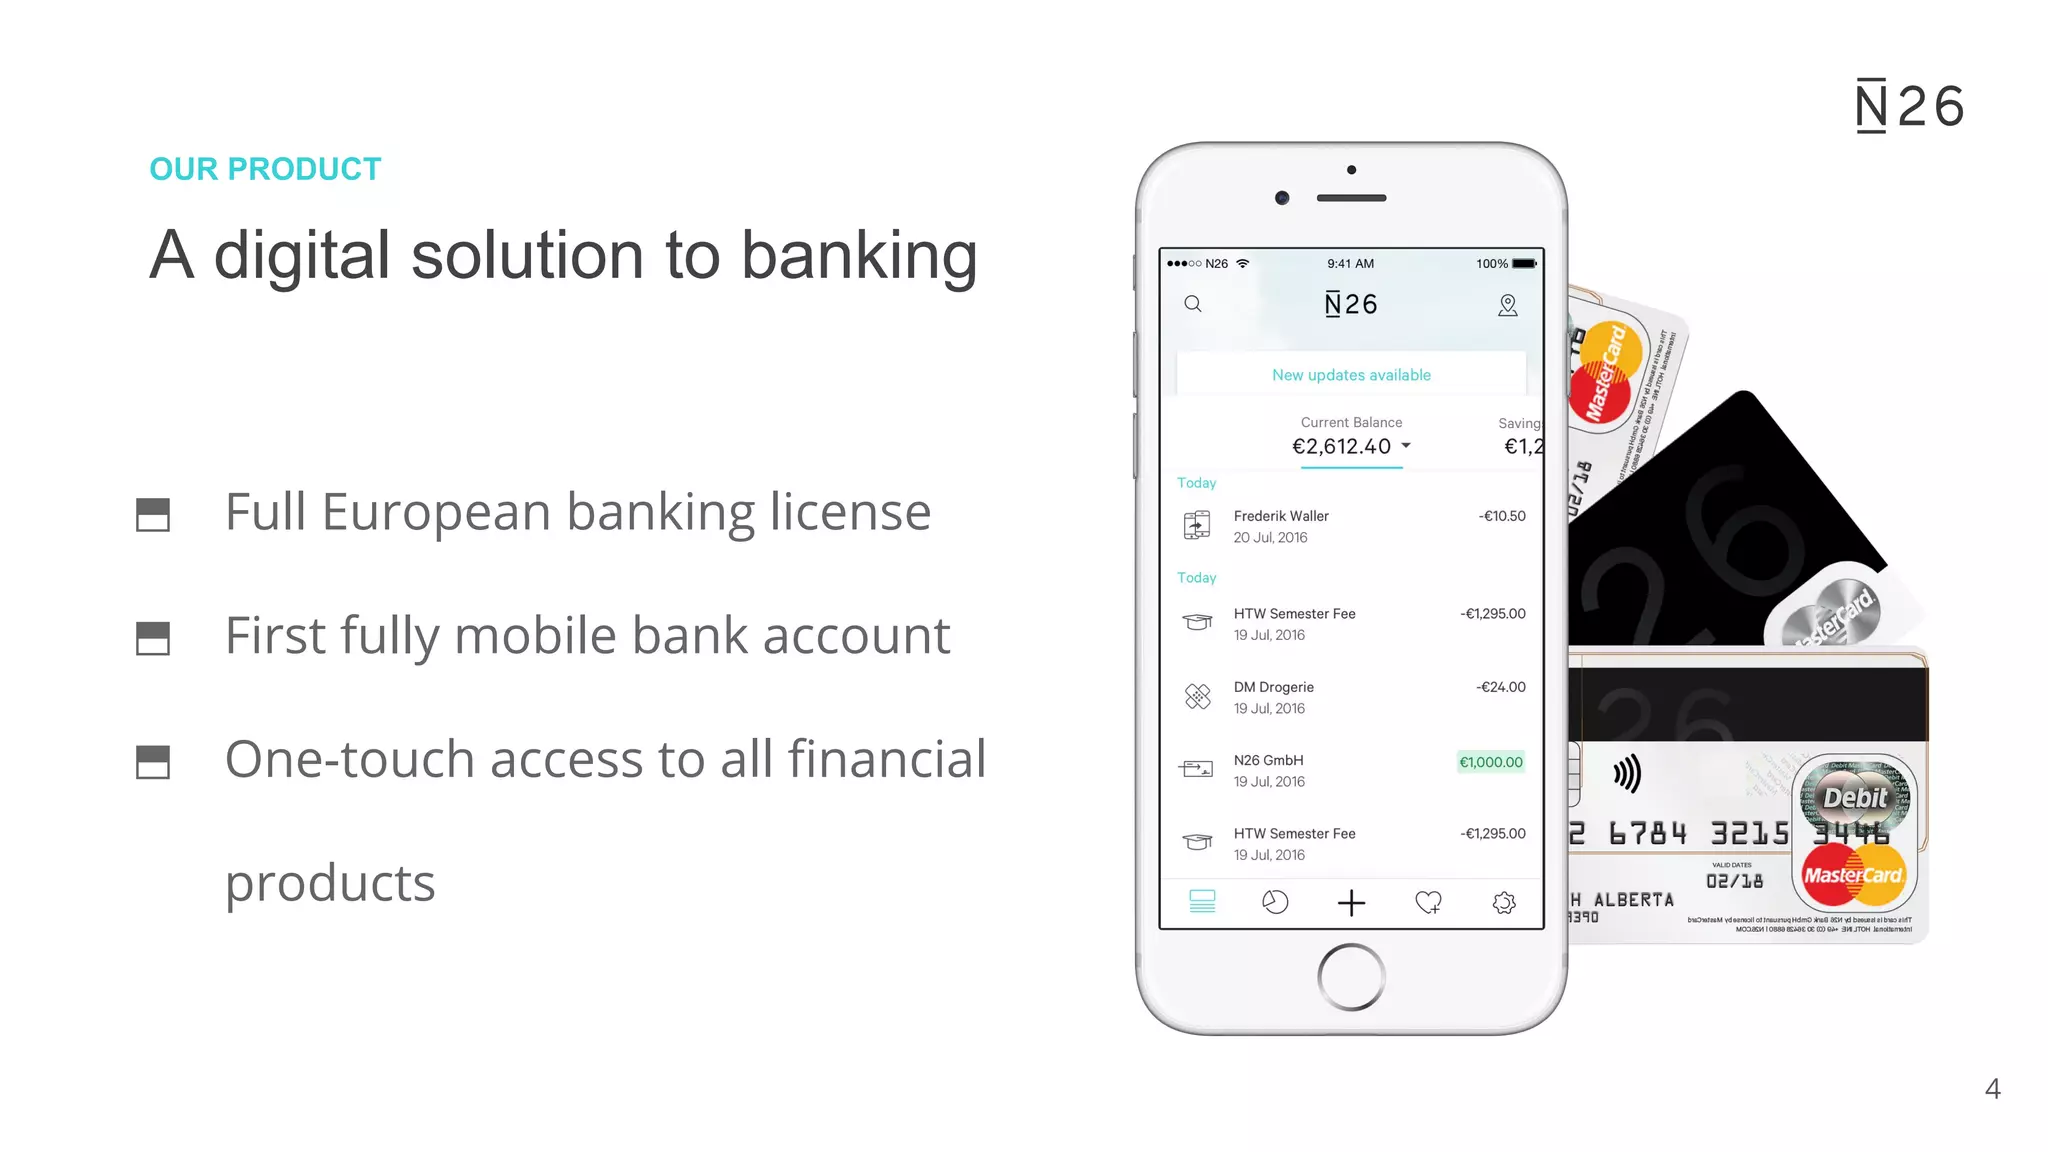
Slide 5 provides a short product summary — "A digital solution to banking" — with three bullet points: full European banking license, fully mobile account, and one-touch access to financial products. The visual of the app and cards reinforces the product experience while the bullets call out regulatory and UX differentiators. This combination of product visuals and succinct feature bullets helps investors quickly understand why N26 is more than just another banking app.

The slide is a good example of balancing product detail with accessibility: it names must-have credentials (banking license) that de-risk the business for investors while highlighting user-facing features that drive adoption. Founders should emulate this mix: present the technical or regulatory credentials that matter to investors alongside the UX benefits that matter to users.

Key Takeaway: Combine regulatory/operational proof points with simple UX benefits to communicate both defensibility and customer value.
Speed & Convenience as a Go-to-Market Lever

Speed & Convenience as a Go-to-Market Lever

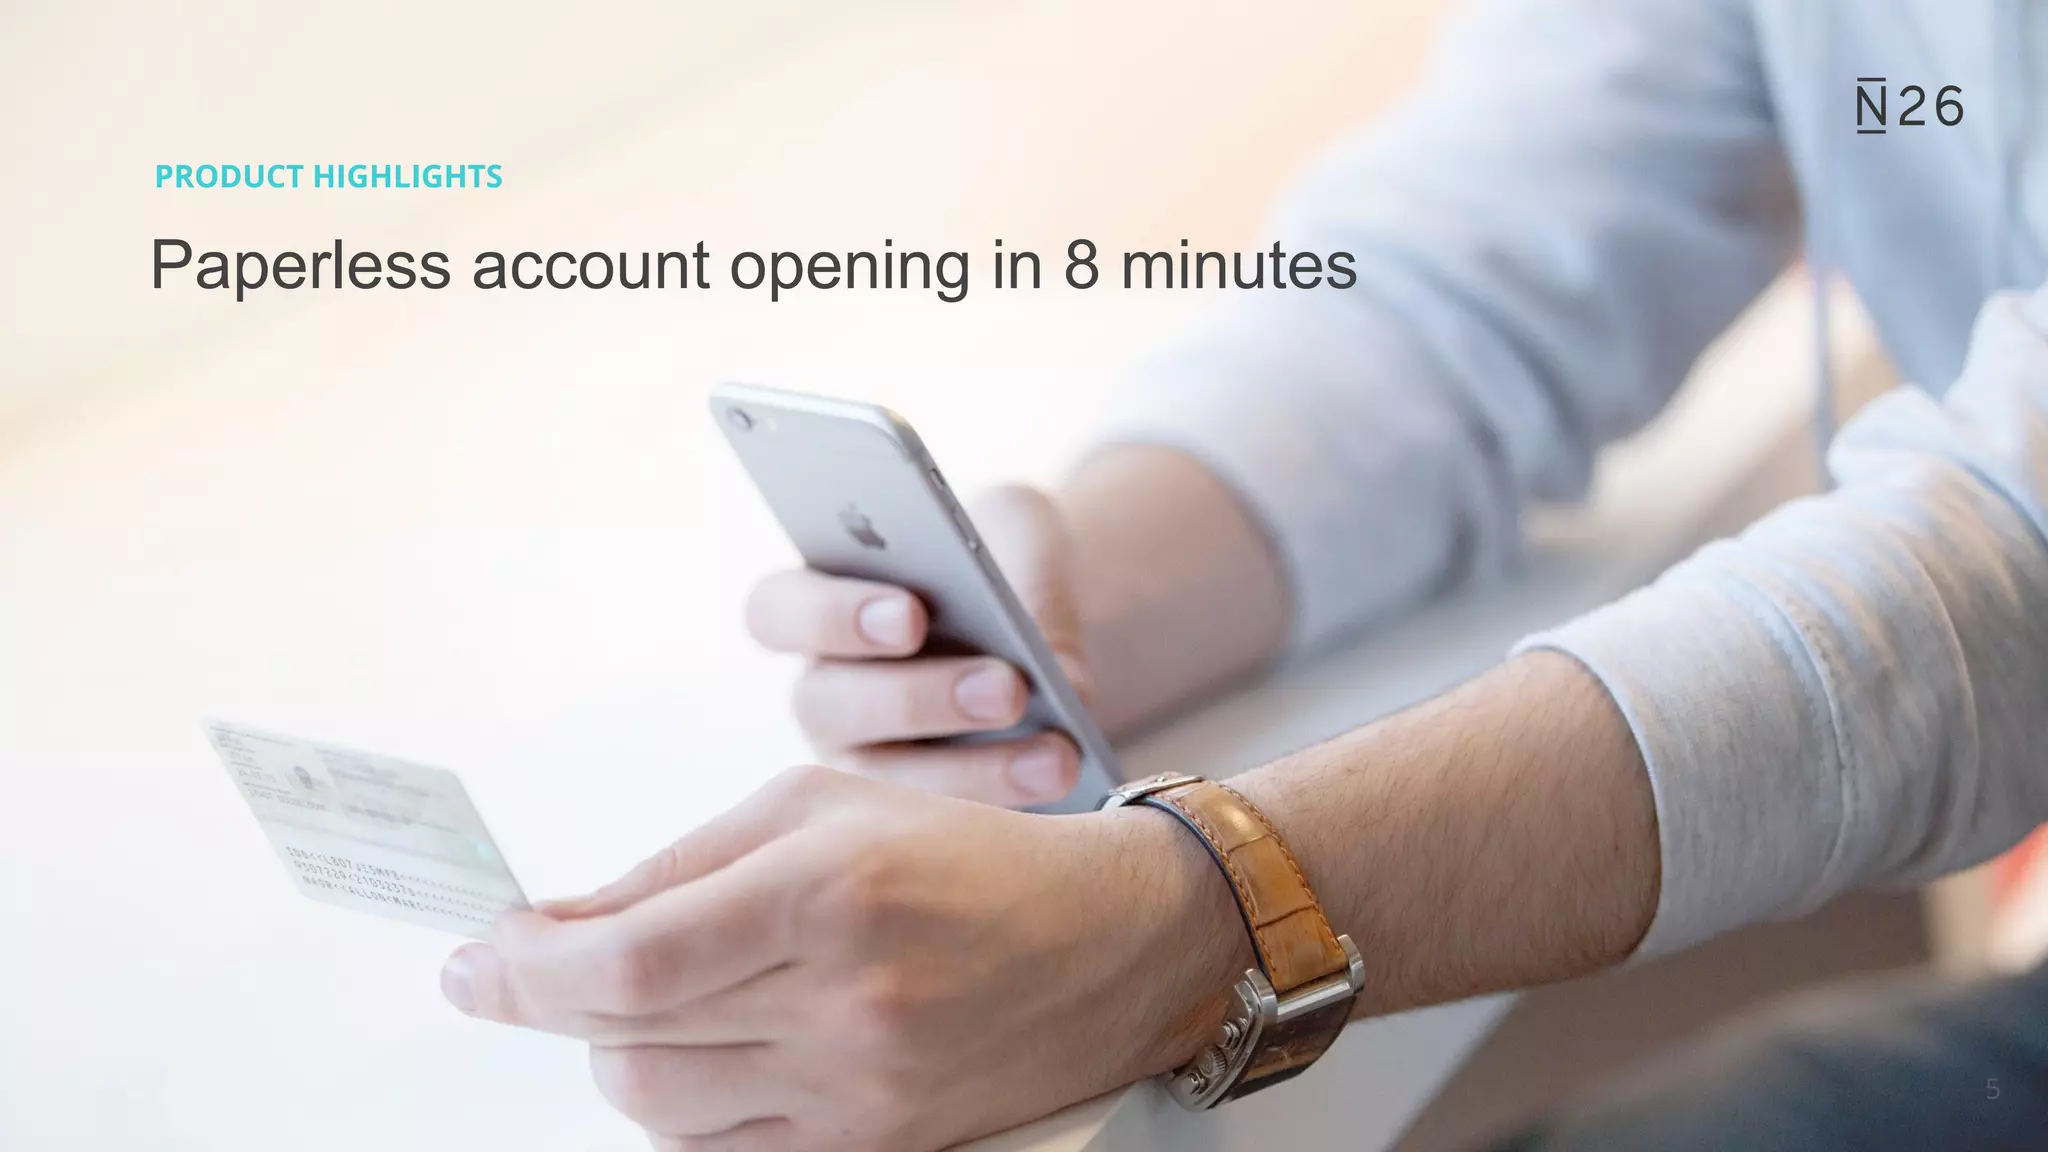
Slide 6 focuses on a high-impact product metric: "Paperless account opening in 8 minutes." The slide uses a lifestyle photo and a single large headline to make the speed of onboarding the star. Operational metrics like time-to-activate are powerful because they translate directly into acquisition efficiency, funnel conversion, and CAC. For digital consumer financial products, reducing friction at sign-up is often one of the easiest levers to show measurable improvement in growth metrics.

The lesson for founders is to quantify user experience improvements and call them out as competitive advantages. If you can demonstrate a faster, cheaper, or more secure onboarding journey than incumbents, make that a primary message and be prepared to show the underlying flow and metrics in appendices or demos.

Key Takeaway: Highlight concrete user-experience KPIs (e.g., minutes-to-open) that map to acquisition and activation improvements.
Product Ecosystem: Partnerships and Retail Presence

Product Ecosystem: Partnerships and Retail Presence

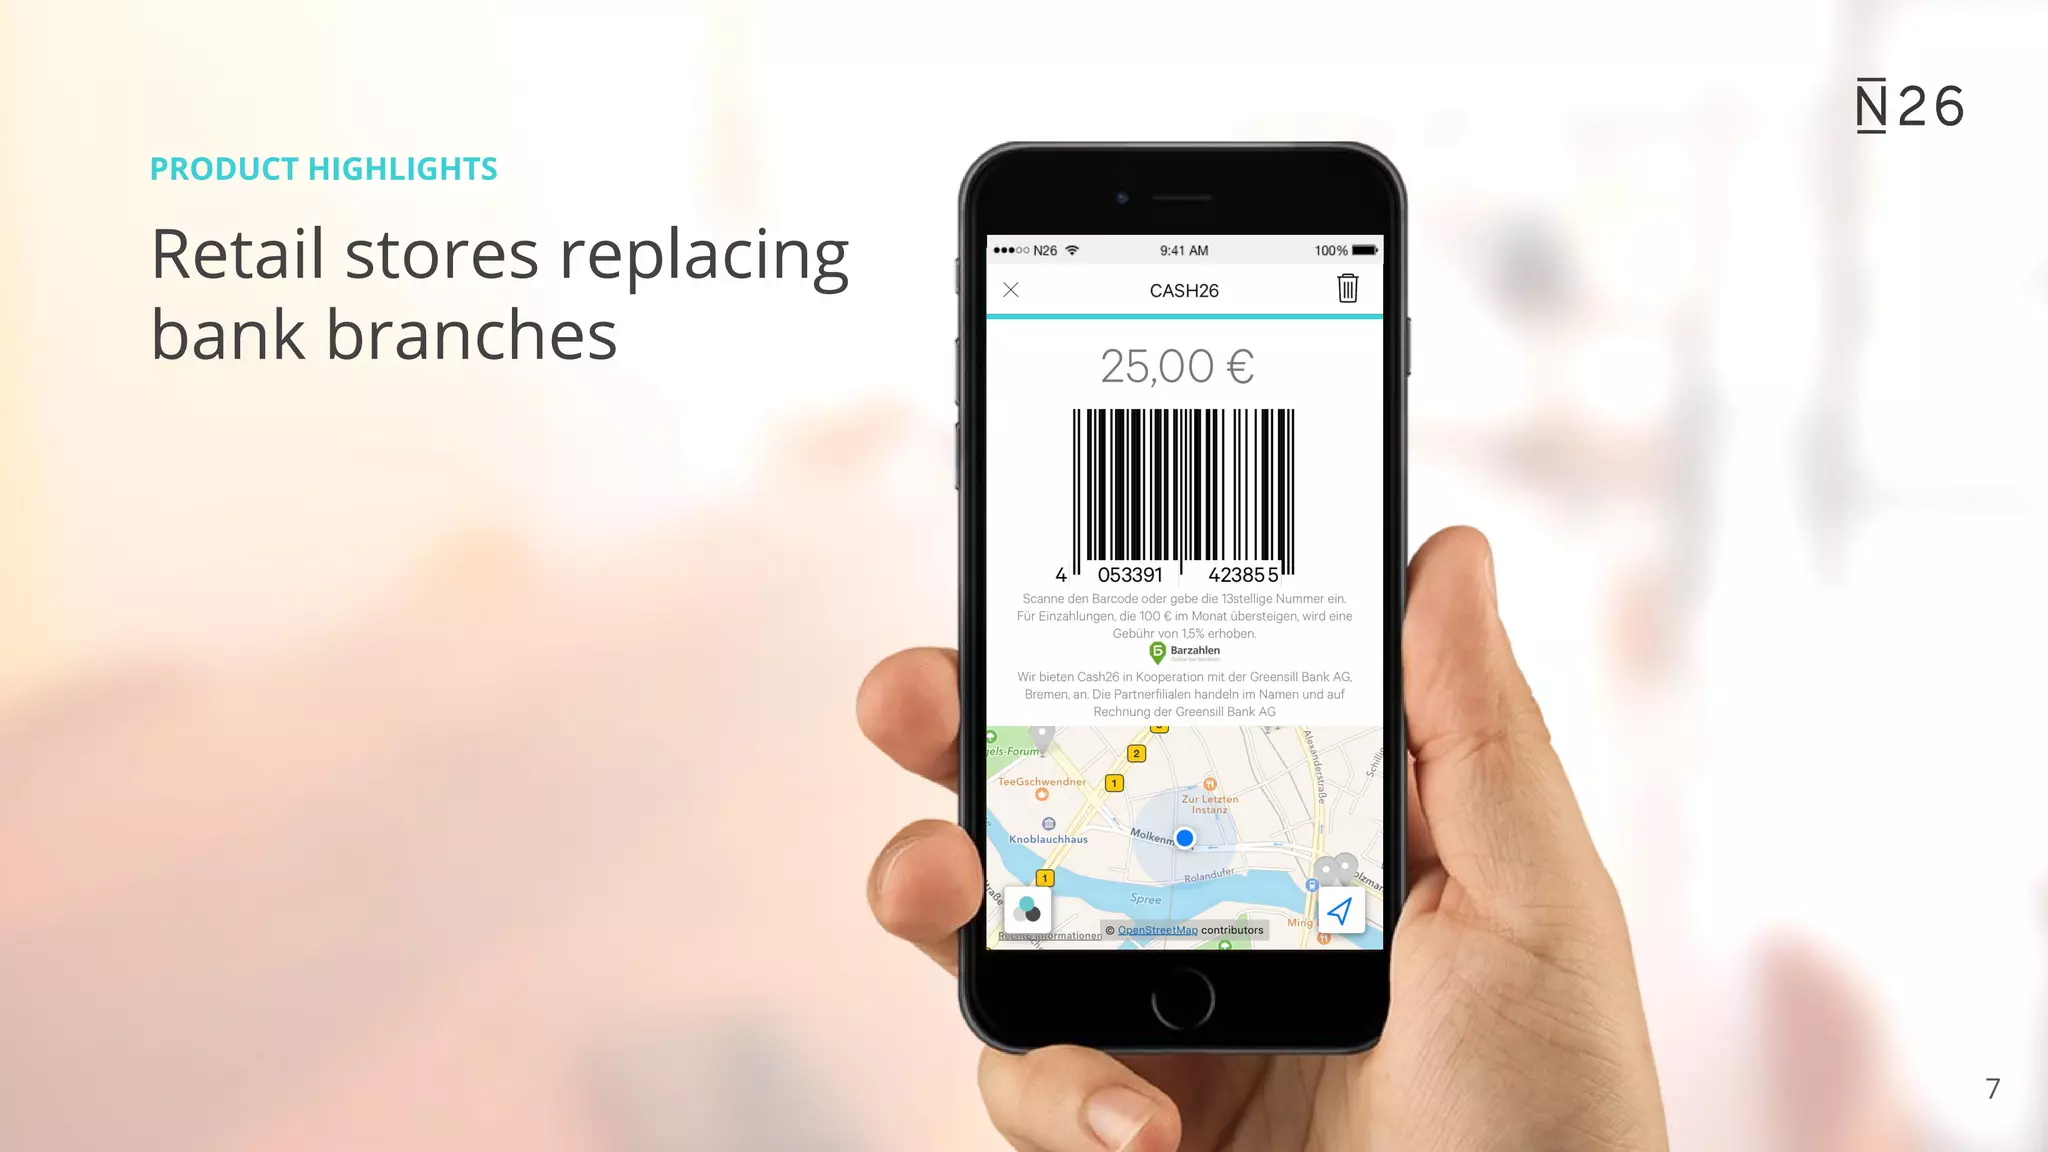
Slide 8 showcases the "retail stores replacing bank branches" value proposition with an example feature (CASH26 barcode) displayed on an in-app screen. This slide communicates a physical-digital hybrid strategy: instead of traditional branches, N26 leverages retail partners to enable cash in/out and broader distribution. It’s an effective way to explain how a mobile-first bank can still deliver essential offline capabilities without the cost of branch networks.

Founders should consider this slide as a template for explaining ecosystem plays: show the feature, explain the partner model, and emphasize the customer benefit. Partnerships that extend product functionality or distribution can be compelling evidence of scalability and unit-economics optimization — include logos, usage metrics, or partner terms in backups to strengthen the claim.

Key Takeaway: Use partner integrations to solve offline needs cost-effectively — show the feature UX plus the partner model to illustrate execution.
Expansion & Monetization Features: Financial Services Stack

Expansion & Monetization Features: Financial Services Stack

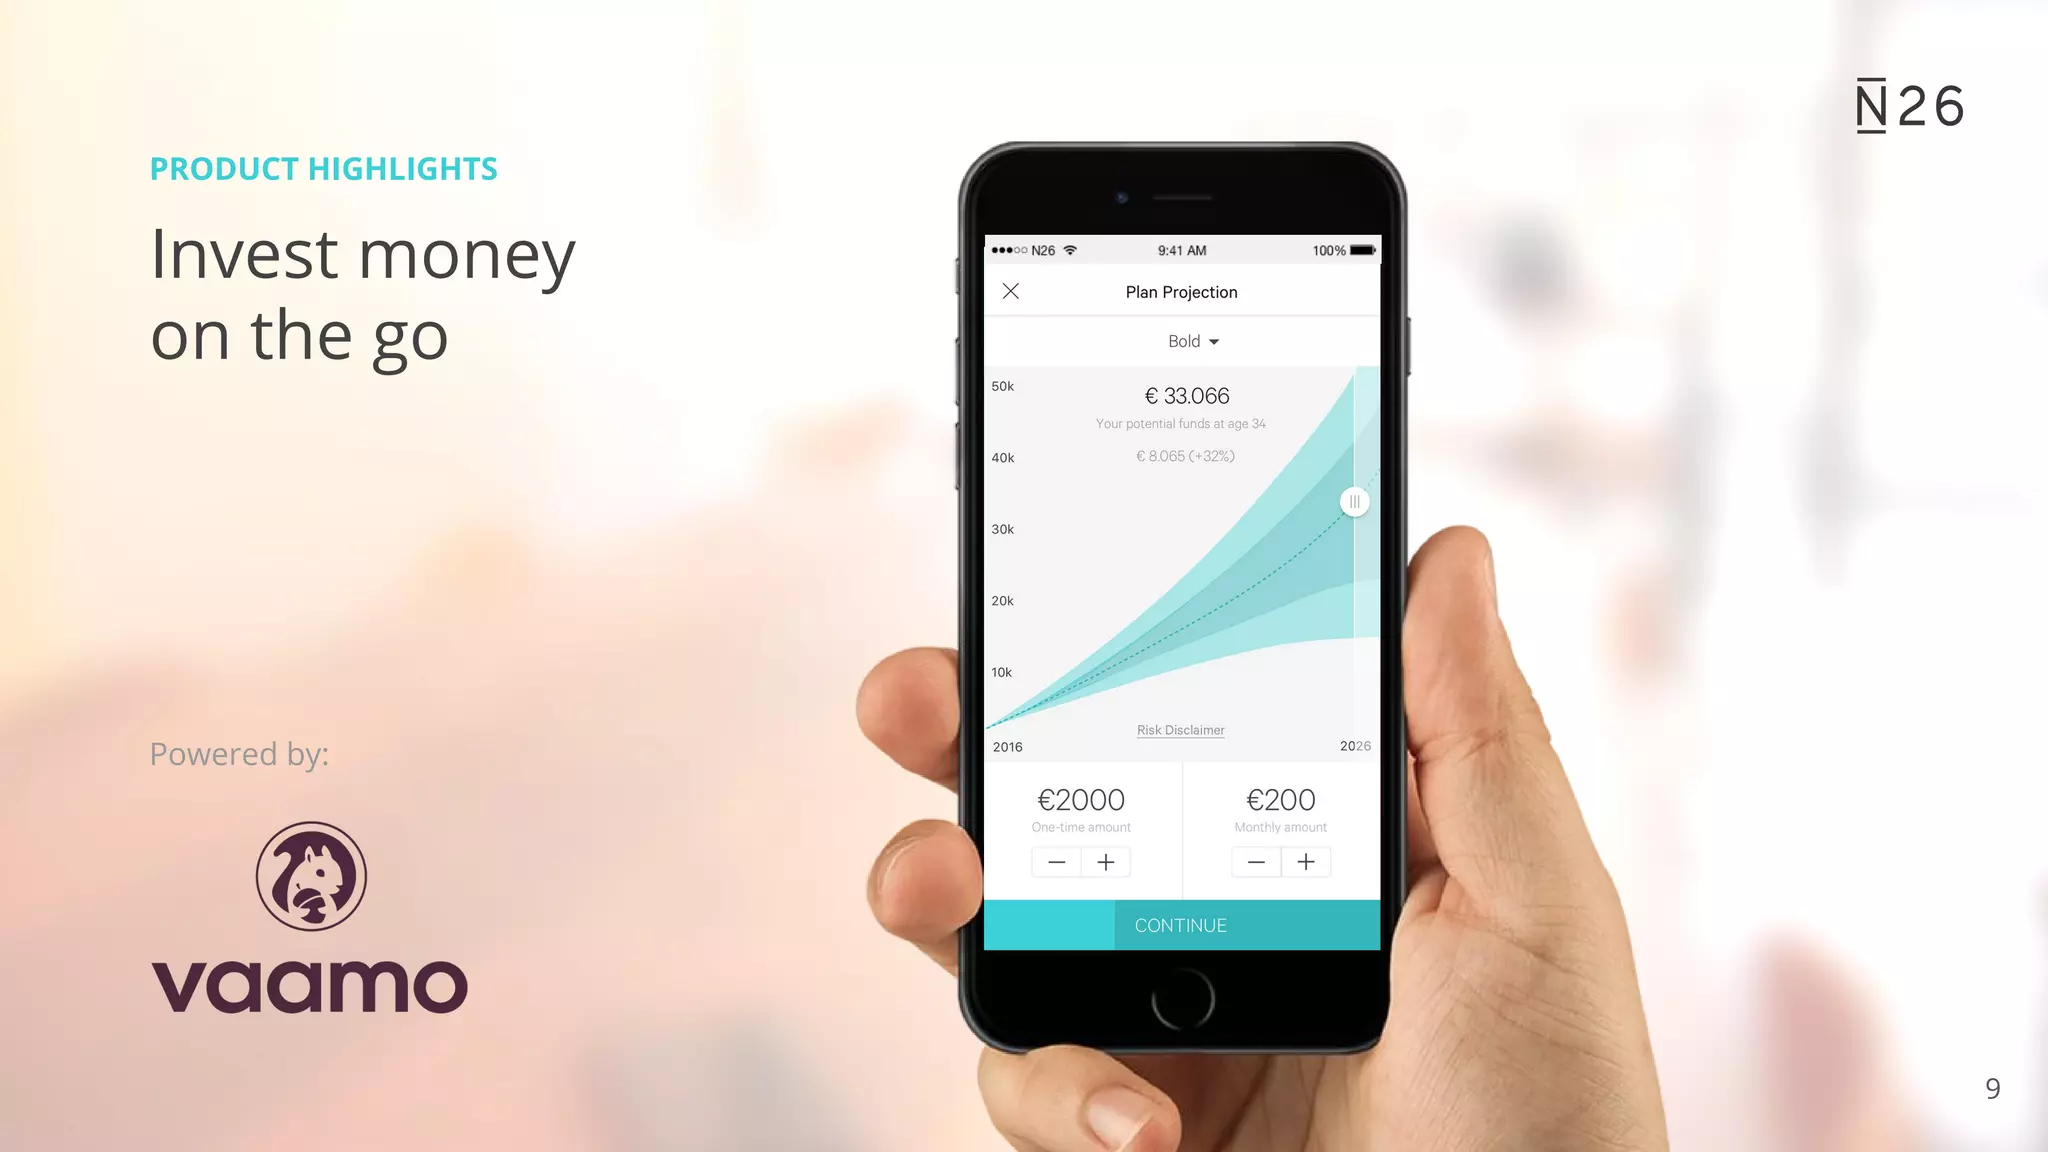
Slide 10 highlights an additional vertical: investment products via a partner (Vaamo) and a clean in-app projection UI. This signals that N26 is positioning as a platform that can aggregate financial services (banking, transfers, investments) rather than a single-product app. The slide illustrates monetization potential through new product lines while keeping the interface and user flow front-and-center, which helps investors picture cross-sell opportunities and lifetime value expansion.

For founders building platforms, showing credible partnerships and in-app UX for new revenue streams is crucial. It reduces risk by demonstrating a go-to-market for additional products and makes the case for higher ARPU; including partner names and sample screens provides tangible evidence rather than abstract claims.

Key Takeaway: Demonstrate platform potential with concrete partner integrations and UI examples that show how new revenue streams will be experienced by users.
Traction & Geographic Strategy

Traction & Geographic Strategy

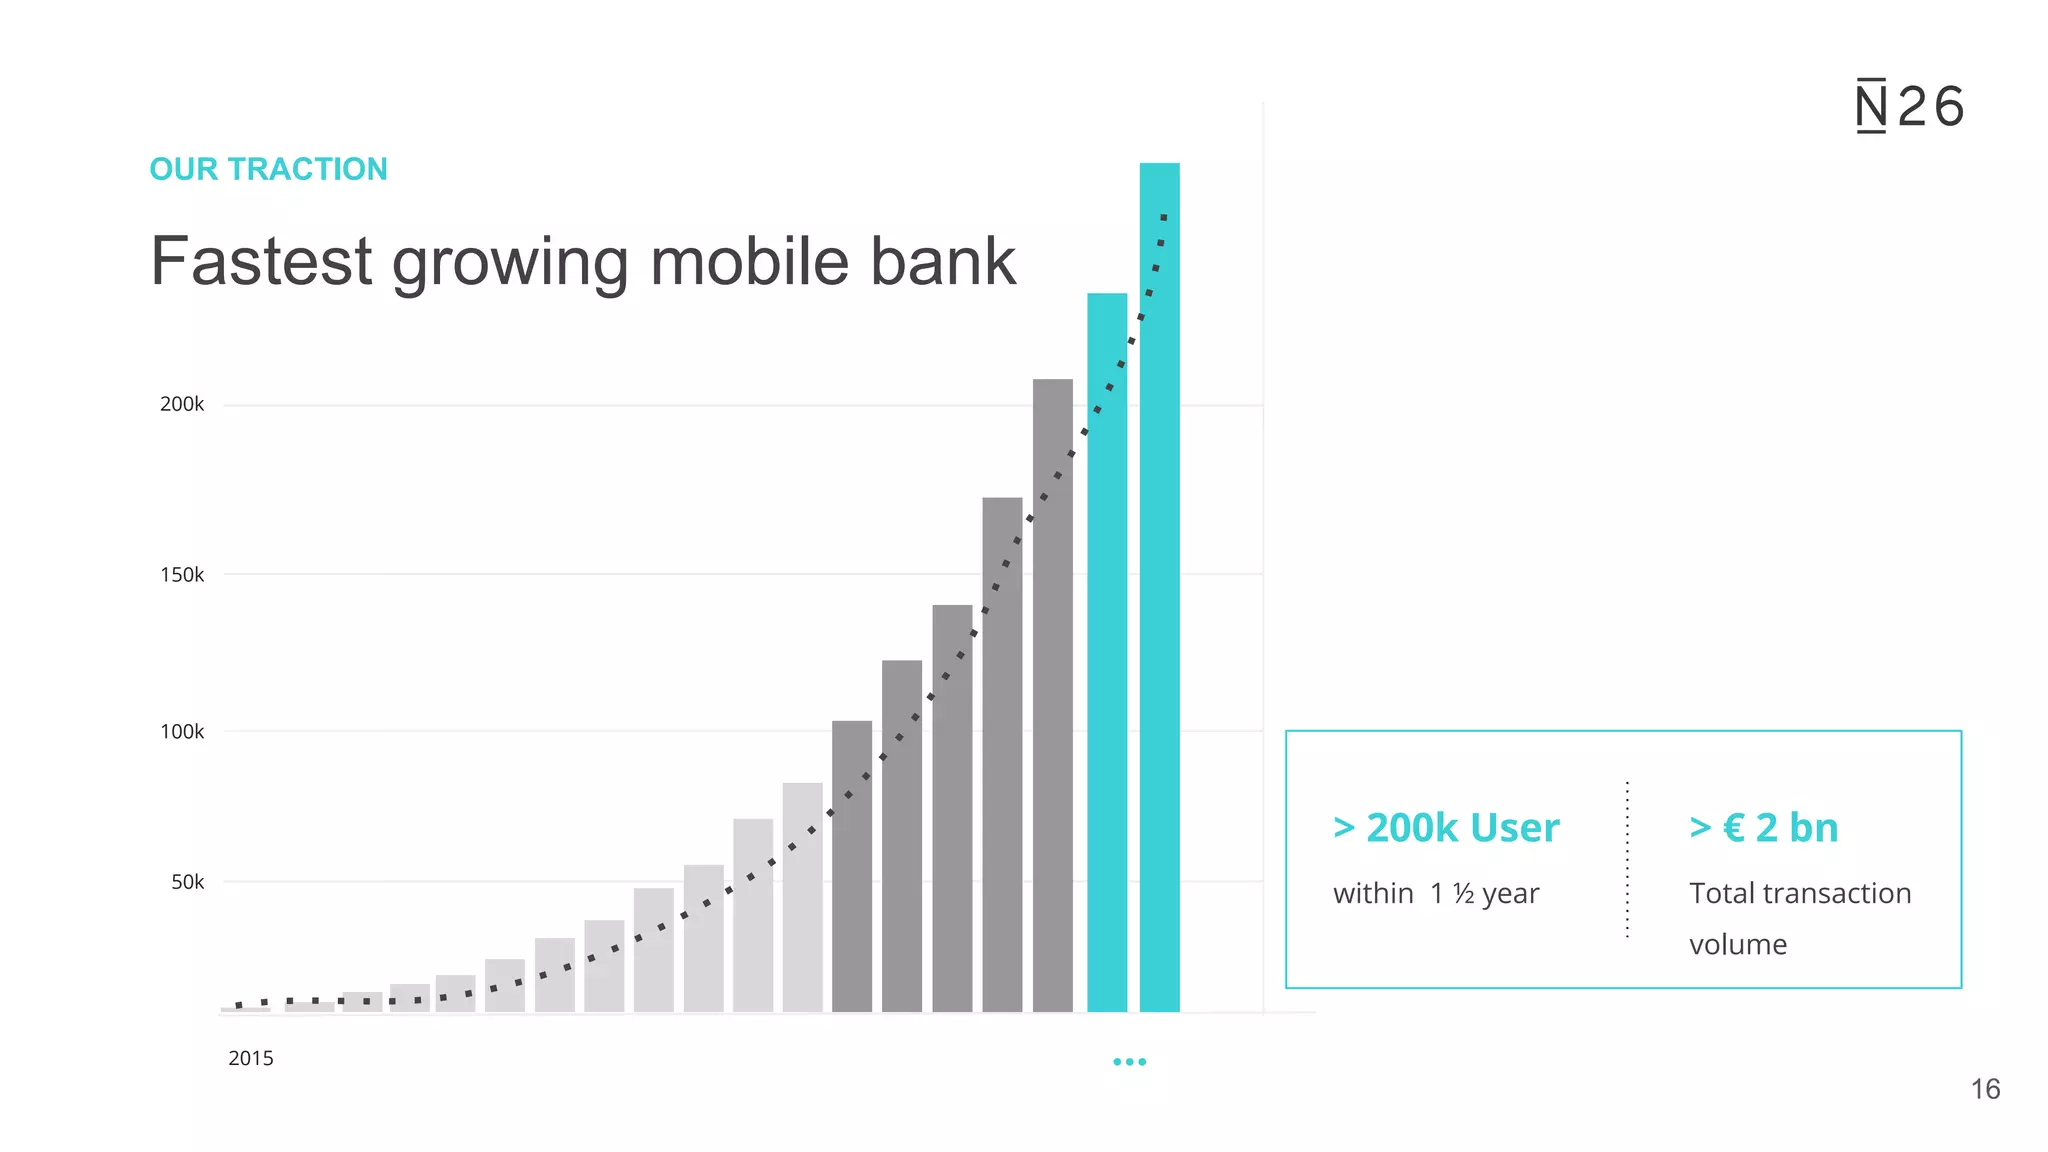
Slide 16 presents growth metrics with a bar chart showing rapid user growth and a callout: "> 200k User within 1 ½ year" and "> €2 bn Total transaction volume." The chart is simple, uses color to highlight recent acceleration, and pairs the visual with clear quantitative milestones. This gives investors substance: traction in user numbers and transaction volume which validates product-market fit and operational scale.

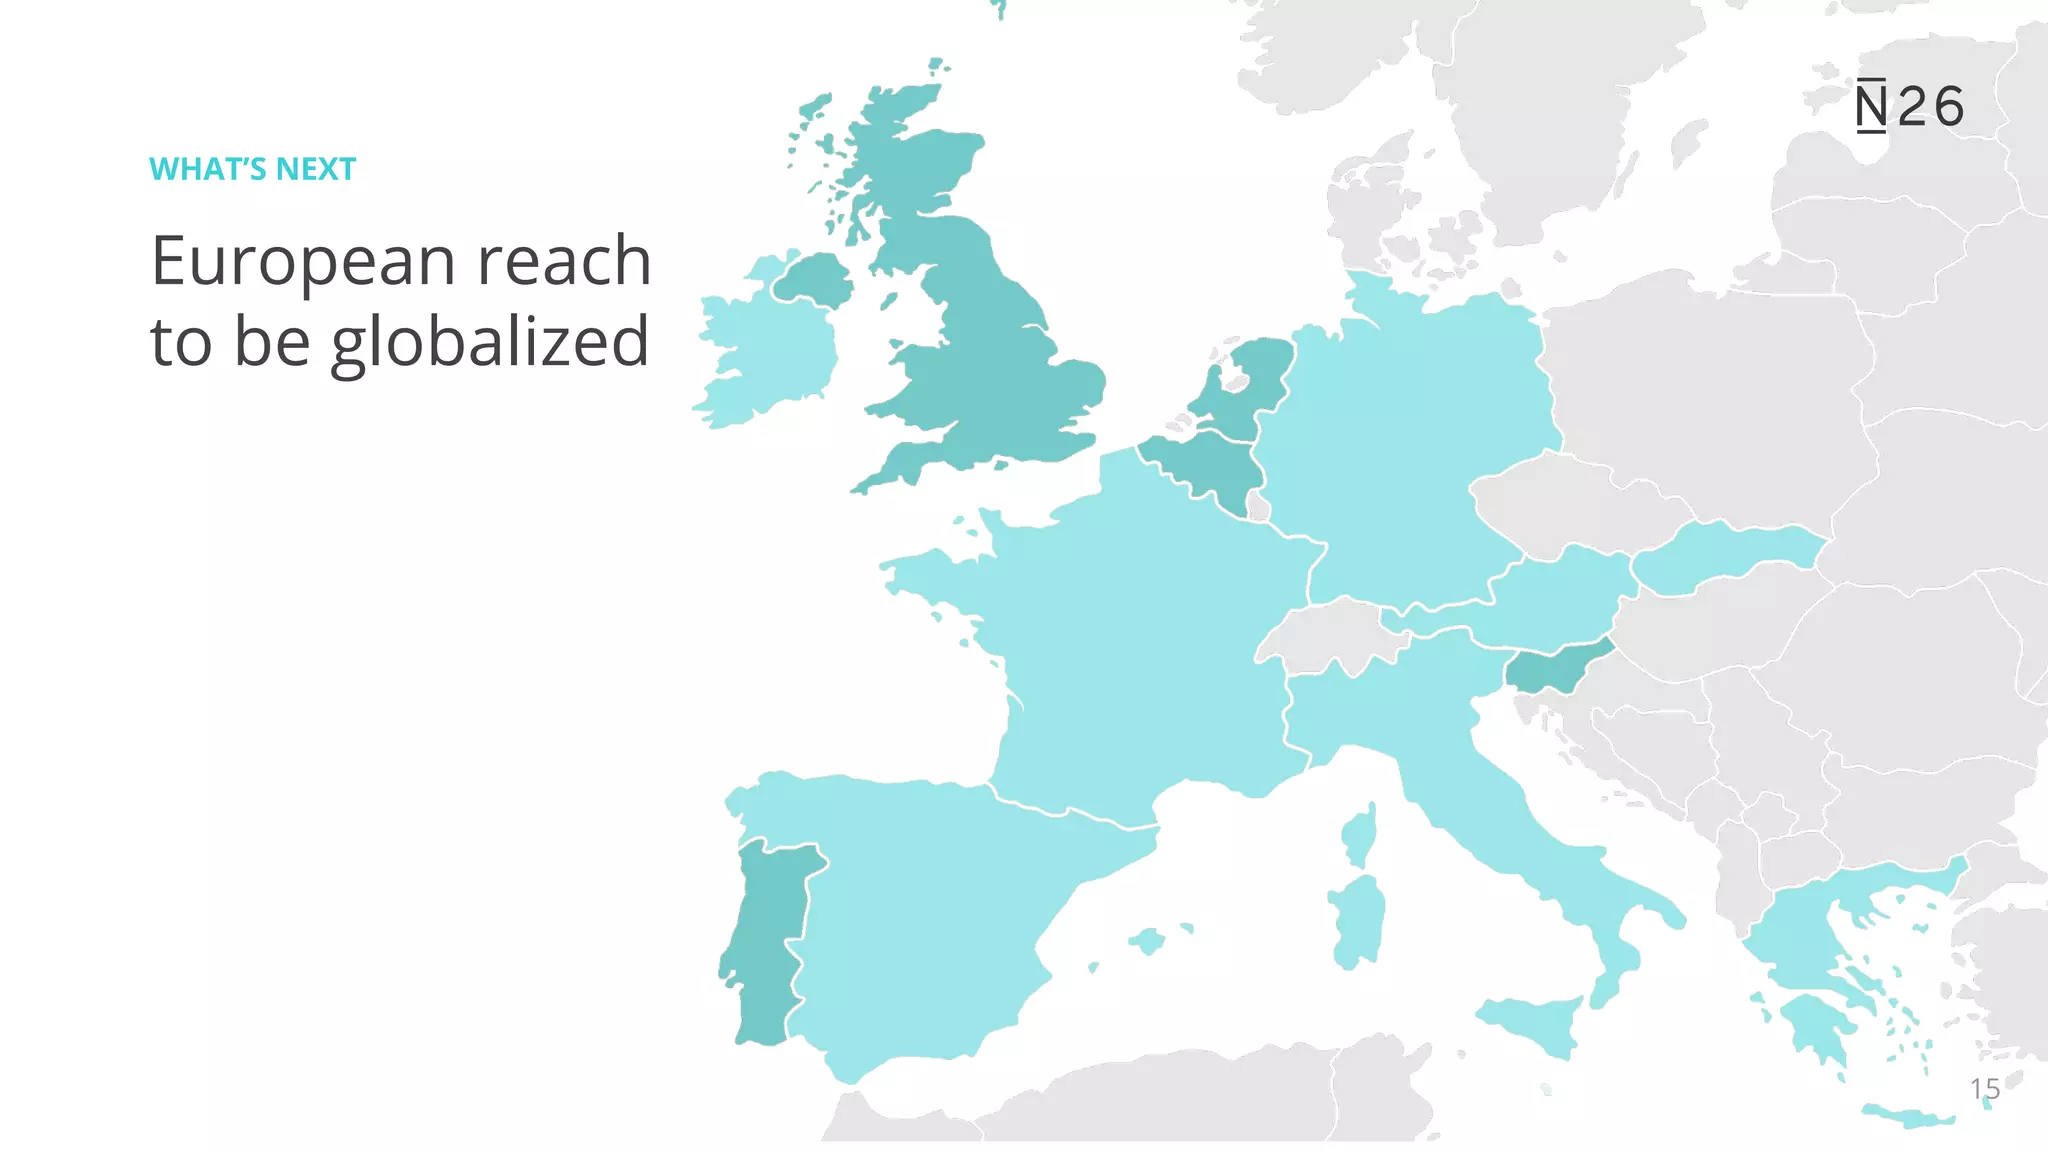
Slide 17 complements this with a European map marking target and operating countries, linking traction to an explicit expansion playbook. Together, these slides show not just growth but an intentional geographic runway. Founders should follow this example by pairing topline growth charts with maps or go-to-market plans that explain where next growth will come from and why those markets are attractive.

Key Takeaway: Pair clear traction charts with a geographic expansion map to show both momentum and a credible plan for scaling.
Team & Culture: Building for Scale

Team & Culture: Building for Scale

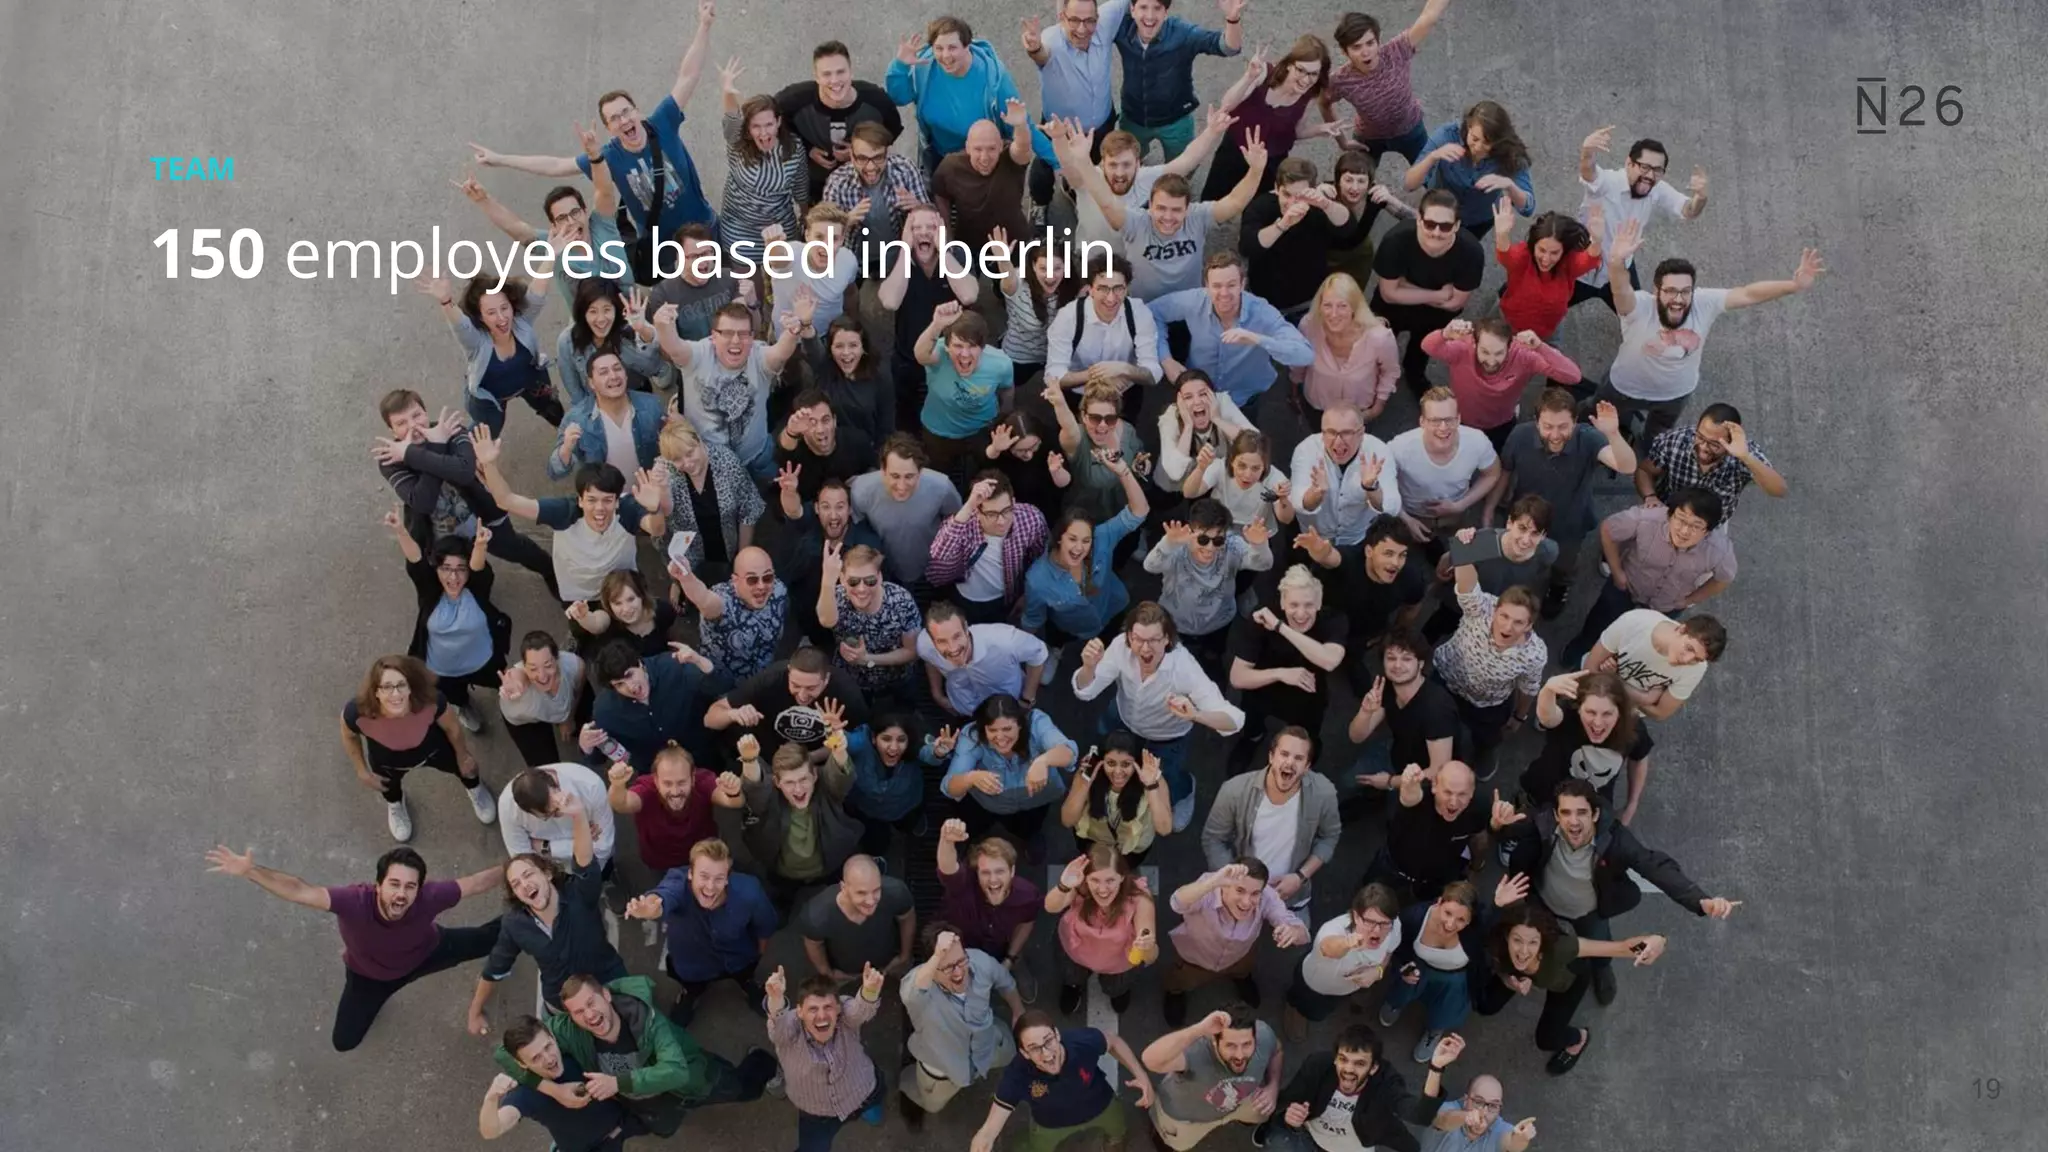
Slide 20 is a large team photo with a headline: "150 employees based in berlin." The visual communicates a sizable, engaged team and emphasizes company culture and operational capability. For investor audiences, a slide like this signals that the company has moved beyond founder-only execution and has built the human capital needed to scale product, operations, and compliance.

Founders should include team slides that convey both headcount and composition: whether you’re hiring for engineering, compliance, or growth matters for investor confidence. A team photo can humanize the company, but it should be supported in backups by org charts and key bios for critical roles to demonstrate depth and domain expertise.

Key Takeaway: Show team scale and culture visually, and support it with backup org details and key bios to prove operational readiness.

Conclusion: Key Lessons

This N26 deck combines strong visual design with tightly curated business proof points: problem framing, product differentiation, partnership-enabled features, actionable traction metrics, and a clear expansion roadmap. Its strengths lie in concise messaging, high-quality product imagery, and the linkage between user experience improvements and measurable business outcomes (activation speed, user growth, transaction volume). For founders, the deck is a useful model for how to present both emotional brand positioning and the hard metrics investors need.

Actionable advice: lead with a striking product-in-context visual and a one-line mission, follow quickly with a concise problem statement and a credible statistic, then show core product differentiators (including regulatory or operational credentials). Pair product UX examples with partner and monetization strategies, and close with clean traction charts plus a geographic expansion plan. Always include backup slides with sources, partner terms, org charts, and unit economics to satisfy diligence after the deck piques interest.

Full Deck Analysis

11 sections

Overview

Company: N26
Round: Various (Multiple)
Year: 2015-2016
Outcome: Valued at $9B
Presentation Date: November 2016 (NOAH London)
Presenter: Valentin Stalf (Founder & CEO)


Executive Summary

N26 presents itself as “the future of banking”—a mobile-first, fully licensed European bank that disrupts traditional banking by aggregating best-in-class fintech services into a single app. The deck demonstrates impressive early traction (200k+ users, €2bn transaction volume within 1.5 years) backed by tier-1 investors (Axel Springer, Horizons Ventures, EarlyBird, Valar) and validates market demand through press coverage from CNBC, Reuters, and TechCrunch. The strategic positioning moves beyond a simple banking app to a “rebundling” platform that consolidates specialized fintech services (TransferWise, vaamo, robinhood, LendingClub, etc.), positioning N26 as the aggregator in a disaggregated fintech ecosystem.


Problem Statement

Slide 3: “7 out of 10 millennials would rather visit their dentist than their local bank”

The deck opens with a powerful emotional hook citing the Millennial Disruption Index. The problem is framed as:

  • Traditional banking is broken: Outdated, slow, expensive, and untrustworthy
  • Millennials are underserved: Digital natives have no banking solution designed for their needs
  • Institutional distrust: Visual metaphor of classical bank building with “BANKS ARE EVIL” protest signs reinforces perception of banking as corrupt/irrelevant

Effectiveness: The statistic is memorable and emotionally resonant, but lacks context (no publication date, methodology, or geographic specificity). The problem is positioned as attitudinal (distrust) rather than functional (what specific banking tasks are broken?).


Solution

Slides 4-11: Product Overview & Feature Highlights

N26 positions itself as “the first global mobile bank” with three core value propositions:

1. Full Regulatory Legitimacy (Slide 5)

  • Full European banking license (not just an app)
  • First fully mobile bank account
  • One-touch access to all financial products
  • Physical MasterCard debit card included

2. Superior User Experience (Slides 6-11)

  • Account opening: 8 minutes, paperless (vs. traditional banks: days/weeks)
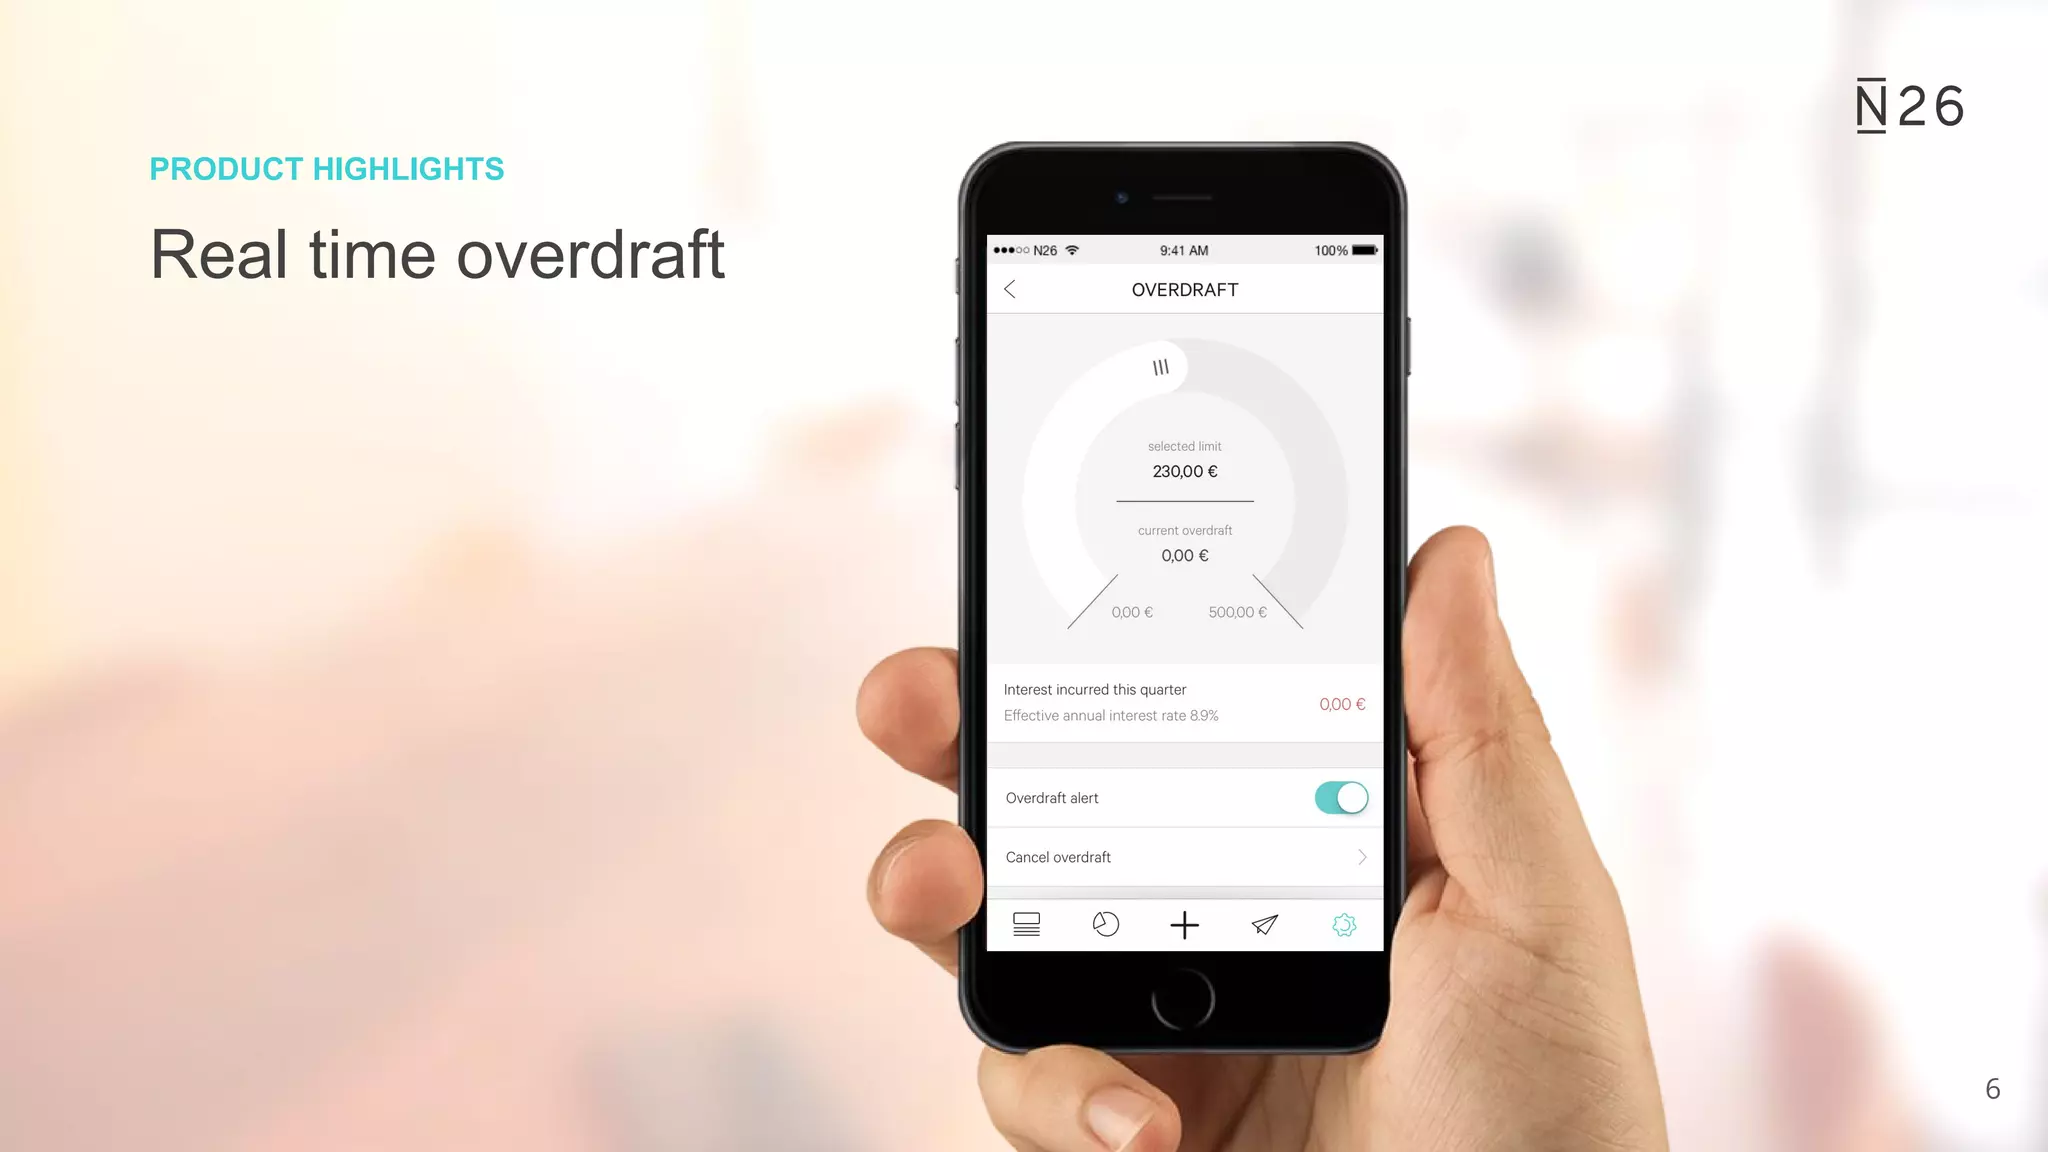
  • Real-time overdraft: Customizable limits (€0-€50,000) with 8.9% interest rate; instant approval
  • Cash access: Cash26 feature enables withdrawals at retail partners (Greensill Bank partnership)
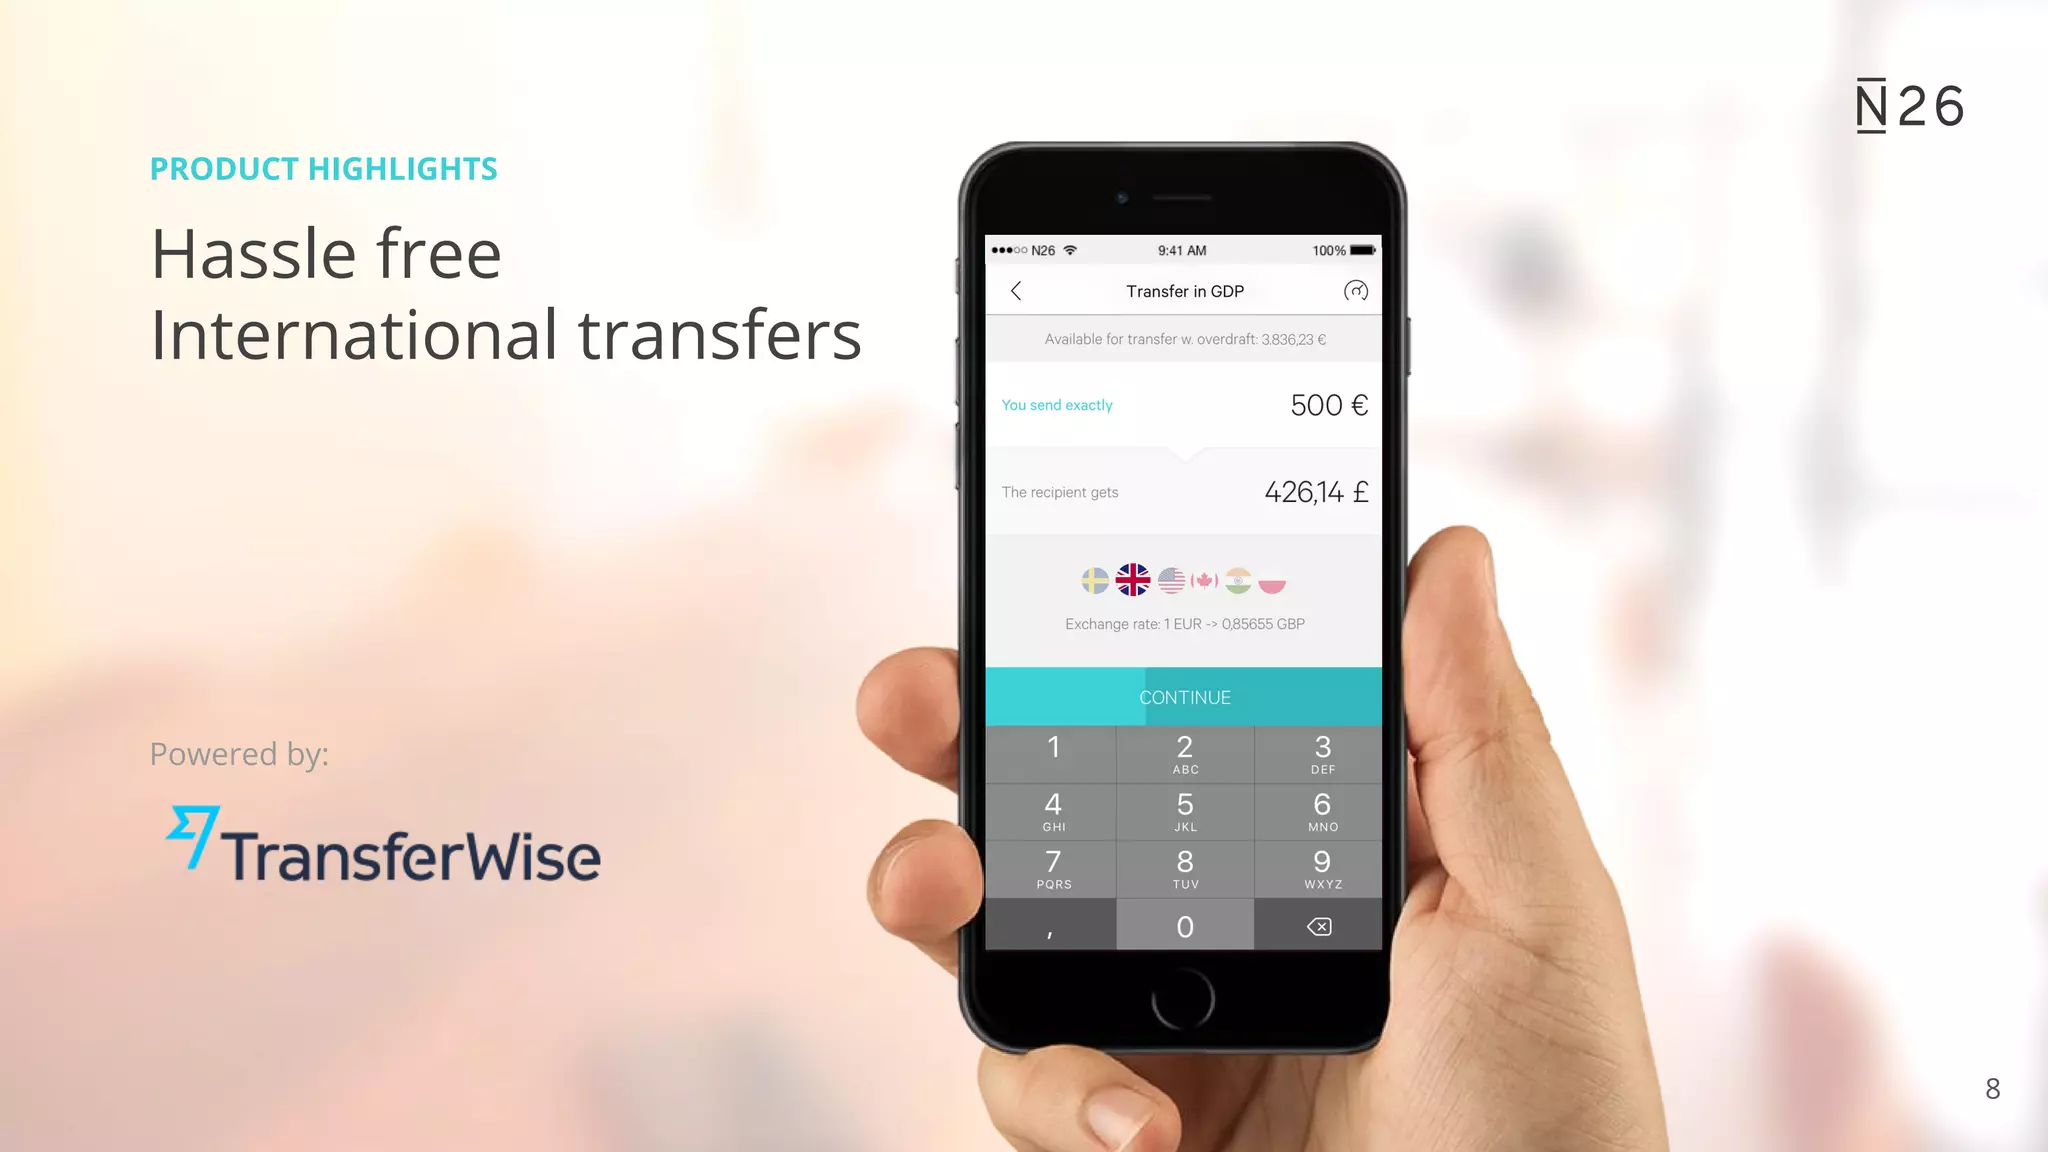
  • International transfers: Hassle-free via TransferWise integration; transparent exchange rates
  • Investment: On-the-go investing via vaamo integration with projections (€33,066 at age 35)
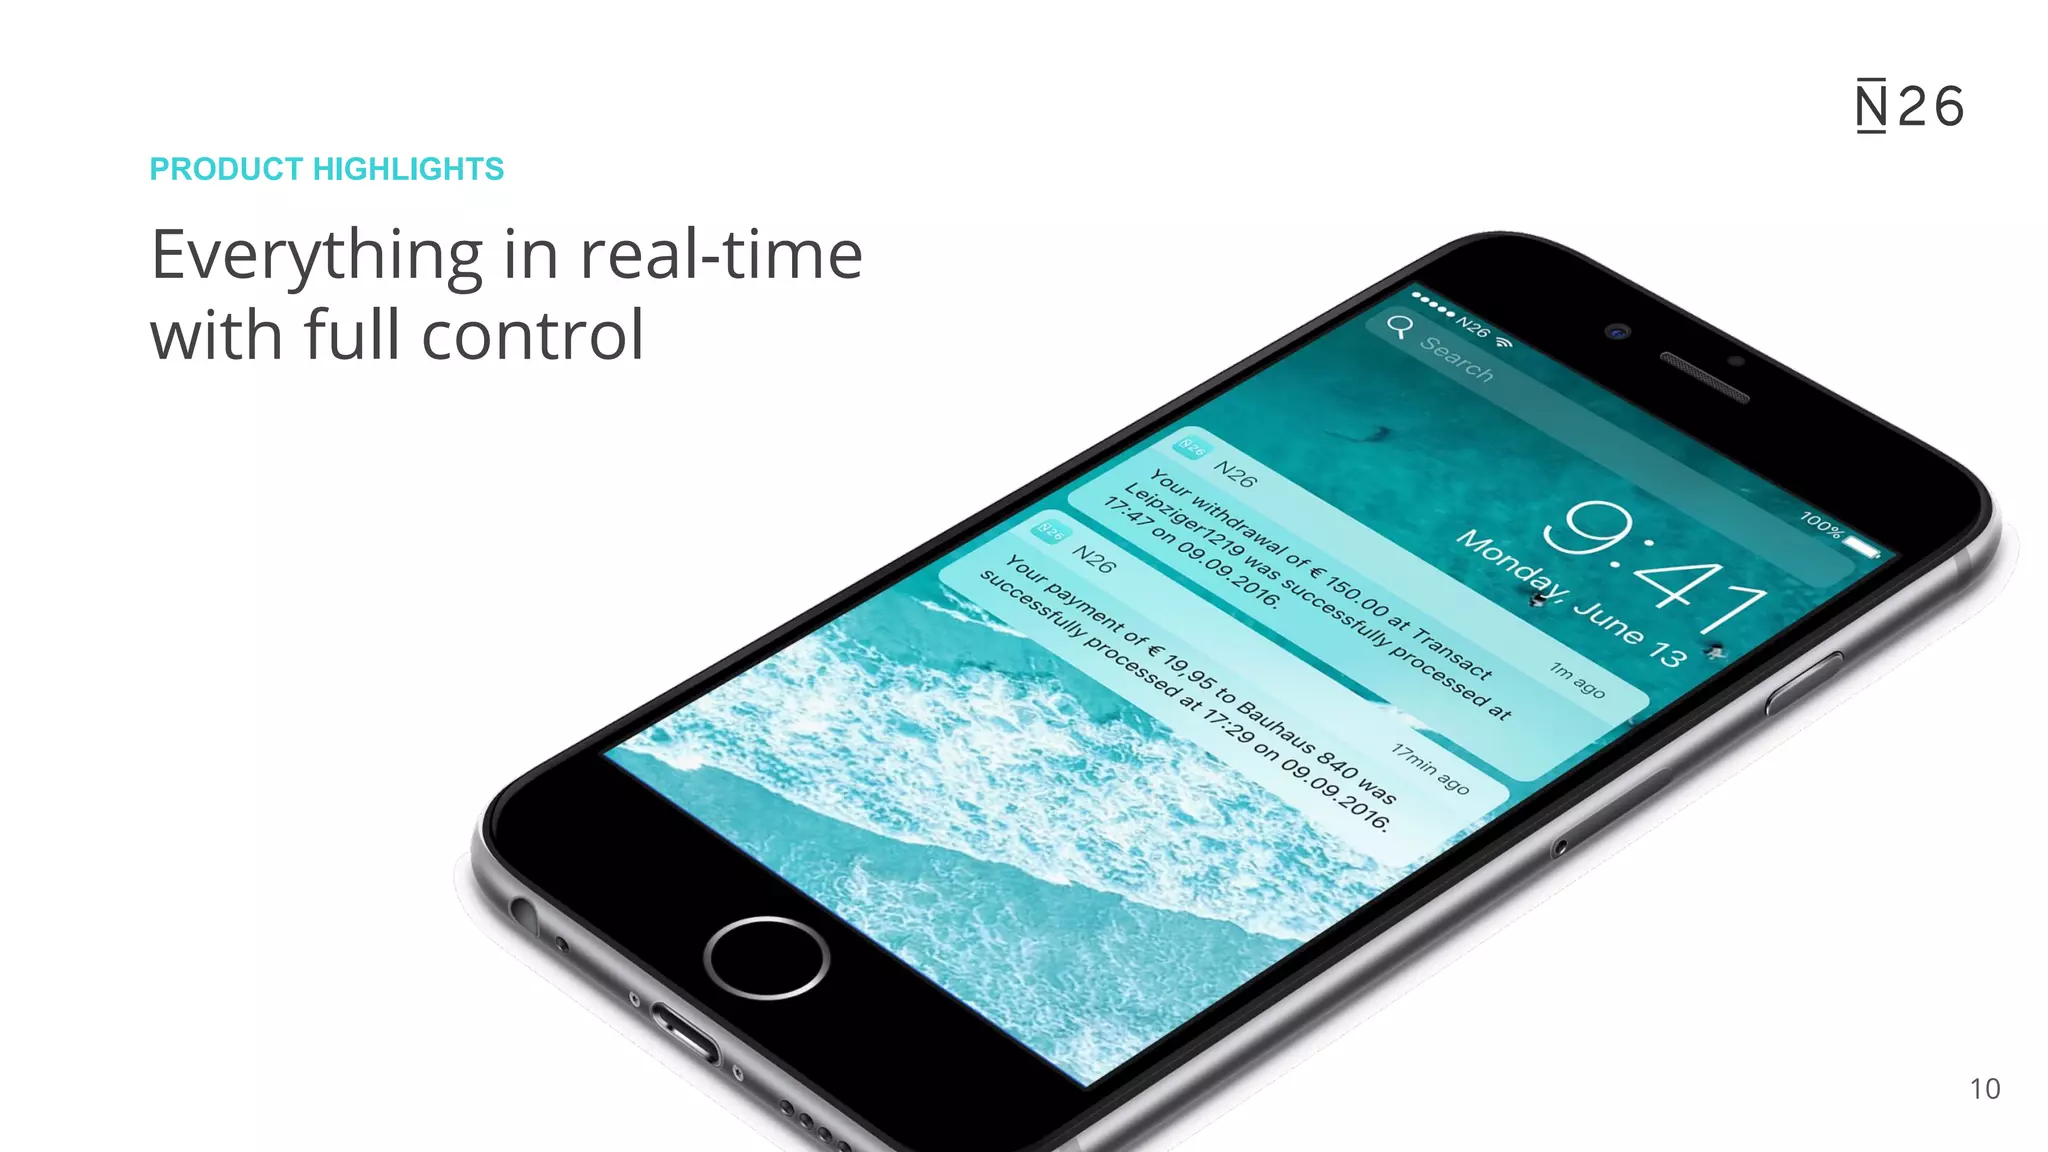
  • Real-time notifications: Instant transaction alerts for fraud detection and control

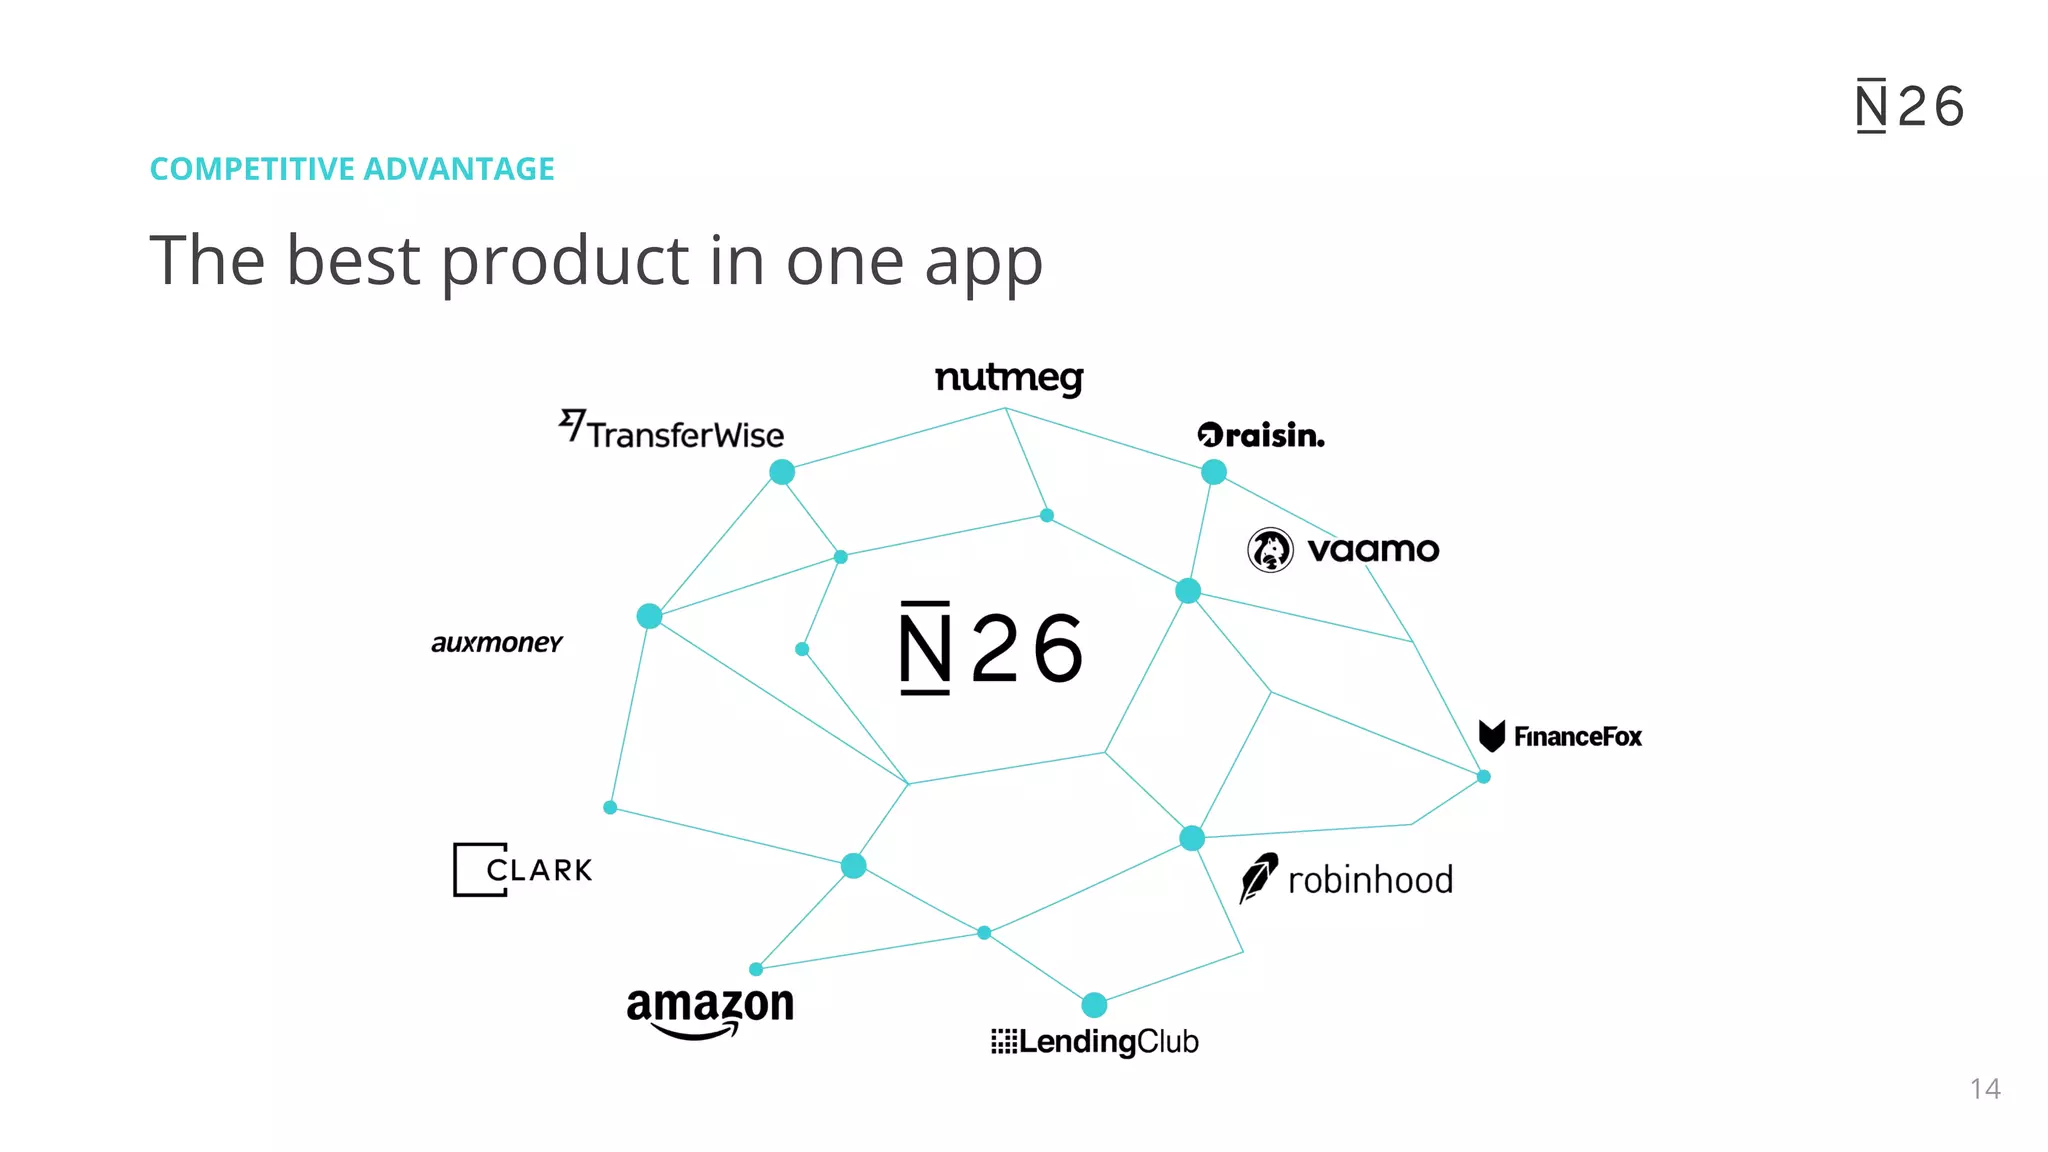
3. Ecosystem Integration (Slide 15)

Rather than building everything in-house, N26 aggregates best-in-class services:

  • Transfers: TransferWise
  • Investments: nutmeg, vaamo, robinhood
  • Savings: raisin.
  • Lending: LendingClub, auxmoney
  • Insurance: CLARK
  • Analytics: FinanceFox
  • E-commerce: Amazon

Positioning: “The best product in one app”—a super-app strategy that leverages partnerships rather than building proprietary technology.


Market Opportunity

Slide 16: European Expansion Strategy

The deck shows geographic ambition but provides limited TAM/SAM/SOM analysis:

Geographic Scope

  • Primary market: Europe (20+ countries highlighted in teal)
  • Target markets: EU, EFTA, UK (regulatory harmonization advantage)
  • Excluded: Turkey, North Africa, some Eastern European countries
  • Future: Headline suggests “European reach to be globalized” (implies multi-continent expansion planned)

Market Size Context (Implicit)

  • Europe has ~450M people
  • Target demographic: Millennials (digital natives, underserved by traditional banking)
  • No explicit TAM/SAM/SOM figures provided
  • No market sizing by country or segment

Weakness: The deck lacks quantitative market opportunity analysis. No mention of:

  • Total addressable market (TAM) in euros or users
  • Serviceable addressable market (SAM) by country
  • Competitive market share assumptions
  • Revenue potential per user

Business Model

Not explicitly shown in the deck. Based on product features, inferred revenue streams:

Likely Revenue Sources

  1. Interchange fees — Debit card transactions (primary revenue for banks)
  2. Overdraft interest — 8.9% rate on overdraft balances
  3. Cash26 fees — 1.5% fee for deposits exceeding €100/month
  4. Partnership revenue — Affiliate fees or revenue share from:
    • TransferWise (international transfers)
    • vaamo/nutmeg (investments)
    • LendingClub/auxmoney (lending)
    • CLARK (insurance)
  5. Premium features — Implied but not detailed (likely subscription tiers)

Unit Economics

  • Not provided — No mention of:
    • Customer acquisition cost (CAC)
    • Lifetime value (LTV)
    • Churn rate
    • Revenue per user
    • Path to profitability

Critical Gap: The deck shows impressive user growth but provides no financial metrics. This is a significant omission for a fundraising pitch, suggesting either:

  • Data was withheld for confidentiality
  • Unit economics were unfavorable at the time
  • Focus was on growth over profitability (common for 2016 fintech)

Traction & Metrics

Slide 17: Growth Trajectory

User Growth

  • Milestone: 200,000+ users
  • Timeline: Within 1.5 years (from ~mid-2015 to late 2016)
  • Growth pattern: Exponential (shown by dotted trend line)
  • Recent acceleration: Teal bars show steeper growth in final periods

Transaction Volume

  • Total transaction volume: €2 billion+
  • Timeframe: Unclear if monthly, annual, or cumulative (likely cumulative through late 2016)
  • Validation: Demonstrates active usage, not just signups

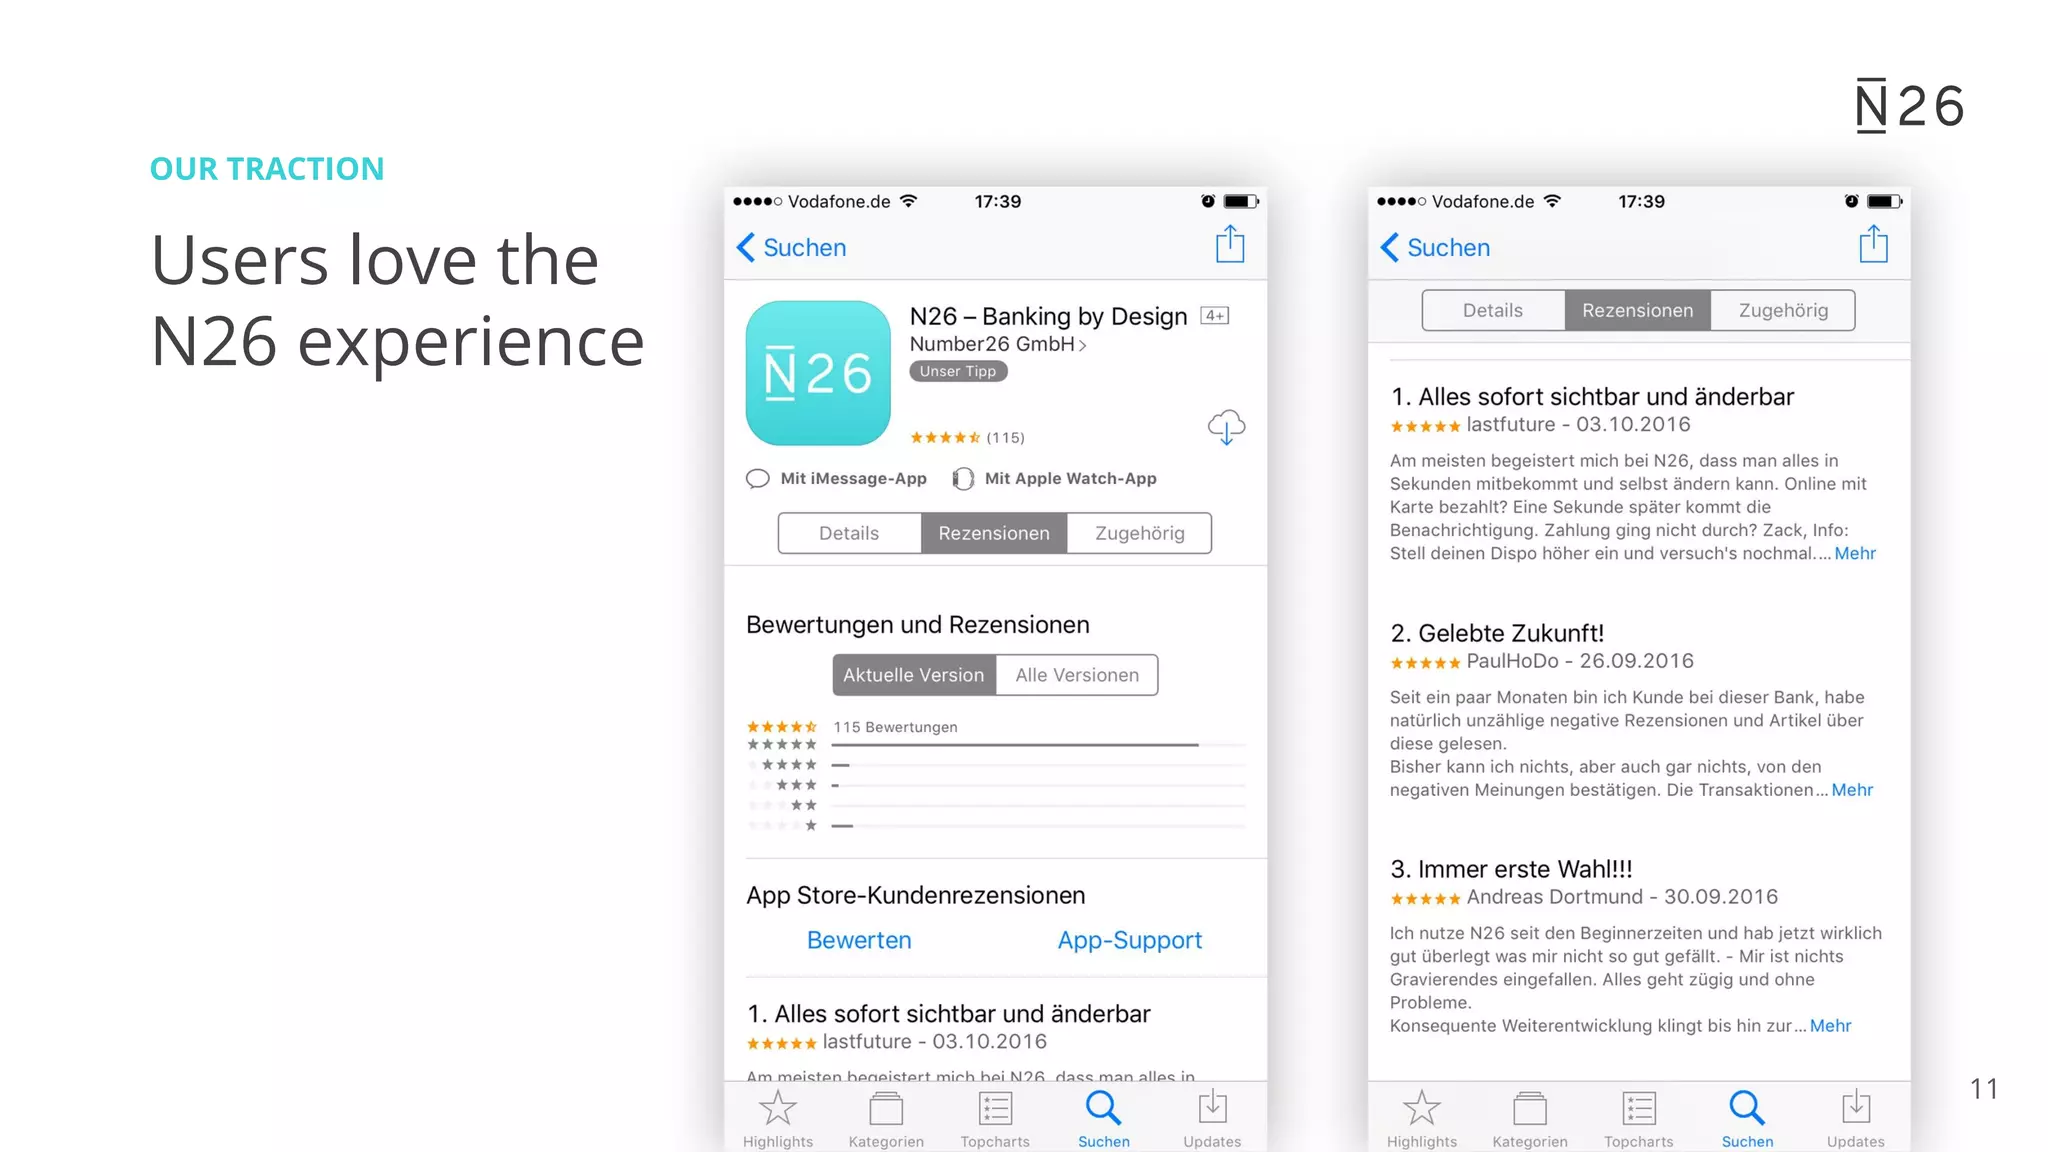
App Store Validation (Slide 12)

  • App Store rating: 4 out of 5 stars (★★★★☆)
  • Total reviews: 115 reviews
  • Sentiment: Overwhelmingly positive (all featured reviews are 5-star)
  • Key praise:
    • “Everything immediately visible and changeable” (real-time control)
    • “Lived future!” (innovation positioning)
    • “Always first choice!!!” (reliability)
    • Explicitly counters negative press: “I can’t confirm any of the negative opinions”

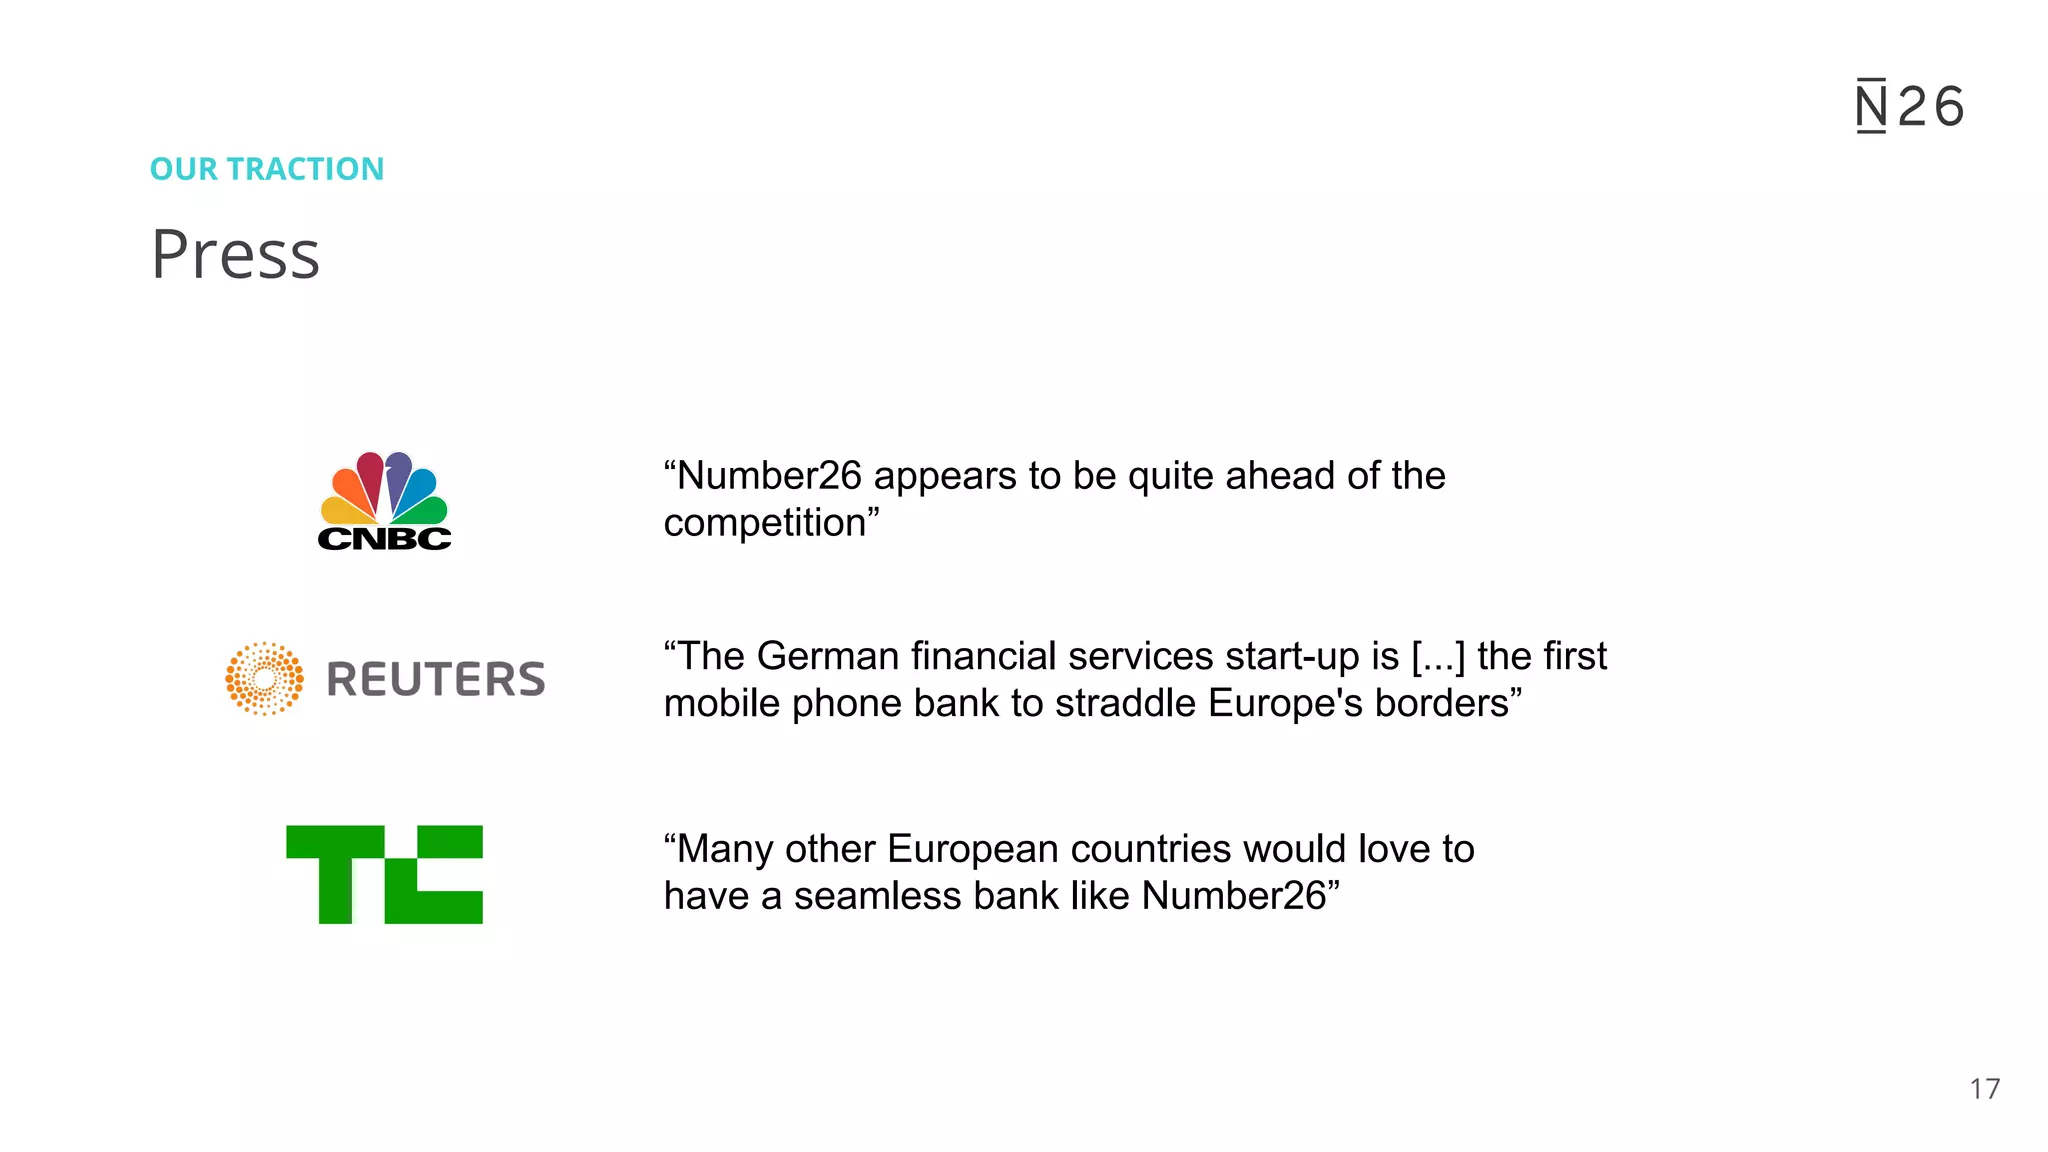
Press Coverage (Slide 18)

  • CNBC: “Number26 appears to be quite ahead of the competition”
  • Reuters: “The first mobile phone bank to straddle Europe’s borders”
  • TechCrunch: “Many other European countries would love to have a seamless bank like Number26”

Strengths:

  • Impressive user growth trajectory
  • Significant transaction volume validates engagement
  • Positive app store reviews and media coverage
  • Growth appears accelerating (not plateauing)

Weaknesses:

  • No competitor comparison (is 200k users fast relative to Revolut, Wise, etc.?)
  • No retention/churn data (could be high user acquisition with low retention)
  • App store reviews (115) is modest for a major app
  • Press quotes lack dates and full context
  • No financial metrics (revenue, profitability, unit economics)

Competitive Positioning

Slides 13-15: Platform Strategy & Differentiation

Strategic Positioning: “Unbundling → Rebundling”

Slide 13-14: The deck articulates a two-phase strategy:

  1. Unbundling phase: Traditional banks bundle all services (checking, savings, lending, investing, insurance)
  2. Rebundling phase: N26 disaggregates and re-aggregates best-in-class services

Competitive Advantages Claimed

  1. Regulatory legitimacy (Slide 5)
    • Full European banking license (vs. fintech apps without banking license)
    • Enables cross-border operations across EU
  2. Speed & convenience (Slides 6-7)
    • 8-minute account opening (vs. traditional banks: days/weeks)
    • Real-time overdraft approval (vs. traditional banks: manual underwriting)
  3. Ecosystem integration (Slide 15)
    • 10 integrated partners (TransferWise, vaamo, robinhood, LendingClub, etc.)
    • “Best product in one app” positioning
    • Aggregator advantage: users don’t need 10 separate apps
  4. User experience (Slide 11)
    • Real-time notifications and control
    • Mobile-first design (vs. traditional banks’ legacy systems)
  5. Cost structure (Implicit)
    • No physical branches (vs. traditional banks’ high overhead)
    • Digital-first operations (lower CAC than traditional banks)

Competitive Weaknesses Not Addressed

  • Partner dependency: Features powered by TransferWise, vaamo, robinhood—not proprietary technology
  • Competitive threats: Doesn’t mention Revolut, Wise, or other mobile banks
  • Regulatory risk: Doesn’t address potential regulatory changes or compliance costs
  • Scaling complexity: Expanding to 20+ countries with different regulations is operationally complex

Team

Slide 20: Organization & Leadership

Team Size

  • 150 employees based in Berlin
  • Organizational stage: Mature startup (substantial headcount for 2016)
  • Culture: Energetic, diverse, inclusive (visual indicators from team photo)

Leadership (Slide 22: NOAH Advisors Team)

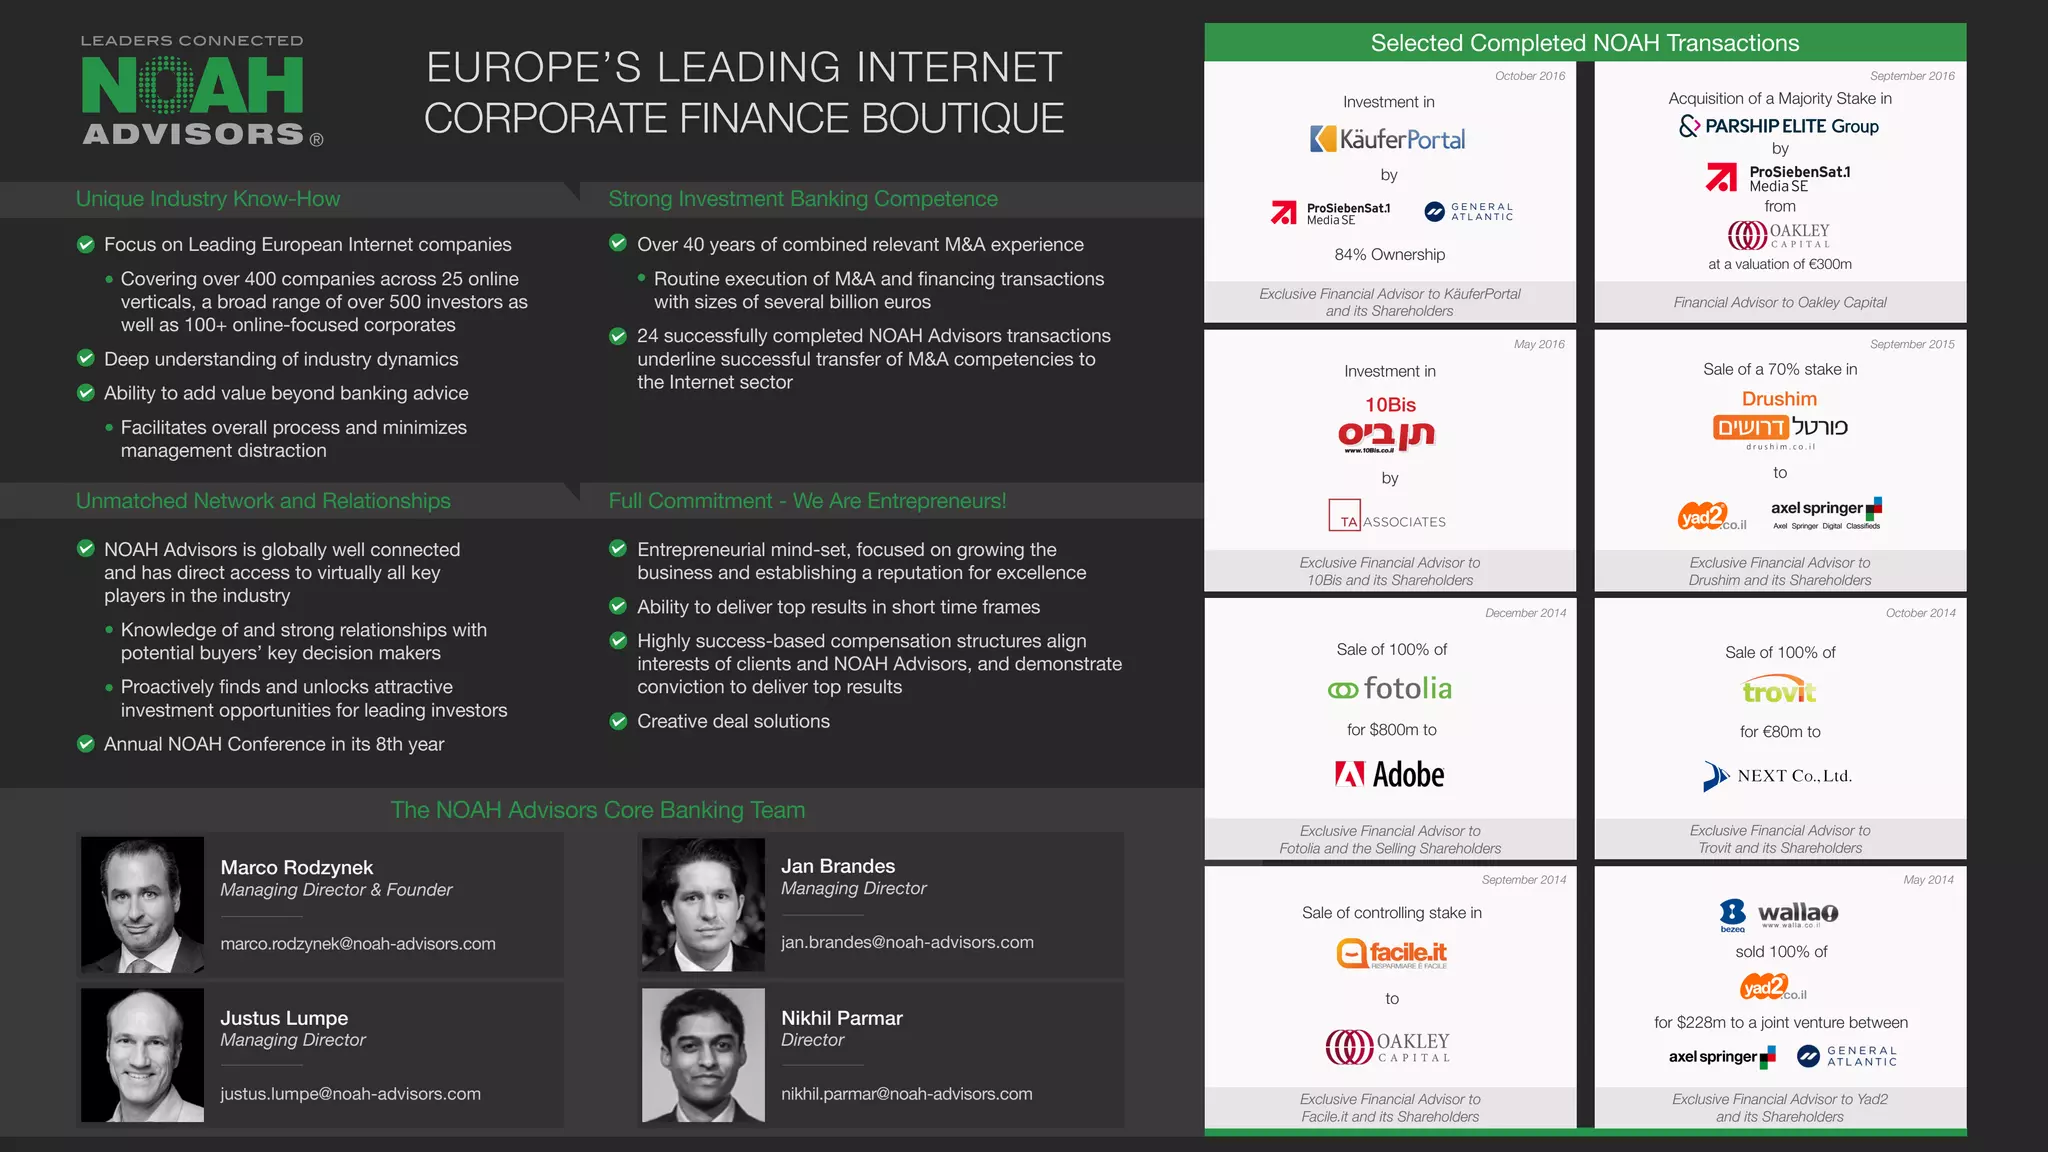
While the deck doesn’t detail N26’s full leadership team, it shows the financial advisor team:

  • Marco Rodzynek — Managing Director & Founder (NOAH Advisors)
  • Jan Brandes — Managing Director (NOAH Advisors)
  • Justus Lumpe — Managing Director (NOAH Advisors)
  • Nikhil Parmar — Director (NOAH Advisors)

Founder

  • Valentin Stalf — Founder & CEO (presenting the deck)

Team Credentials

  • Not detailed in deck — No mention of:
    • Engineering expertise or background
    • Banking/fintech experience
    • Previous exits or relevant experience
    • Board composition
    • Advisory board

Weakness: The deck shows team size but provides minimal information about leadership credentials, relevant experience, or organizational structure. This is a significant gap for a fintech company requiring deep banking/regulatory expertise.


Go-to-Market Strategy

Slide 16: Geographic Expansion

The deck shows geographic ambition but limited GTM detail:

Market Entry Strategy (Implied)

  1. Primary market: Germany (headquarters in Berlin)
  2. European expansion: 20+ countries via EU banking license
  3. Sequencing: Not specified (which countries first?)
  4. Localization: Not addressed (language, payment systems, regulatory differences)

User Acquisition (Implied)

  • Organic/viral: App store presence (115 reviews suggests organic discovery)
  • Press coverage: CNBC, Reuters, TechCrunch coverage drives awareness
  • Word-of-mouth: Positive app reviews suggest strong NPS
  • No paid acquisition mentioned: No discussion of marketing spend or CAC

Distribution Channels

  • Direct: Mobile app (iOS shown; Android implied)
  • Partnerships: Cash26 retail network (Greensill Bank partnership)
  • Ecosystem: Integration with partner apps (TransferWise, vaamo, etc.)

Weakness: The deck lacks detail on:

  • Marketing strategy or budget
  • Customer acquisition cost (CAC)
  • Retention/engagement tactics
  • Competitive positioning in each market
  • Regulatory approval timeline for new markets

The Ask

Not explicitly stated in the deck.

Based on context clues:

  • Funding raised to date: $50M+ (Slide 19)
  • Investors: Axel Springer, Horizons Ventures, Battery Ventures, redalpine, EarlyBird, Valar
  • Implied ask: Series B or later round (given investor caliber and company maturity)
  • Use of funds: Not specified, but likely:
    • European expansion (20+ countries)
    • Product development (new features, partnerships)
    • Team scaling (150 employees → larger org)
    • Marketing/user acquisition

Critical Gap: The deck does not state:

  • Specific funding amount being raised
  • Use of proceeds breakdown
  • Runway/burn rate
  • Path to profitability
  • Exit strategy or timeline

This is unusual for a formal fundraising pitch and suggests either:

  • This is a general investor update (not a specific fundraising pitch)
  • Specific financial details were discussed separately
  • The deck was designed for broad audience (media, partners) rather than specific investors

Investor Deep Dive

Executive summary, strengths & red flags

Executive Summary

N26 presents itself as "the future of banking"—a mobile-first, fully licensed European bank that disrupts traditional banking by aggregating best-in-class fintech services into a single app. The deck demonstrates impressive early traction (200k+ users, €2bn transaction volume within 1.5 years) backed by tier-1 investors (Axel Springer, Horizons Ventures, EarlyBird, Valar) and validates market demand through press coverage from CNBC, Reuters, and TechCrunch. The strategic positioning moves beyond a simple banking app to a "rebundling" platform that consolidates specialized fintech services (TransferWise, vaamo, robinhood, LendingClub, etc.), positioning N26 as the aggregator in a disaggregated fintech ecosystem.

Key Strengths

7 identified

1

Product-First Storytelling

- Every product highlight is shown with actual app UI screenshots (Slides 5-11)

2

Regulatory Legitimacy as Differentiator

- Emphasizes "Full European banking license" prominently (Slide 5)

3

Impressive Growth Trajectory

- 200k users in 1.5 years with €2bn transaction volume (Slide 17)

4

Ecosystem/Partnership Strategy

- 10 integrated partners (TransferWise, vaamo, robinhood, LendingClub, etc.) shown as network diagram (Slide 15)

5

Tier-1 Investor Backing

- $50M+ from Axel Springer, Horizons Ventures, EarlyBird, Valar (Slide 19)

6

Third-Party Validation

- Press coverage from CNBC, Reuters, TechCrunch (Slide 18) + 115 app store reviews (Slide 12)

7

Visual Design & Presentation Quality

- Consistent design language, high-quality photography, clear typography

Red Flags & Weaknesses

10 identified

1

No Financial Metrics or Unit Economics

- Growth metrics (users, transaction volume) without profitability, CAC, LTV, or churn data

2

Partner Dependency Without Competitive Moat

- 10 integrated partners (TransferWise, vaamo, robinhood, LendingClub) are not exclusive to N26

3

Vague Market Opportunity Analysis

- No TAM/SAM/SOM analysis; European expansion map (Slide 16) shows 20+ countries but no prioritization or sizing

4

Regulatory Risk Not Addressed

- Deck emphasizes "Full European banking license" but doesn't address regulatory risks

5

No Competitive Analysis

- Deck doesn't mention competitors (Revolut, Wise, Bunq, etc.)

6

Team Credentials Underspecified

- Slide 20 shows 150 employees but provides no detail on leadership, expertise, or relevant experience

7

Date Discrepancies & Data Staleness

- Disclaimer dated "30 January 2016" but presentation is November 2016 (10-month gap)

8

Slide 22 Is Confusing & Off-Brand

- Final slide is about NOAH Advisors (financial advisor), not N26

9

"Fastest Growing Mobile Bank" Claim Unsubstantiated

- Slide 17 headline claims "Fastest growing mobile bank" but provides no competitor comparison

10

Partnership Ecosystem Lacks Integration Details

- Slide 15 shows 10 partners but doesn't explain integration depth or user experience

More Pitch Decks To Study

Compare structure, fundraising context, and investor-facing story across similar startup decks.