Anti-Dilution Provisions: What Every Founder Must Understand Before a Down Round
Most founders never think about anti-dilution provisions until they're staring at a down round. By then, it's too late to negotiate. Anti-dilution...
Most founders never think about anti-dilution provisions until they're staring at a down round. By then, it's too late to negotiate.
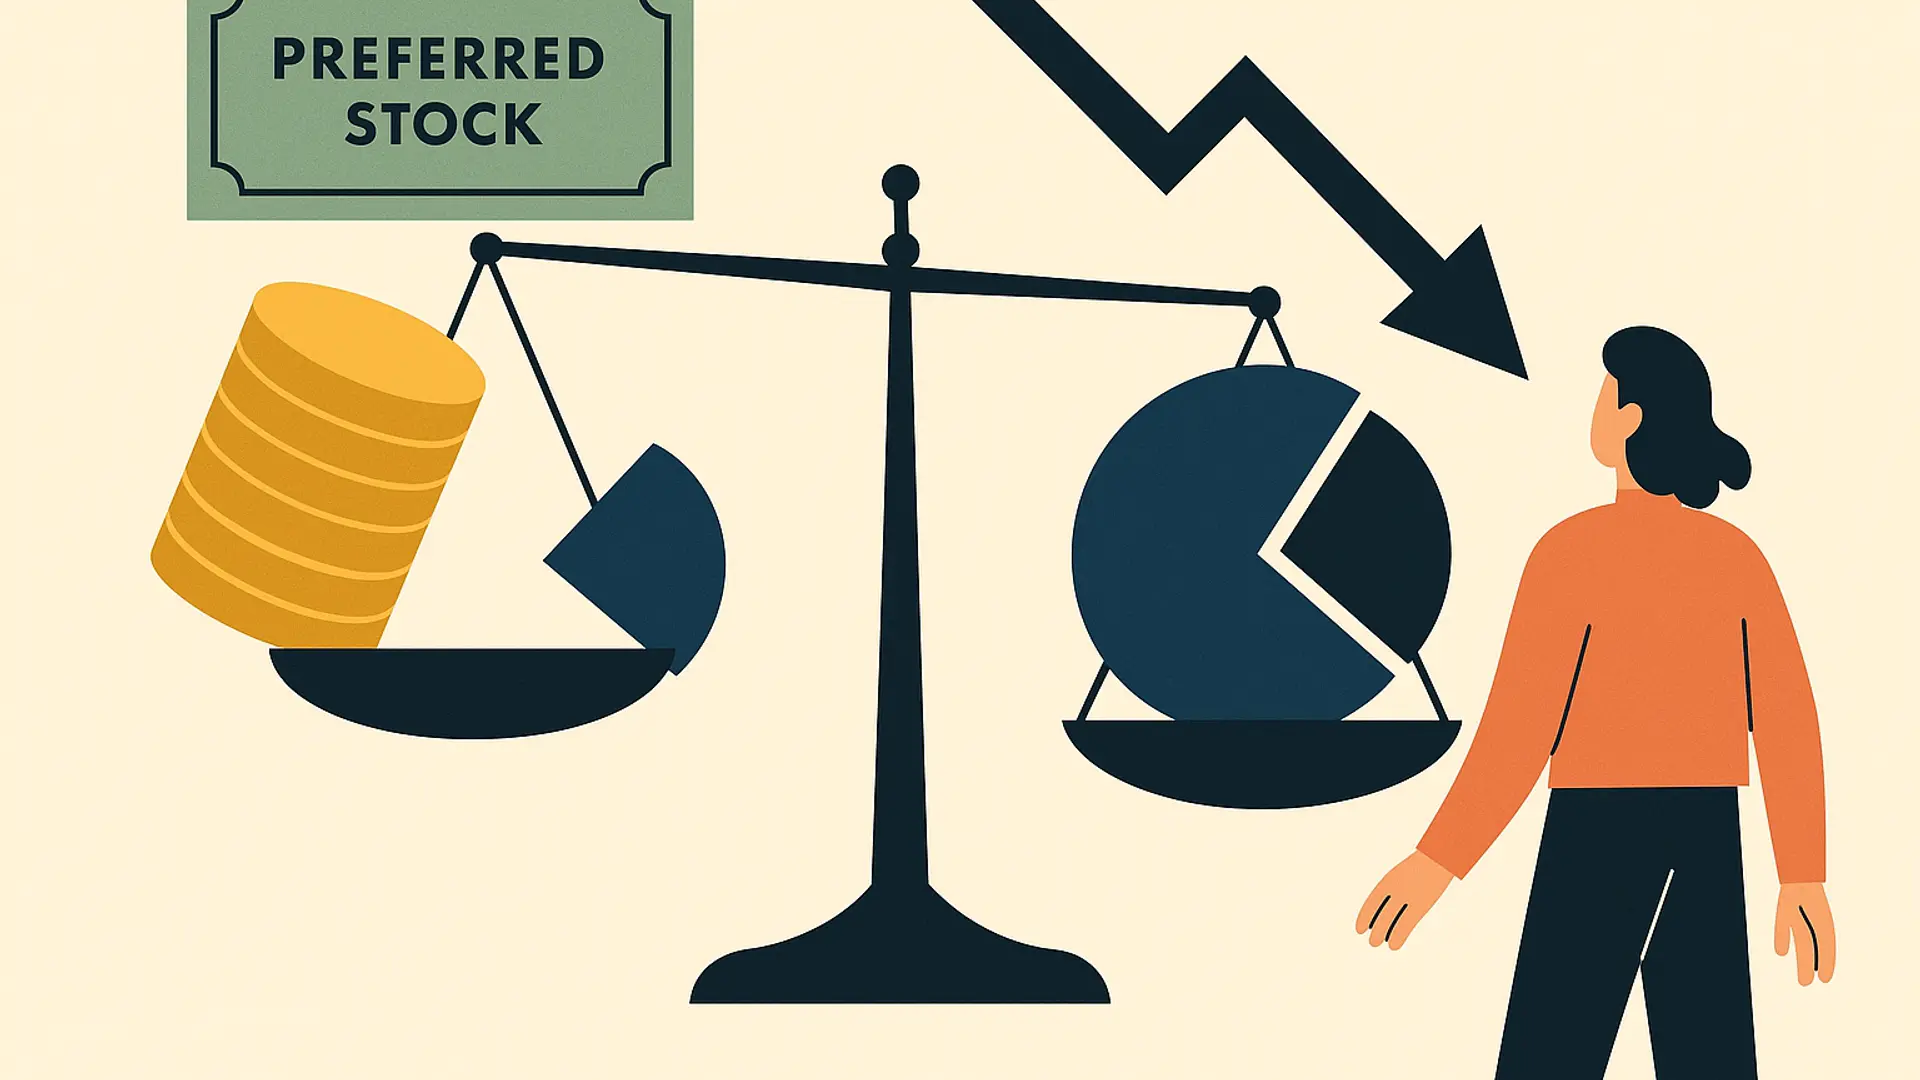
Anti-dilution protection is one of the most consequential clauses in any venture term sheet — and one of the least understood. When you raise at a lower valuation than your previous round, anti-dilution provisions determine how much your investors are protected from that loss. That protection comes directly out of your equity.
Here's what you need to know before you sign anything.
Key takeaways
- An anti-dilution provision protects preferred stock investors when a company raises new capital at a lower per-share price than they originally paid (a "down round").
- There are two main types: weighted average (the market standard, founder-friendly) and full ratchet (investor-friendly and punishing for founders).
- Anti-dilution provisions do not trigger in up rounds — only in rounds priced below the investor's original purchase price per share.
- The mechanism adjusts the investor's preferred-to-common conversion ratio, giving them more shares upon conversion — at the expense of founders and common shareholders.
- Most institutional VC deals use broad-based weighted average anti-dilution. If you see full ratchet, push back hard.
What is an anti-dilution provision?
An anti-dilution provision is a clause in preferred stock terms that protects investors from valuation decreases in future funding rounds. If your company raises capital at a lower price per share than an existing investor paid, anti-dilution rights adjust the conversion ratio of their preferred shares downward — effectively granting them more common shares upon conversion to partially compensate for the loss. The adjustment does not make investors whole. But it shifts a meaningful portion of the economic pain from investors to founders and common shareholders — and it can be severe if you don't know which type you agreed to.
Broad-Based Weighted Average | Full Ratchet | |
|---|---|---|
Trigger | Down round (lower price per share) | Down round (lower price per share) |
Adjustment basis | Blended price weighted by all dilutive shares | Fully reset to the new round's price |
Founder impact | Moderate dilution | Severe — can be catastropic |
Market standard? | Yes — institutional VC standard | Rare — red flag in most contexts |
When you see it | Standard term sheets from reputable VCs | Bridge rounds under duress, distressed deals |
Why down rounds trigger anti-dilution
A down round is any financing where new shares are sold at a lower price per share than the previous round. A company that raised a Series A at $2.00 per share and now raises a Series B at $1.20 per share has raised a down round.
This matters because investors hold preferred stock that converts to common stock at a fixed conversion price — typically the price they paid per share. In a down round, their preferred stock would convert to the same number of common shares it always would. But those shares are now worth less than the investor expected when they originally wrote the check.
Anti-dilution provisions adjust that conversion price downward. Instead of converting at $2.00 per share, the investor might now convert at a blended $1.60. That lower price means each preferred share converts to more common shares — partially offsetting the investor's per-share loss.
The economic reality: anti-dilution protection doesn't give investors new money. It gives them more of your company. In a down round, that additional dilution falls entirely on founders, employees, and common stockholders.
This is why understanding the type of anti-dilution you're granting matters as much as whether you're granting it at all.
How weighted average anti-dilution works: a worked example
Broad-based weighted average anti-dilution is the market standard. It accounts for the size of the down round — not just the new price — when calculating the adjusted conversion price. A small down round causes a small adjustment. A massive down round causes a larger one.
The formula:
New Conversion Price = CP × (OS + Money Raised ÷ Old CP) ÷ (OS + New Shares Issued)
Where:
- CP = original conversion price
- OS = fully diluted shares outstanding before the new round
- Money Raised ÷ Old CP = the hypothetical shares if money had been raised at the old price
- New Shares Issued = shares actually issued in the down round
The numbers:
- Series A investor paid $2.00 per share and holds 500,000 preferred shares
- Fully diluted shares outstanding (OS): 5,000,000
- Series B raises $2,000,000 at a down-round price of $1.00 per share, issuing 2,000,000 new shares
Step 1 — Hypothetical shares at old price: $2,000,000 ÷ $2.00 = 1,000,000 shares
Step 2 — Adjusted conversion price:
New CP = $2.00 × (5,000,000 + 1,000,000) ÷ (5,000,000 + 2,000,000)
New CP = $2.00 × 6,000,000 ÷ 7,000,000
New CP ≈ $1.714 per share
Step 3 — Conversion impact:
- Without anti-dilution: 500,000 preferred shares → 500,000 common shares
- With weighted average anti-dilution: investor's $1M invested ÷ $1.714 new CP = ~583,430 common shares
The investor gains approximately 83,430 additional shares — an ~17% increase in their common equity stake, funded entirely by dilution of everyone else.
This is weighted average at work. Meaningful. But measured.
Full ratchet anti-dilution: the nuclear option
Full ratchet is far simpler and far more punishing. Under full ratchet, the investor's conversion price resets completely to whatever per-share price the new investors paid — regardless of how many shares were sold at that price.
Using the same example:
- Series A investor's conversion price resets from $2.00 to $1.00
- Their 500,000 preferred shares now convert to 1,000,000 common shares — twice their original stake
- Every common shareholder is diluted by this reset accordingly
A single $50,000 bridge at a fire-sale price could reset the conversion terms on tens of millions in prior investment. Full ratchet provisions are sometimes called the "nuclear option" in VC negotiations — because the scale of damage is entirely uncorrelated with the size of the triggering round.
A small emergency bridge with full ratchet anti-dilution can transfer effective control of a company to investors before a single board meeting is called.
When does full ratchet appear? In distressed financing situations — a founder taking desperate bridge capital, a down-round lead extracting maximum terms, or an early deal with unsophisticated investors who used non-standard documents. In a competitive institutional raise from reputable VCs, full ratchet should not appear in the term sheet. If it does, that's information.
Where anti-dilution lives in your term sheet
Anti-dilution provisions are embedded in the Certificate of Incorporation (in the preference and conversion terms for preferred stock) and are referenced in the term sheet under the Conversion section.
In a standard NVCA-form term sheet, you'll see language like:
"The conversion price will be subject to broad-based weighted average adjustment to reduce dilution in the event that the Company issues additional equity securities at a purchase price less than the applicable conversion price."
That phrase — "broad-based weighted average" — is the market standard. "Full ratchet" is not. "Narrow-based weighted average" is a middle ground that still favors investors over founders relative to the broad-based standard.
Anti-dilution carve-outs matter just as much as the type. Standard term sheets exclude certain issuances from triggering anti-dilution rights: option pool grants to employees, shares issued in strategic partnerships, acquisition-related issuances. Review the carve-out list carefully. An option pool expansion at Series A should not trigger your seed investors' anti-dilution rights — but a poorly drafted agreement can create exactly that problem.
How to negotiate anti-dilution provisions as a founder
You have more leverage than you think — especially in a competitive fundraising environment.
Insist on broad-based weighted average. This is the market standard. Any lead investor requesting full ratchet in a normal institutional round is outside market norms. Name it clearly in your negotiation.
Push for a pay-to-play clause. A pay-to-play provision requires investors to participate in the down round to retain their anti-dilution rights. If they don't put in new money, their preferred stock converts to common — and their anti-dilution protections evaporate. This aligns incentives: investors who won't support the company in a difficult round lose the special protections designed for those who do.
Audit the carve-out list. Option pool expansions, strategic issuances, and equity grants to employees or advisors should be excluded from triggering anti-dilution. Missing a carve-out here can create cap table chaos at exactly the wrong moment.
Model the waterfall before signing anything. Run your cap table through a full waterfall analysis at multiple exit prices — $5M, $20M, $50M, $100M, $250M — with anti-dilution protections modeled in. The math will show you exactly how much equity shifts to investors at each exit price point. Your investors already have this model. Build yours.
Ready to connect with venture investors who negotiate fair terms?
Understanding anti-dilution mechanics is half the battle. The other half is being in the room with the right investors. Innovent's VC Match connects founders directly with venture capital firms matched to their stage, sector, and deal structure — so you're negotiating from a position of knowledge and leverage, not just gratitude.
Final Thought
Anti-dilution provisions are easy to ignore when you're closing a hot round at a strong valuation. They become very expensive when you're not.
The founders who survive down rounds with their equity intact are the ones who understood these mechanics before the first term sheet landed in their inbox. Broad-based weighted average anti-dilution is standard and fair. Full ratchet is not. Know the type you're agreeing to, run the waterfall analysis, and never sign a term you haven't modeled.
Your cap table is the most permanent record of every decision you make as a founder. Treat every clause in it accordingly.
FAQ
What is an anti-dilution provision in venture capital?
An anti-dilution provision is a preferred stock term that protects investors when a company raises new capital at a lower per-share price than they originally paid — a "down round." It adjusts the investor's preferred-to-common conversion ratio downward, granting them more common shares upon conversion to partially offset their per-share loss. That additional equity comes from the dilution of common stockholders — founders and employees.
What triggers anti-dilution provisions?
Anti-dilution provisions are triggered by a down round: any new share issuance priced below the protected investor's original purchase price per share. Standard carve-outs exclude employee option grants, strategic partnership issuances, and certain acquisition-related shares. Every term sheet's carve-out list is slightly different, which is why reviewing the specific language — not just the headline provision type — matters.
What is the difference between full ratchet and weighted average anti-dilution?
Under full ratchet, an investor's conversion price resets completely to the price paid in the new (lower) round, regardless of how many shares were sold at that price. Under weighted average (the market standard), the conversion price adjusts to a blended rate that accounts for the size of the new issuance — a substantially less punishing outcome for founders and common shareholders. Broad-based weighted average is what to insist on.
Is anti-dilution protection the same as pro rata rights?
No. Anti-dilution provisions protect investors from valuation decreases by adjusting their conversion terms. Pro rata rights give investors the right to participate in future rounds to maintain their current ownership percentage. They serve different purposes and typically appear in the same term sheet. Anti-dilution applies in down rounds; pro rata rights apply in up rounds and flat rounds where a founder raises new capital from new investors.
Can founders negotiate anti-dilution provisions out of a term sheet entirely?
Rarely — some form of anti-dilution protection is nearly universal in institutional VC deals and is considered market standard. What founders can negotiate is the type (broad-based weighted average vs. full ratchet), the carve-out list, and whether a pay-to-play condition applies. In a highly competitive fundraise, some founders have secured aggressive pay-to-play provisions that make anti-dilution rights effectively conditional — but eliminating anti-dilution entirely is an unusual outcome.
Related Articles
Series A Funding: What It Is, What Investors Want, and How to Raise It
Most founders treat Series A like a bigger seed round. It isn't. The investors are different, the bar is different, a...
What Is a Term Sheet? A Founder's Complete Guide to VC Term Sheets
Key takeaways• A term sheet is a non-binding document outlining the key economic and governance terms of a venture in...