This is a sample investor memo. It shows what a completed investor submission brief looks like.
Learn More About Investor AccessInvestor Brief
VCMatch.ai
Stage SeedEnterprise Software / SaaS
Matches startups to the right investors using public and proprietary signals, cutting fundraising time by 60%+.
01
Investment Summary
- First Pass Memo
VCMatch.ai is a B2B SaaS fundraising infrastructure play with strong early traction ($431k ARR, 18% MoM growth, 112% NRR) targeting a clear founder pain point. The AI-powered investor matching thesis aligns well with Innovent's AI/ML vertical disruption focus and hands-on operator model. However, team credibility gaps, competitive positioning uncertainty, and data moat defensibility warrant deeper diligence before advancing.
02
Deal Highlights
- Why This Company Is Interesting
Strong early unit economics: 5.2x LTV/CAC with 2.5-month payback period demonstrates capital-efficient growth potential—this is exceptional for early-stage B2B SaaS and suggests product-market fit
Impressive net revenue retention at 112% (Q2 2025) with only 3.2% monthly logo churn indicates strong product stickiness and expansion revenue—customers are finding value and buying more over time
Accelerator partnership traction (6 pilots, 2 revenue share agreements, 14 university programs in pipeline) creates scalable distribution channel with high-intent customer acquisition—could drive rapid ARR growth with low CAC
Proprietary investor graph with 2.1M relationship edges and feedback-trained ML model represents early data moat—network effects strengthen with usage, creating defensibility if execution continues
$1.2M of $2.5M round already committed at $10M cap suggests external validation and reduces execution risk—round is 48% filled with 18-month runway planned
03
Problem & Solution
- Company One-Liner
Matches startups to the right investors using public and proprietary signals, cutting fundraising time by 60%+.
- Problem
Founders spend 200+ hours per fundraising round emailing the wrong investors with an average reply rate below 2%. VCs are flooded with off-thesis pitches while sourcing remains manual despite abundant data. This results in slow fundraising processes, warm-intro bias, and missed matches for both founders and investors.
- Solution
VCMatch is a matching engine that ranks investor fit using firm theses, check sizes, geography, stage, and portfolio signals. Founders complete a 10-minute intake, receive an auto-generated startup profile and ranked investor list with reason codes, can send one-click personalized email sequences, and sync with their CRM. The system includes a feedback loop where outcomes and replies retrain the ranking model for continuous improvement in match precision.
Additional Product Data
Value Propositions
Cuts fundraising time by 60%+ by eliminating manual investor research and targeting, Increases reply rates from <2% baseline through AI-powered investor fit scoring and personalized outreach, Provides transparent reason codes for each match, helping founders understand why specific investors are recommended, Integrates seamlessly with Gmail, Outlook, HubSpot, and Notion for frictionless workflow adoption, and Improves outcomes for both sides through data-driven matching that reduces off-thesis pitches and missed opportunities
Unique Selling Points
Investor fit scoring with explainable reason codes—not just a ranked list, but a transparent explanation of why each investor matches, Feedback-trained ranking model that improves precision over time using labeled outcomes and reply data, creating a data network effect, Warm intro graph that identifies connection paths to investors, reducing cold outreach friction, and Proprietary investor graph with 45k firm/partner profiles and 2.1M relationship edges normalized for thesis and portfolio signals
04
Market Opportunity
- Industry
Enterprise Software / SaaS
- Verticals
Fundraising Infrastructure, Venture Capital Technology, Founder Tools, and B2B SaaS
- Market Size
TAM
$173m
05
Business Model
- Model Type
B2B SaaS
- Revenue Model
Subscription and Success-based fees
- Pricing
Overview
- ACV
- $1.32k
- Model
- Tiered per-seat monthly subscription with optional success fee
06
Traction Snapshot
- Key Metrics
$431k ARR with $35.9k MRR from 410 paying customers (2,300 total users). ACV of $1,320 suggests mix of Solo ($99/mo) and Team ($499/mo) plans with limited Pro ($999/mo) uptake. 5.2x LTV/CAC with 2.5-month payback indicates strong unit economics. 112% NRR with 3.2% monthly logo churn (~33% annual) shows product stickiness and expansion revenue.
- Growth Signals
18% MoM growth in both paid customers and users demonstrates consistent, compounding expansion. Accelerator partnerships scaling (6 pilots → 2 signed deals → 14 pipeline) suggests distribution channel validation. $1.2M of $2.5M round committed at $10M cap indicates investor interest. Revenue growth trajectory implies ~$600k+ ARR by end of 2025 if momentum holds.
- Market Validation
410 paying customers willing to spend $1,320 ACV validates founder willingness to pay for fundraising efficiency. 112% NRR proves customers expand usage (likely adding team seats or upgrading tiers), indicating product delivers ROI. Accelerator revenue share agreements (vs. just pilots) show institutional buyers see value in offering to portfolio companies. Low 2.5-month payback suggests strong word-of-mouth and product-led acquisition working.
- Headline Metrics
ARR
$430.8k
MRR
$35.9k
LTV
$1.18k
CAC
$230
ARPU Paid
87.56
LTV CAC Ratio
$5
Payback Months
2.5
Nrr Q2 2025
1.12
Logo Churn Monthly
3.2%
07
Team
- Founders
Amy Rivera — CEO
Avi Flombaum — CTO
Brett Lee — Head of Data
08
Founder Assessment
- Team Overview
Mixed signals on team strength. CTO Avi Flombaum is a known quantity (Flatiron School founder/exit) with proven Rails/AI architecture chops—this is a significant positive. CEO Amy Rivera shows strong early GTM execution (18% MoM growth, solid unit economics) but lacks verifiable track record without disclosed company names. Head of Data Brett Lee's background is similarly opaque.
- Domain Expertise
Team has relevant domain exposure but depth is unclear. CEO's venture platform background suggests fundraising ecosystem familiarity, but 'growth lead' role may indicate limited CEO/founder experience. CTO's edtech exit demonstrates 0→1 scaling ability but not in B2B SaaS infrastructure. Data lead's knowledge graph expertise is on-point for product needs. Advisor bench (seed fund partner, CRM product lead) adds credibility if names can be verified.
- Team Dynamics
Product-engineering balance appears strong with experienced CTO, but CEO's GTM track record needs validation. No mention of design, sales, or customer success leadership—at $431k ARR with 410 customers, this is becoming a gap. Three-person core team (CEO/CTO/Data) is lean for a product requiring both technical infrastructure and sales motion scaling. Advisor involvement level unclear—are they active or letterhead?
- Notable Backgrounds
Avi Flombaum (CTO): Flatiron School founder with successful exit—proven technical leadership and company-building experience
Amy Rivera (CEO): Two B2B SaaS exits claimed but companies not disclosed—requires verification in diligence
Advisor network includes former seed fund partner—suggests fundraising ecosystem credibility if relationship is substantive
09
Fundraising
- Stage
Seed
- Target Amount
$2.5m
- Raised To Date
$1.2m
- Use Of Funds
Category: Product & Data · Percentage: 45% · Description: Engineering, data infrastructure, and ML model development, Category: Sales & Marketing (GTM) · Percentage: 35% · Description: Sales team, marketing, and customer acquisition, and Category: General & Administrative · Percentage: 20% · Description: Operations and overhead
Additional Fundraising Data
Target Ranges
Amounts: 2.5M · Currency: USD · Raw Text: 2500000 · Max Amount: $2.5m · Min Amount: $2.5m
10
Thesis Alignment
- Alignment Summary
Strong alignment across multiple Innovent thesis dimensions: AI/ML vertical market disruption (core product), Enterprise SaaS (business model), and FinTech adjacency (fundraising infrastructure). The product-led growth motion and technical founding team match Innovent's preference for full-stack builders with shipping velocity. Post-product, post-launch stage with demonstrated PMF signals fits their seed investment criteria.
- Strategic Fit
Innovent's hands-on operational model is highly relevant here: CTPO Avi Flombaum's expertise in data infrastructure and product scaling directly addresses VCMatch's need for ML systems guidance. The firm's 30-year fundraising network and portfolio of 32 companies creates immediate value-add through investor graph validation, warm intro expansion, and accelerator partnership introductions. Family office structure allows patient capital for data moat development.
- Portfolio Synergies
Carta (cap table management) - natural integration partner for fundraising workflow; potential joint GTM with shared customer base
Spiky AI, NextLM (AI/ML portfolio) - technical knowledge sharing on ML model training, data infrastructure scaling, and explainable AI implementation
Credit Sesame, Selectfi (FinTech) - parallel B2C financial matching models; learnings on data network effects and algorithmic recommendation systems
11
Vision & Exit
- 5-Year Vision
VCMatch will become the default matching infrastructure layer between founders and capital globally, processing thousands of fundraises annually with AI-driven precision. The platform will evolve into a comprehensive fundraising data API and ecosystem, serving not just founders but also accelerators, scouts, and institutional investors seeking better signal and efficiency.
- Impact Goals
Reduce time-to-close for fundraising rounds by 60%+, Broaden access to capital by removing warm-intro bias and leveling the playing field for underrepresented founders, and Improve signal quality for both founders and investors through data-driven matching
- Exit Strategy
Strategic acquisition by CRMs, data providers, or fundraising exchanges; potential for infrastructure/API play positioning company as critical fundraising data layer
12
Discussion Points
- Topics to Explore in a Partner Meeting
Team credibility verification and leadership gaps
CEO's two claimed B2B SaaS exits need company names and verification through backchannel references. At $431k ARR with 410 customers, lack of dedicated sales/CS leadership is concerning for scaling to $2M+ ARR. Discuss hiring plan specifics, sales motion strategy, and whether CEO has led sales teams before. Verify advisor involvement level and willingness to make intros.
Competitive landscape and data moat defensibility
No direct competitors named raises red flag—Crunchbase, PitchBook, Harmonic, and others operate in adjacent space. Need to understand: (1) why incumbents haven't built this, (2) what prevents well-funded data providers from adding matching features, (3) how defensible the 2.1M relationship graph is long-term, (4) data refresh cadence and accuracy vs. competitors. This is critical for validating $10M valuation and long-term moat.
Revenue mix and customer concentration risk
Heavy accelerator partnership focus (6 pilots, 2 revenue share deals) creates distribution leverage but also concentration risk. Need to understand: (1) what % of $431k ARR comes from direct founder subscriptions vs. institutional partnerships, (2) revenue share economics and margin impact, (3) churn risk if 1-2 large accelerator partnerships end, (4) scalability of founder-direct motion without partnerships. This affects growth predictability and valuation.
Market sizing validation and TAM expansion path
TAM of $173M ARR seems conservative (120k founders × $120/mo) but lacks SAM/SOM breakdown and top-down validation. At 410 customers, they're at 0.34% penetration—what's realistic capture rate? Discuss expansion beyond fundraising founders: (1) VCs for sourcing (mentioned but not quantified), (2) scouts and angels, (3) M&A advisors, (4) corporate venture. Understanding addressable market growth affects outcome potential and return profile.
Product roadmap and AI differentiation sustainability
Explainable AI and feedback-trained ML model are differentiators today, but AI capabilities are commoditizing rapidly. Discuss: (1) proprietary data advantages vs. public data sources, (2) model architecture and training approach, (3) roadmap for maintaining AI edge as OpenAI/Anthropic improve, (4) plans for warm intro automation and outcome tracking. This determines whether 'AI-powered' is a feature or sustainable moat.
For Investor Teams
Learn everything about inbound deals with zero effort
Allow submissions directly from your website into an AI-powered deal pipeline. VCMatch generates AI briefs so your team can process deal flow faster and with more intelligence, then decide whether to accept a pitch or pass.
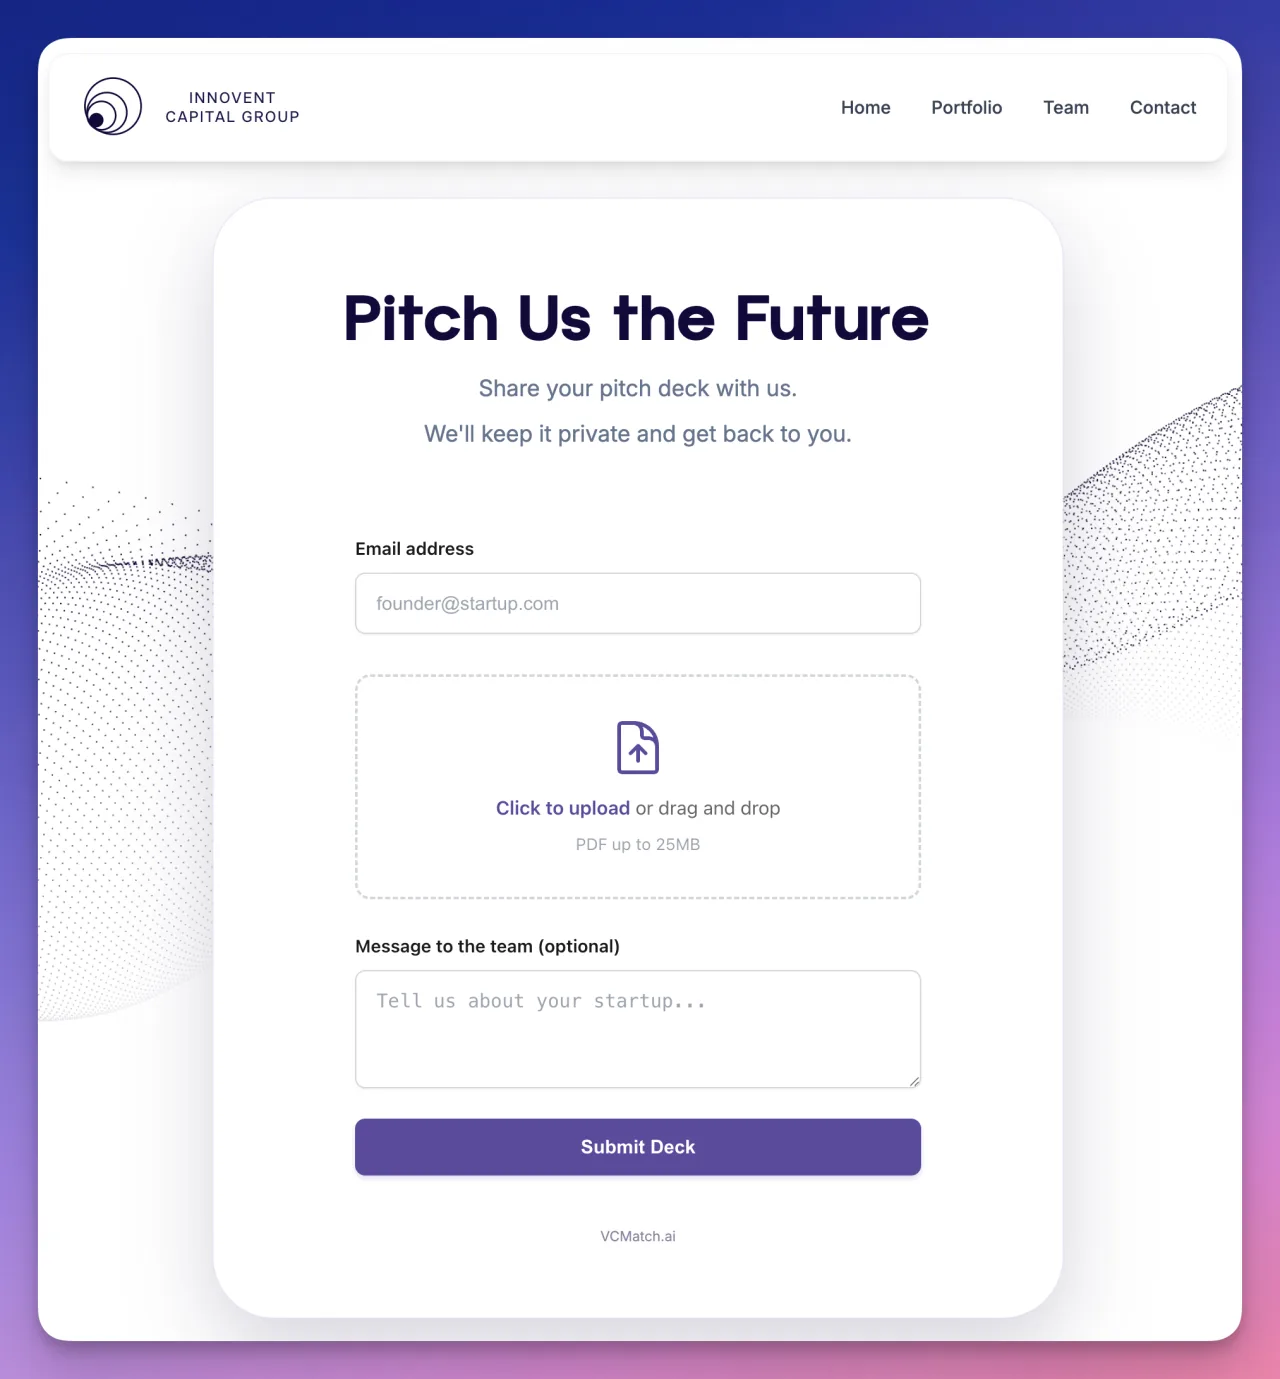
Capture submissions directly from your website
Deploy the embed in minutes and turn your site into a clean, branded intake point for inbound opportunities.
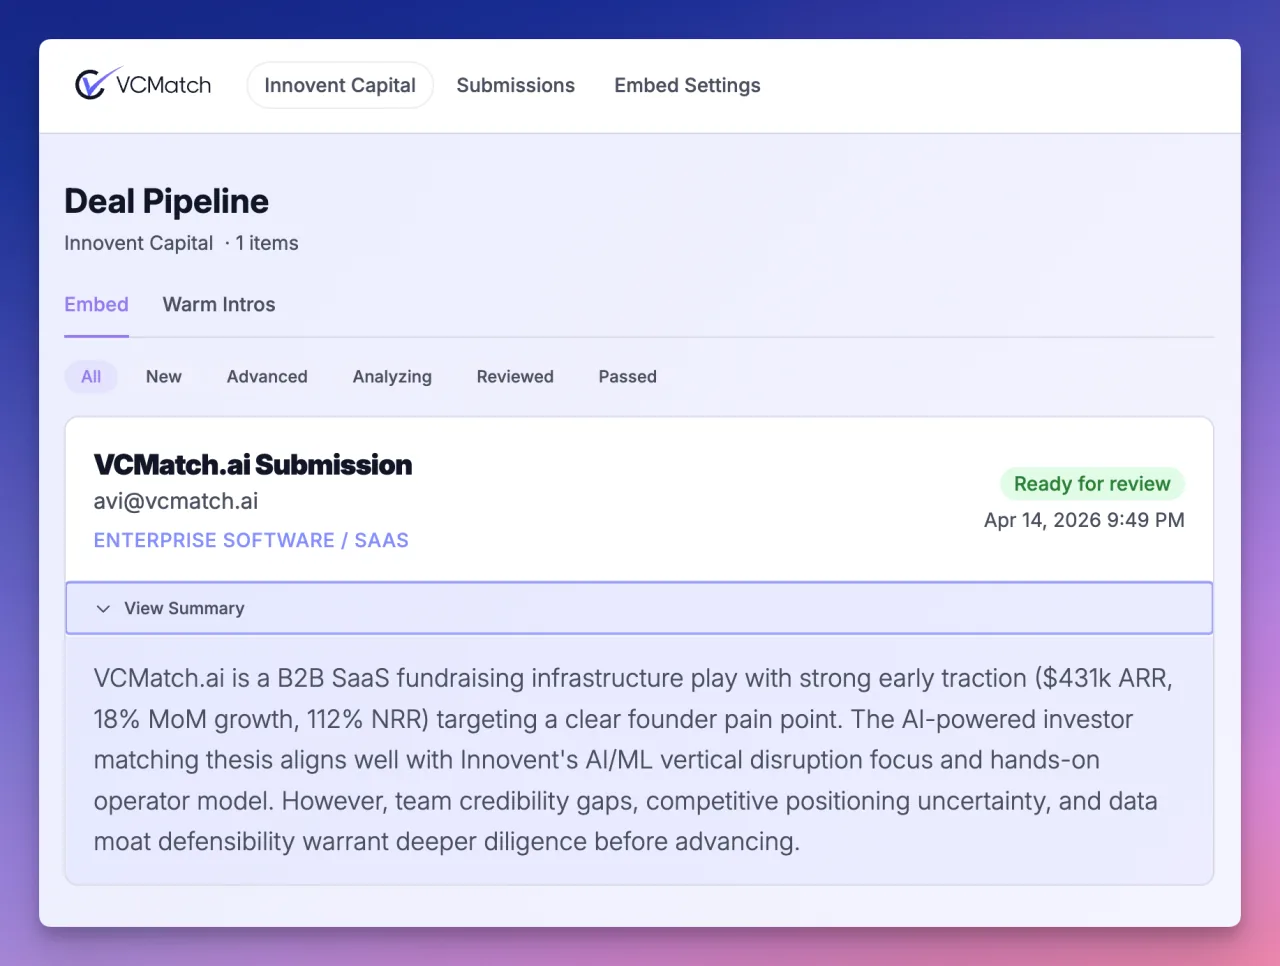
Review faster with AI-powered briefs
Every submission is enriched into an AI brief so your team can make smarter accept-or-pass decisions with less manual work.