Drag-Along Rights: The Term Sheet Clause That Can Force You to Sell Your Company
Most founders read the drag-along clause and move on. That's exactly what their investors are hoping for. Drag-along rights are one of the most po...
Most founders read the drag-along clause and move on. That's exactly what their investors are hoping for.
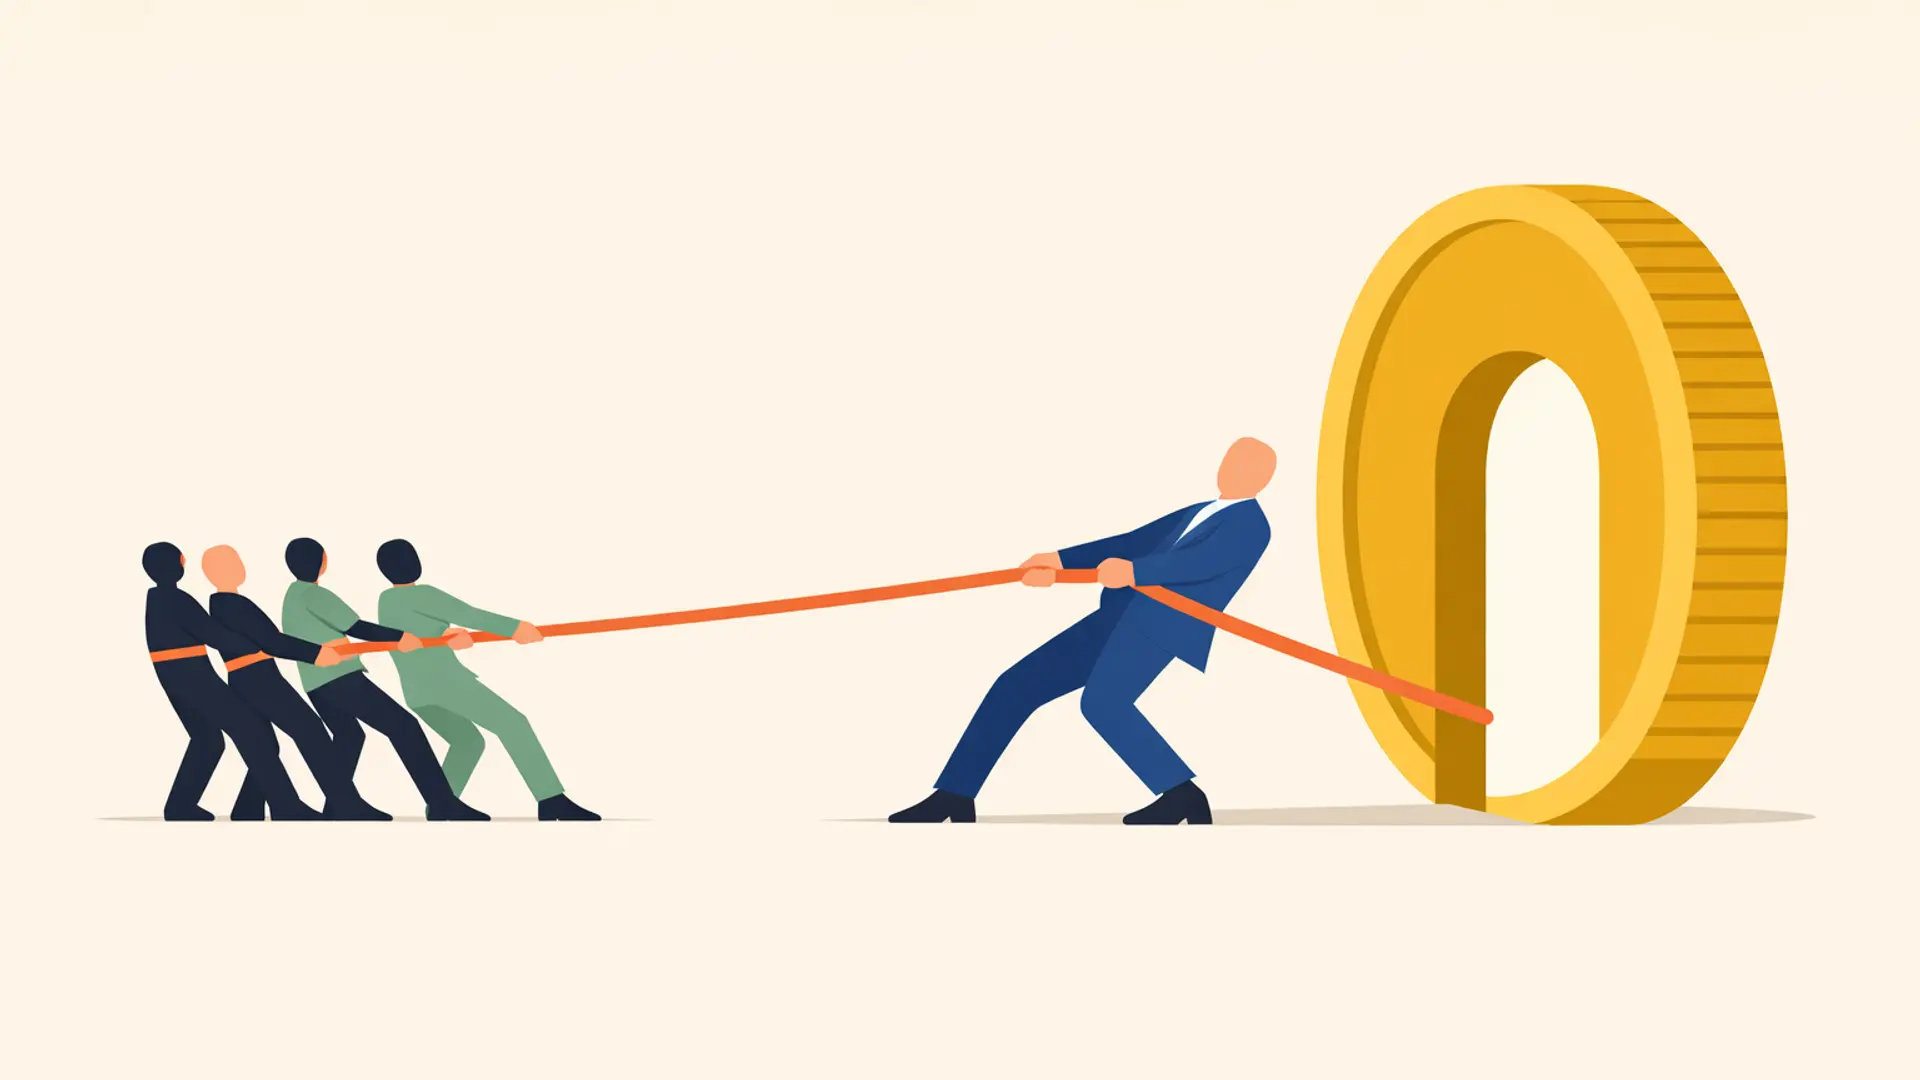
Drag-along rights are one of the most powerful — and least discussed — provisions in any venture term sheet. They give your investors the ability to force a sale of the company even if you don't want to sell. If you hold common stock, a broad drag-along can override your vote entirely. If you haven't modeled this out, you haven't fully understood your term sheet.
This is the explainer you should read before signing anything.
Key takeaways
- Drag-along rights give a majority shareholder (usually investors) the right to force all other shareholders to approve a sale of the company
- They override individual objections — if the drag-along threshold is met, you must vote yes on the acquisition even if you disagree
- The drag-along is designed to prevent a small minority from blocking a sale that the majority wants
- Negotiating the threshold, trigger, and price floor determines whether drag-along rights are founder-friendly or founder-hostile
- Drag-along rights are distinct from tag-along (co-sale) rights — they force a sale rather than allow participation in one
What are drag-along rights?
Drag-along rights are a provision in a shareholder agreement or investor rights agreement that allows a majority shareholder — typically investors, once their ownership passes a defined threshold — to "drag along" all other shareholders into a sale of the company. If the drag-along is triggered, every shareholder must vote to approve the sale and tender their shares at the agreed price, regardless of their individual preference.
The core logic is straightforward: investors don't want a minority founder, ex-employee, or early angel to hold the company hostage during an otherwise viable exit.
A drag-along right doesn't mean your investors can sell the company without cause — it means they can proceed with a sale without your consent if the threshold conditions are met.
How drag-along rights work: a worked example
Imagine you raised a $5M seed round. Your cap table looks like this:
Shareholder | Ownership |
|---|---|
Founders (2) | 60% |
Seed investors | 25% |
Option pool | 15% |
Five years in, an acquirer offers $40M for the company. Your seed investors want to take the deal. You don't — you think the company is worth $70M and you're not ready to sell.
Without a drag-along clause, you vote no. The acquisition doesn't proceed unless you approve it. Your investors are stuck.
With a drag-along clause triggered by majority investor approval only, you're required to vote yes. The sale closes. You receive your proportional payout. Your objection doesn't change the outcome.
That's the mechanism in a paragraph. The question isn't whether this provision exists in your documents — it almost certainly does. The question is what the specific terms around it say.
Drag-along rights vs tag-along rights: what's the difference?
This is where most founders get confused. Drag-along and tag-along rights are opposites.
Feature | Drag-Along Rights | Tag-Along (Co-Sale) Rights |
|---|---|---|
Who exercises it | Majority shareholders (investors) | Minority shareholders (early investors, founders) |
What it does | Forces others into a sale | Allows others to participate in a sale |
Direction | Pushes you in | Lets you in |
Protects | Majority from minority holdouts | Minority from being left out |
Founder posture | Negotiate carefully | Push to include |
Tag-along rights protect minority shareholders. If a majority shareholder sells their stake, tag-along rights let you sell yours at the same price and terms. They are a shield.
Drag-along rights protect majority shareholders from holdouts. They are a lever — and the terms determine who holds it.
Both appear in term sheets. You want favorable tag-along rights as a founder. You want carefully bounded drag-along terms. And you want to negotiate both before you sign.
Where drag-along rights live in the term sheet
Drag-along rights typically appear in the Voting Agreement or Investor Rights Agreement — not in the main economics section of the term sheet. They are easy to overlook during the high-adrenaline phase of closing a round, which is exactly when most founders miss them.
The key variables to scrutinize:
Trigger threshold. What percentage of shareholders must approve the sale to activate the drag? Industry standard is a majority of preferred (investors) plus a majority of common (founders and employees). An investor-friendly version requires only a majority of preferred — giving your investors the ability to drag you without your vote.
Price protections. Some drag-along agreements require the acquisition price to meet a minimum return before the drag can be invoked — for example, 1× or 1.5× invested capital. If your investors paid $5M, the drag only fires on deals worth at least $5M (or $7.5M). No floor means your investors could accept a distressed sale and drag you into it.
Who is dragged. Does the clause apply to all common holders, or specifically to the founding team? Broad provisions that drag option holders can create complications for employees.
Exit process requirements. The best drag-along provisions require board approval as a second hurdle before the clause can be triggered. That two-step process creates meaningful friction against rushed or low-price exits.
Founder-hostile version: a drag-along triggered by a simple majority of preferred stock only, at any price, with no minimum return floor. That's your investors deciding when you sell and for how much.
Founder-friendly version: a drag-along requiring majority approval from both common and preferred, above a minimum price floor, with board approval as an additional gate.
Why investors insist on drag-along rights
Investors have legitimate reasons to want drag-along protection — and understanding those reasons helps you negotiate more effectively.
Imagine 95% of your cap table supports a $60M acquisition, but one early angel who owns 1% of the company is holding out for $80M. Without a drag-along, that single investor can kill a deal that benefits everyone else. With properly constructed drag-along rights, the majority can proceed.
The drag-along doesn't just protect investors — it also protects you from bad actors. The issue isn't whether the provision should exist. It's whether the terms reflect a genuine balance of interests or a lopsided advantage.
When investors ask for a drag-along triggered only by preferred majority at any price, they're asking for the ability to force an exit that benefits them disproportionately — especially if they have a liquidation preference that makes a low sale price acceptable to them even when it leaves founders with little. That's the version worth negotiating hard against.
How to negotiate drag-along rights
You have more leverage before you sign than after. Here's what to push for in order of importance:
1. Require both common and preferred approval. This is the most important point. If your approval as a common stockholder is required to trigger the drag, the provision can't be used against your interests without your consent. Push for this first.
2. Set a minimum price floor. Negotiate a floor — typically 1× or 1.5× return on invested capital, or a specified dollar threshold. This prevents investors from accepting a fire-sale acquisition price while dragging you along.
3. Require board approval. A second-hurdle board vote adds meaningful friction. It also gives independent directors a say in the process, which is important if your board has investor-appointed seats.
4. Carve out unvested option holders. Make sure the drag-along doesn't bind holders of unvested options. Those are employees who can't vote their shares in a meaningful way and shouldn't be swept into the mechanism.
5. Sunset the drag on a timeline. Some drag-along provisions are time-limited — they expire if not exercised within a certain window. This is less common but worth raising.
Ready to find investors who structure deals fairly?
The drag-along clause is one of the clearest signals of an investor's disposition toward founders. Investors who push for uncapped, investor-only drag triggers with no price floor are signaling something about how they behave when outcomes are uncertain.
Innovent's VC Match connects startup founders with the right venture investors for their stage, sector, and structure — so you're not comparing term sheets from investors who don't understand your business or don't have your interests at heart. If you're in market, start there before your next term sheet conversation.
FAQ
What is a drag-along right in simple terms?
A drag-along right is a provision that allows a majority shareholder — typically investors — to force all other shareholders to approve a sale of the company. If the drag-along threshold is met and the provision is triggered, minority shareholders must vote yes on the acquisition and sell their shares at the agreed price, even if they personally object to the deal.
Are drag-along rights standard in venture deals?
Yes. Drag-along rights appear in virtually all institutional venture deals, typically in the Voting Agreement or Investor Rights Agreement. The question isn't whether they'll be there — it's what the specific trigger, threshold, and price protection terms say. Those details are negotiable.
Can founders negotiate drag-along terms?
Absolutely. The most important things to negotiate are (1) requiring both preferred and common majority approval before the drag is triggered, (2) setting a minimum price floor, and (3) requiring board approval as a second hurdle. First-time founders often skip these negotiations; experienced founders prioritize them because they know what happens at exit.
What happens if I refuse to honor a drag-along right?
If a drag-along provision is validly triggered and you refuse to vote in favor of the acquisition, you are in breach of your shareholder agreement. This can result in legal liability. Many drag-along agreements also include an irrevocable proxy clause — meaning the other shareholders can vote your shares on your behalf if you refuse to exercise them.
What's the difference between drag-along and co-sale (tag-along) rights?
Drag-along rights are exercised by majority shareholders to force all shareholders into a sale. Tag-along (co-sale) rights are exercised by minority shareholders to participate in a sale on the same terms as the majority. Drag-along pushes you into a deal you may not want; tag-along lets you into a deal you'd otherwise be excluded from. Both should be in your shareholder agreement — but they serve opposite purposes.
Final Thought
A term sheet isn't just a valuation. It's a governance document. The drag-along clause is one of the clearest examples of this: it has nothing to do with your daily operations, never appears in your pitch deck, and barely comes up in founder conversations — until the moment an acquisition offer lands and you discover, for the first time, exactly what you agreed to two funding rounds ago.
Read the drag-along. Negotiate the trigger. Set a price floor. Know your tag-along rights. It takes twenty minutes to understand and can be the difference between millions of dollars in your pocket and a payout that leaves you wondering what happened.
The best investors know the difference between protecting themselves and cornering you. Find those investors, and the drag-along clause will never keep you up at night.
Related Articles
Startup Equity Vesting: The Complete Founder's Guide
Key takeaways• Standard structure: 4-year vesting with a 1-year cliff is the default for founders and employees — dev...
Liquidation Preference Explained: What Every Founder Must Know Before Signing
You raised money. You feel good. Now read the liquidation preference clause — because it determines how much of your ...