Liquidation Preference Explained: What Every Founder Must Know Before Signing
You raised money. You feel good. Now read the liquidation preference clause — because it determines how much of your exit you actually keep. Key t...
You raised money. You feel good. Now read the liquidation preference clause — because it determines how much of your exit you actually keep.
Key takeaways
- A liquidation preference gives investors the right to be paid before founders and employees in any exit event.
- The market standard is 1× non-participating preferred — investors get their money back first, then convert to common if that pays more.
- Participating preferred lets investors double-dip: they claim their preference and share in remaining proceeds alongside common shareholders.
- Liquidation preference matters most in the moderate exits ($15M–$80M) that are far more common than unicorn outcomes.
- Always model a waterfall analysis at multiple exit prices before signing any term sheet.
A liquidation preference is a preferred shareholder's right to receive a specified return — usually 1× their invested capital — before any proceeds are distributed to common stockholders. It is triggered by a "liquidity event": an acquisition, merger, or wind-down. In most scenarios, it is the single clause that most directly determines how much founders and employees take home.
What is liquidation preference in venture capital?
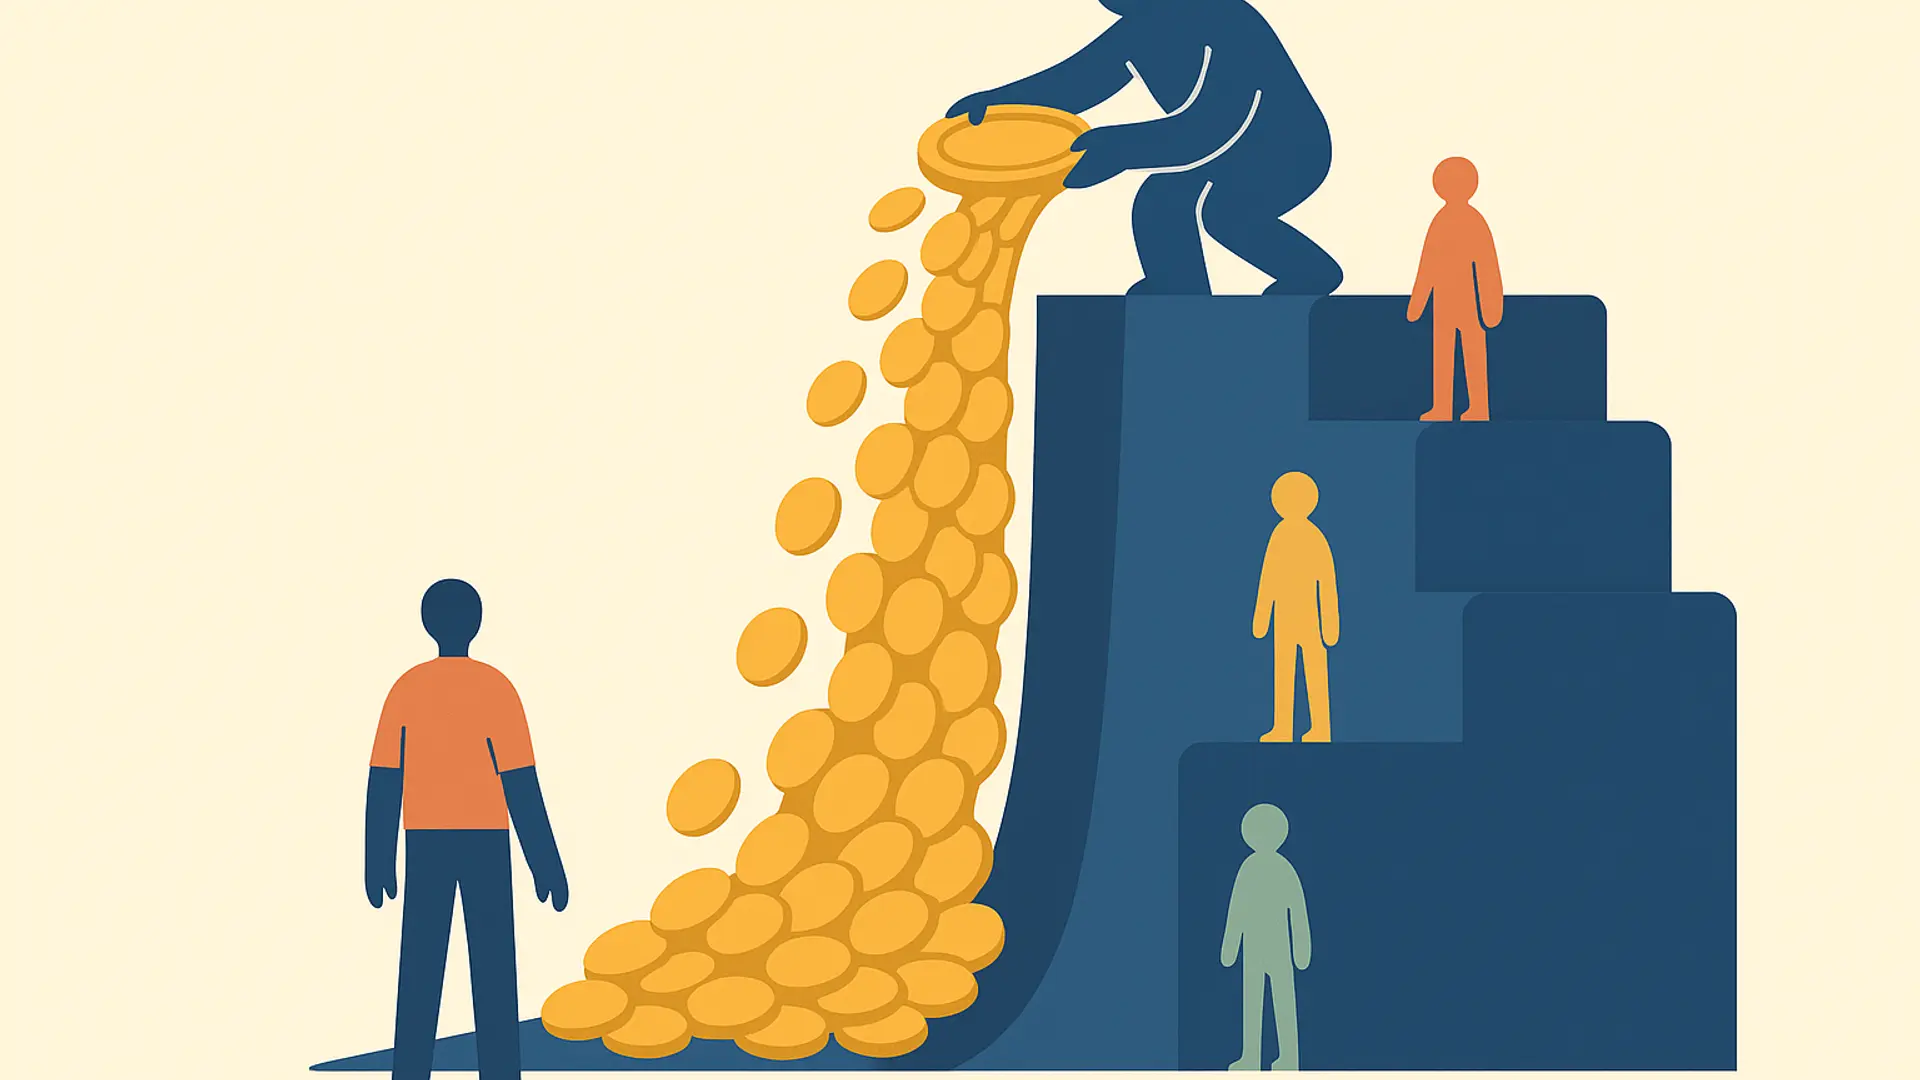
A liquidation preference is the investor's first claim on exit proceeds. Before founders, before employees, before any common shareholders — preferred investors are made whole first. The "preference" is expressed as a multiple of invested capital (1×, 2×, sometimes higher) and sets the minimum a preferred shareholder receives before anyone else participates.
Liquidation preference does not apply to IPOs. When a company goes public, preferred shares convert to common and the preference dissolves. It applies to acquisitions, mergers, and formal wind-downs — the full range of outcomes that are not a public offering.
How does liquidation preference work? A worked example
Say a VC invests $5M at a $20M post-money valuation, taking 25% ownership with a 1× non-participating liquidation preference.
Scenario A: Your startup sells for $8M
- Investor takes $5M (their 1× preference)
- Common shareholders split the remaining $3M
- Your 75% of $3M = $2.25M — not the $6M you'd expect from 75% of $8M
Scenario B: Your startup sells for $30M
- 25% of $30M = $7.5M, which exceeds the $5M preference
- Investor converts to common and takes $7.5M
- Common shareholders split the remaining $22.5M
The liquidation preference protects investors in down or moderate exits. In a large exit, investors convert to common because it pays more.
The crossover point — where investors stop claiming the preference and start converting to common — is called the conversion threshold. Understanding where it sits for your specific round is essential before signing anything.
Participating vs. non-participating: the distinction that costs founders money
Non-participating preferred (founder-friendly): The investor takes either their preference or their pro-rata share of proceeds as converted common — whichever is higher. Standard in competitive institutional VC rounds today.
Participating preferred (investor-friendly): The investor takes their preference first, then participates in the remaining proceeds alongside common shareholders. They get paid twice.
Same $5M investment, same $30M exit — but now with participating preferred:
- Step 1: Investor takes $5M preference
- Step 2: Investor participates in the remaining $25M at 25% = $6.25M
- Investor total: $11.25M (vs. $7.5M in the non-participating scenario)
- Common shareholders receive: $18.75M (vs. $22.5M)
That is a $3.75M swing in a company that delivered a healthy return for everyone involved. Multiply this across multiple rounds with participation rights and the impact on founder liquidity compounds quickly.
Some participating preferred terms include a participation cap — a ceiling, e.g., 3× the original investment, above which the investor converts to common rather than continuing to participate. These are a reasonable middle ground, but still dilute common equity at moderate exit prices.
The liquidation preference multiplier: 1×, 2×, and beyond
Most institutional VC rounds carry 1× preference — investors get their capital back first, nothing more. In bridge rounds, down rounds, or structured financings under duress, you may see:
- 2× preference: Investor receives twice their investment before common sees a dollar. On a $10M check, common receives nothing until exit exceeds $20M.
- 3× preference: Rare in standard VC; appears in recapitalization scenarios or emergency financings.
Always model the impact at your realistic exit range. A 2× preference on a $10M investment means that in a $25M exit, the investor takes $20M and common shareholders split the remaining $5M — regardless of how much equity common holds.
Rule of thumb: every additional "×" on your preference is a dollar-for-dollar reduction in founder and employee upside at moderate exit prices.
Where liquidation preference sits in the term sheet
Look for it in the "Liquidation Preference" section — typically after valuation and capitalization terms, before anti-dilution provisions. Four things to review immediately:
- Multiplier: 1×, 2×, or higher?
- Participating or non-participating? The most impactful flag in the entire section
- Participation cap: If participating, is there a ceiling?
- Seniority: Later-stage investors often sit senior to earlier rounds
That last point matters in complex cap tables. If your Series B sits senior to Series A in a $20M exit, Series A investors may be wiped out before they ever apply their own preference — even though they took on the highest early risk.
What liquidation preference means for your cap table and your team
Liquidation preference is irrelevant in a home-run exit. If your company sells for 10× total capital raised, everyone converts to common and the waterfall is clean.
It matters enormously in the $15M–$80M exits that represent the majority of VC-backed outcomes. At these valuations, preference terms and participation rights directly determine what founders and employees actually take home — sometimes the difference between a life-changing outcome and a modest one.
How to negotiate:
- Push for 1× non-participating as your baseline — it is market standard for top-tier institutional VC
- Avoid participating preferred; if unavoidable, insist on a 3× participation cap at minimum
- Run a waterfall model at $10M, $25M, $50M, and $100M exit prices before you countersign
- Track seniority stacking carefully as you raise additional rounds
The right investors structure deals that work for both sides. Heavily preferred cap tables deter future investors just as much as they hurt founder economics.
VC Match connects founders with venture investors aligned to your stage, sector, and deal structure — investors who come with market-standard terms and transparent waterfall economics. Explore VC Match →
FAQ
What is a liquidation preference in simple terms?
A liquidation preference is the investor's right to be paid first when a startup is sold or wound down. Before founders, employees, or any common shareholders receive exit proceeds, preferred investors are made whole — typically at 1× their invested capital. Whatever remains after the preference is satisfied is distributed to common stockholders.
Does liquidation preference apply in an IPO?
No. At an IPO, preferred shares convert to common stock and the liquidation preference dissolves. It is only triggered in liquidity events classified as a sale, merger, or dissolution — not a public offering. This is why a company can be "worth" $500M on paper and preferred investors still receive exactly their preference in a $40M acquisition.
What is the difference between 1× participating and 1× non-participating?
With 1× non-participating, the investor receives either their preference or their pro-rata equity value as converted common — whichever is larger. With 1× participating, they receive their preference and their pro-rata equity value. Participating preferred means investors are paid twice, which is significantly more dilutive for founders and employees in moderate-exit scenarios.
Is a 2× liquidation preference standard in VC deals?
No. The market standard in institutional VC rounds today is 1× non-participating. A 2× multiplier signals a bridge round under pressure, a down round, or a structured deal with elevated risk perception on the investor's side. Treat it as a negotiating signal and always model the impact before accepting.
How does liquidation preference affect employee stock options?
Employee options convert to common shares upon exercise. Since preferred investors are paid before common shareholders, options may be worth little or nothing in exits where the preference stack consumes most proceeds. A heavily preferred cap table can demotivate key team members — their equity may be effectively worthless even when the company sells for a meaningful number.
Understanding your liquidation waterfall is one of the most important steps before accepting any term sheet. VC Match helps founders connect with venture investors who structure deals transparently and align with founder outcomes. Find your investor →
Tagged with:
Related Articles
Startup Equity Vesting: The Complete Founder's Guide
Key takeaways• Standard structure: 4-year vesting with a 1-year cliff is the default for founders and employees — dev...
What Is a Cap Table? A Founder's Complete Guide
Most founders think their equity is simple until they sit down across from a Series A investor and hear, "We have som...