How to value your company at different stages
Founders often ask for a single, clean answer to the question of valuation. What’s my company worth right now? The uncomfortable truth is that valu...
Founders often ask for a single, clean answer to the question of valuation. What’s my company worth right now? The uncomfortable truth is that valuation is less about formulas and more about context. The way your company is evaluated changes dramatically as you move from idea to early revenue to real scale. Understanding how investors think about valuation at each stage helps you set realistic expectations, avoid over- or under-pricing your round, and have more credible fundraising conversations.
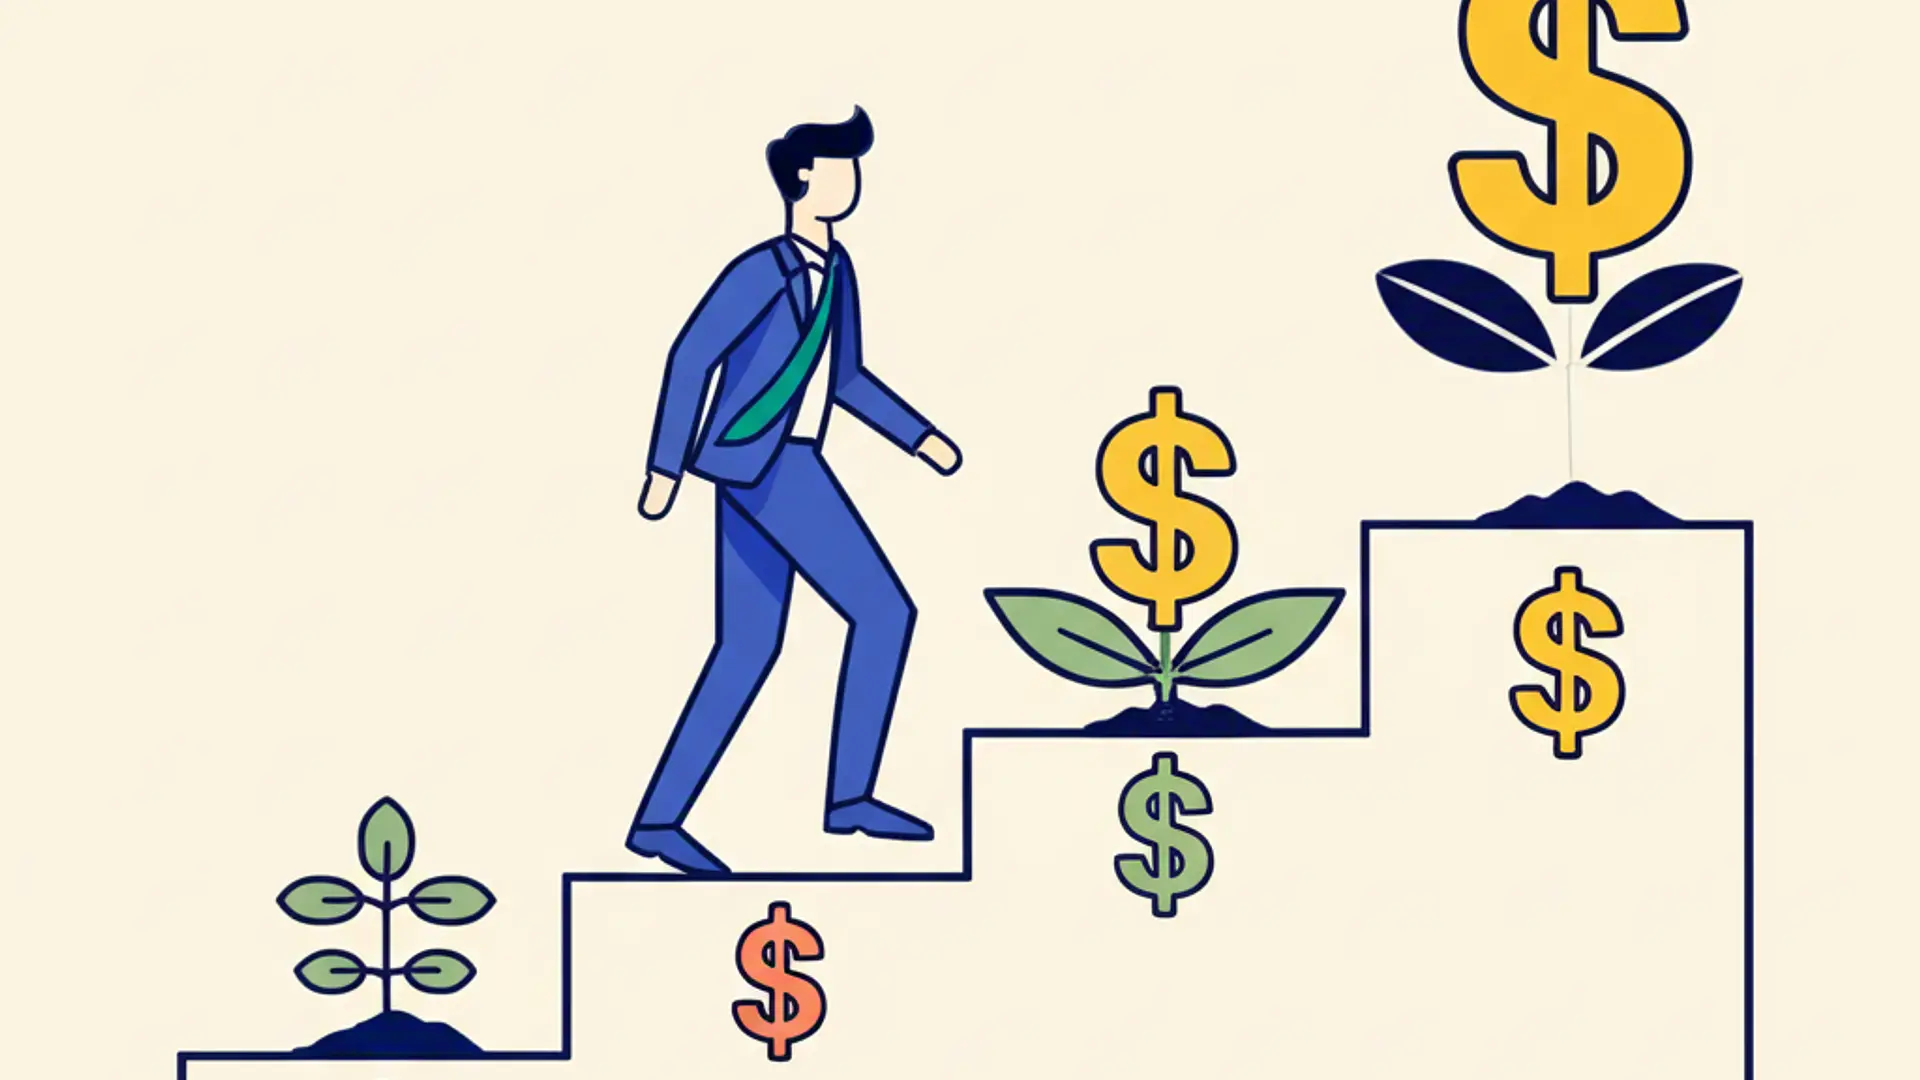
At the earliest stages, valuation is almost entirely narrative-driven. Pre-seed and seed companies are rarely valued on financials because there usually aren’t any that matter yet. Investors are underwriting the team, the problem, and whether the market is big enough to justify venture risk. At this point, valuation tends to cluster around market norms rather than precision. Comparable rounds, founder experience, speed of early traction, and clarity of vision all matter more than spreadsheets. A first-time founder with an unproven idea will be evaluated very differently than a repeat founder tackling a known pain point, even if neither has revenue. This is why pre-seed valuations often look similar across wildly different businesses: they reflect risk tolerance, not performance.
As companies move into seed and early traction, the evaluation framework starts to shift. Investors still care deeply about the story, but now they want evidence that reality is starting to match the pitch. Early revenue, pilots, user growth, or strong engagement metrics begin to anchor valuation conversations. This is where founders often make mistakes by stretching numbers or presenting projections as facts. Seed-stage valuation is less about how big the company could be someday and more about whether the early signals justify further capital. A modest amount of high-quality traction with honest metrics will usually outperform inflated claims every time.
By the time a company reaches Series A, valuation becomes much more structured. Investors are no longer betting on potential alone; they are underwriting execution. Revenue quality matters more than revenue size. Is it recurring? Is it contracted? Is growth consistent or spiky? Cohort behavior, retention, sales efficiency, and gross margins all begin to directly influence how investors think about price. At this stage, valuation often emerges from a combination of forward revenue multiples and risk adjustments based on growth rate and capital efficiency. The narrative still matters, but it must be supported by clean data and a clear path to scale.
Later-stage companies are evaluated in an entirely different language. Growth rate, unit economics, and predictability dominate the conversation. Investors compare companies against public market comps, recent private transactions, and sector-specific benchmarks. Valuation becomes less forgiving because the margin for error is smaller. Strong companies with slowing growth can see compressed multiples, while companies with durable growth and expanding margins are rewarded disproportionately. At this stage, credibility is everything. Missed forecasts or aggressive accounting can permanently damage investor trust and materially impact valuation.
Across all stages, one principle stays constant: honesty compounds. Founders who are transparent about what they know, what they don’t, and where the risks are tend to build stronger investor relationships and achieve better long-term outcomes. Valuation is not a scorecard; it is a tool to align incentives between founders and investors. The best outcomes happen when valuation reflects both ambition and reality at that specific moment in time.
If you want to dig deeper into how investors think about early-stage pricing and metrics, Carta’s overview of startup fundraising provides a solid baseline for valuation norms across stages: https://carta.com/learn/startups/fundraising/. Understanding where your company truly fits in its lifecycle is the first step toward pricing your round intelligently—and raising capital from the right partners for the stage you’re actually in.
Related Articles
Series A Funding: What It Is, What Investors Want, and How to Raise It
Most founders treat Series A like a bigger seed round. It isn't. The investors are different, the bar is different, a...
What Is a Term Sheet? A Founder's Complete Guide to VC Term Sheets
Key takeaways• A term sheet is a non-binding document outlining the key economic and governance terms of a venture in...